

- Insights
- Market Insights
- 2027 Year-Ahead Outlook
2027 Outlook · J.P. Morgan Asset Management
Finding Balance in a Moderating Economic Environment
If 2026 was the year of boom and doom, 2027, at least from an economic perspective, should be a year of moderation. Growth slows, inflation slides and AI keeps reshaping earnings, so how you rebalance matters.
Audio summary · 3 min
Listen to the executive summary
0:00 / 3:00
Finding Balance in a Moderating Economic Environment.
After a tumultuous 2026, 2027 should see an economy of moderation. Economic growth should slow, reflecting less fiscal stimulus, a deceleration in still-growing AI-related capital spending and weak demographics impacting both labor supply and consumer demand. Job growth should remain weak, even as the unemployment rate drifts down. And inflation should slide, assuming that a wind-down of the war with Iran allows energy prices to fall and tariff rates to stay flat or decline, as Washington focuses on attacking the affordability problem.
In this environment, the Federal Reserve could feel comfortable in raising interest rates just once more in December, in a more dovish stance than is currently priced in futures markets. This could leave long-term yields range-bound near current levels with fixed income providing better yields than for most of the period since the Great Financial Crisis. That being said, heavy borrowing from both sovereign issuers and corporations financing the AI buildout could limit any rally in bonds if the stock market falters.
The outlook for corporate earnings remains positive, reflecting strong capital spending and corporate success in maintaining margins. However, both U.S. and EM equity indices are heavily exposed to the AI boom, underscoring the need for active management and broader international exposure.
Alternatives can also continue to play an important role in stabilizing portfolios given less potential for bond market gains to offset stock market losses. That being said, investors should recognize the exposure of many alternative assets to the AI theme dominating public markets and diversify among alternatives accordingly.
Finally, investors should recognize that the strong gains in U.S. equity markets over the past four years may have left them overexposed to U.S. stocks in general and mega-cap tech stocks in particular. While our baseline forecast is one of moderation, shocks, by definition, cannot be forecast, and the best protection against shocks should come from thoughtful and tax-efficient rebalancing.
01 Economy
If 2026 was the year of boom and doom, 2027, at least from an economic perspective, should be a year of moderation.
Economic growth should continue to reflect a very divergent and K-shaped economy.
Capital spending on equipment, intellectual property and all the infrastructure associated with the AI buildout will continue to be very strong, although it could grow more slowly than in 2026 as it runs into potential hurdles of local opposition to data centers and, potentially, some regulatory pushback. Higher interest rates and the reality that hyperscalers are now having to tap capital markets in a big way to fund the buildout could also slow the pace of expansion. Despite this, a capital spending boom and strong consumer spending among the richest households should help drive the economy forward.
On the negative side, weak job growth, wage growth and demographic growth should all inhibit consumer spending by lower- and middle-income households. Political gridlock after the midterm elections will likely rule out any further fiscal stimulus or tax breaks, and, without this, we expect overall real consumer spending growth that is closer to 1% than 2%.
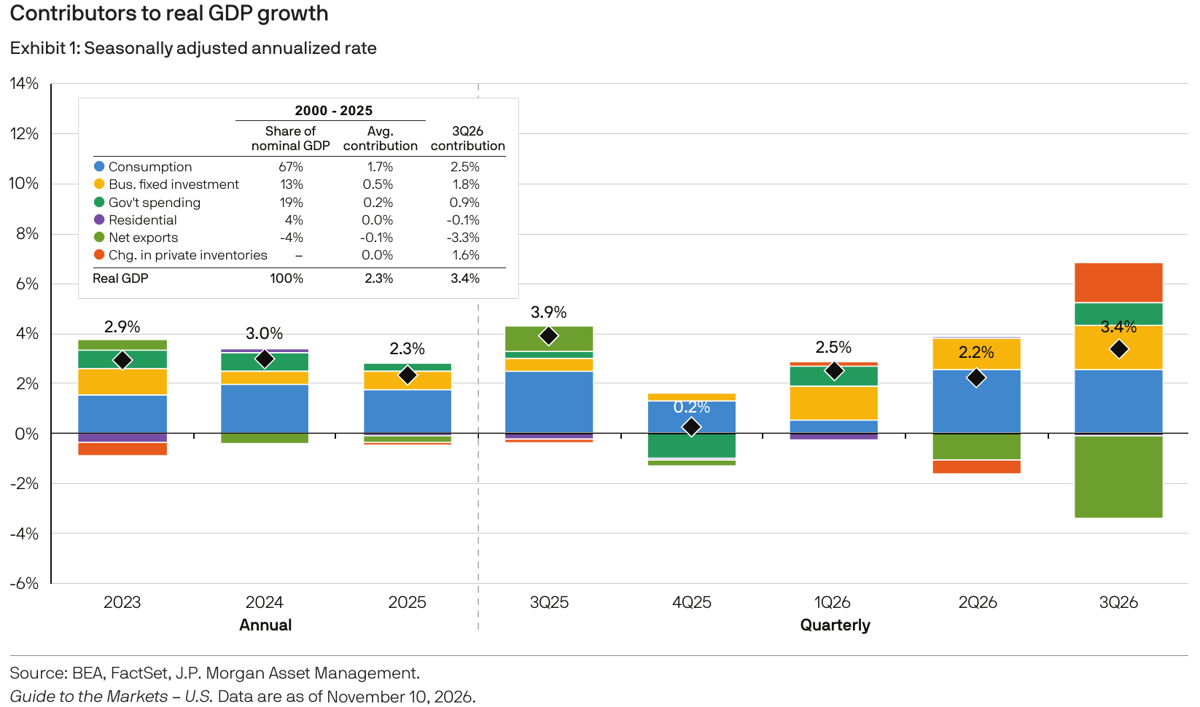
Other areas of weakness include housing, which is being impacted by high mortgage rates, at least by recent standards, and very weak demographics. A surge in imports, mainly due to the AI buildout, will also continue to drag on growth, while state and local government spending will be subdued due to very slow growth in the tax base for sales taxes, property taxes and personal income taxes. Putting it all together, we expect real GDP to climb by 1.6% over the next four quarters compared to 2.5% in the year ending in the fourth quarter of 2026.
On jobs, we expect payroll employment growth to remain lackluster despite moderate economic growth. Looking at the relationship between real GDP growth and job gains over the past 40 years, the 2.3% real GDP growth seen between the third quarter of 2024 and the third quarter of 2026 should have led to a monthly gain of roughly 155,000 net new jobs over the past two years. However, monthly job growth has averaged just 48,000 since September 2024. We believe this pattern mainly reflects a lack of available workers due to a sharp reversal of immigration policy over the past two years, and we expect this pattern of roughly 50,000 net new jobs per month to continue in 2027. However, because of a lack of labor supply, we expect the unemployment rate to drift down to below 4% over the course of the next year.
Despite a tight labor market, real year-over-year wage growth has been negative for seven consecutive months, and we expect wage gains to remain meager in 2027.
We also expect to see a pattern of moderation in inflation.
Headline CPI inflation climbed to over 4% year-over-year in October, almost matching its spring peak of 4.1% in May. The inflation surge has largely been caused by higher energy prices due to the Iran war, the feedthrough effects of higher tariffs over the past two years, fiscal stimulus in the form of bumper income tax refunds, still sticky housing inflation as measured by the Bureau of Labor Statistics and the impact of the AI buildout on consumer electronics prices.
In 2027, we expect many of these forces to fade. In particular, we believe some compromise is likely in the Middle East to allow for a resumption of more normal flows through the Strait of Hormuz. Divided government should allow for a further whittling away of tariff rates while dimming the possibility of further fiscal stimulus. In addition, a steady rise in the rental vacancy rate should subdue rents on new leases, allowing for a gradual decline in measured inflation. Given this, even if AI spending remains robust, we expect headline consumption deflator inflation to drift down from 3.7% year-over-year in the fourth quarter of 2026 to 2.3% by the fourth quarter of 2027.
02 Fixed income
FOMC: Swapping hawks for doves
The Federal Reserve will look different next year. As usual, four Reserve Bank presidents will rotate onto the 12-member voting Federal Open Market Committee (FOMC), a shift that could matter as policy evolves. Since Warsh became Chair, three of the four rotating presidents have dissented in favor of raising rates over the past three meetings. In 2027, however, three hawks appear likely to give way to three more patient doves, reducing the risks of aggressive tightening.
We expect a rate hike in December 2026, with upside risk of another hike in March 2027 if inflation proves more persistent. Thereafter, we expect the Fed to pause for an extended period as it assesses the effect of tighter policy on growth and prices.
Moreover, a new era of forward silence is beginning to take shape at the Fed. Chair Warsh has recently outlined a schedule under which seven of the eight meetings in 2027, and six of eight in 2028, would be “live” meetings to consider policy changes. As a result, there will generally be longer stretches between policy decisions, placing greater weight on each meeting. Altogether, a more patient Fed and fewer policy signals call for humility in forecasting policy rates.
Stay in your lane, long rates
We expect the U.S. 10-year Treasury yield to spend much of 2027 in a 4.75% to 5.25% range. Normalizing growth, gradually cooling inflation and a patient Fed should keep yields from rising sharply, barring another external inflation shock.
A substantial decline also seems unlikely outside a recession or severe market correction, neither of which is our base case. Elevated fiscal deficits and debt-service costs will sustain Treasury financing needs, while government and corporate issuance compete for investor capital. A higher neutral federal funds rate also makes a return to the old low-yield regime unlikely. We foresee more than $2 trillion of net privately held Treasury borrowing in 2027. While we expect the Treasury to rely on bills and shorter-dated issuance rather than abruptly increasing long-bond supply, it does not erase the effects of persistent deficits and rising debt levels.
Tight spreads amid climbing supply
Over the past two years, credit spreads have spent 80% of the time in the top decile of historical tights, while all-in yields have spent 70% above 5%. Attractive yields have compensated for tight spreads, and we expect that dynamic to continue, though with wider dispersion under the surface. Strong expected corporate earnings should contain defaults, leaving supply as a key driver of sector spreads and relative performance.
We expect roughly $265 billion of hyperscaler USD-investment-grade issuance in 2027, up from $225 billion this year to finance AI infrastructure. This volume has tested investors’ appetite for duration and has caused technology spreads to widen, but more issuance does not mean a broad deterioration in credit.
If earnings growth remains strong as we expect, issuers should be able to service their debt, and investors should continue to find value in all-in yields. We expect spreads to widen modestly but remain tight historically. Security selection will be key as the market distinguishes well-funded AI investment from borrowing reliant on overly optimistic future returns.
Investment implications
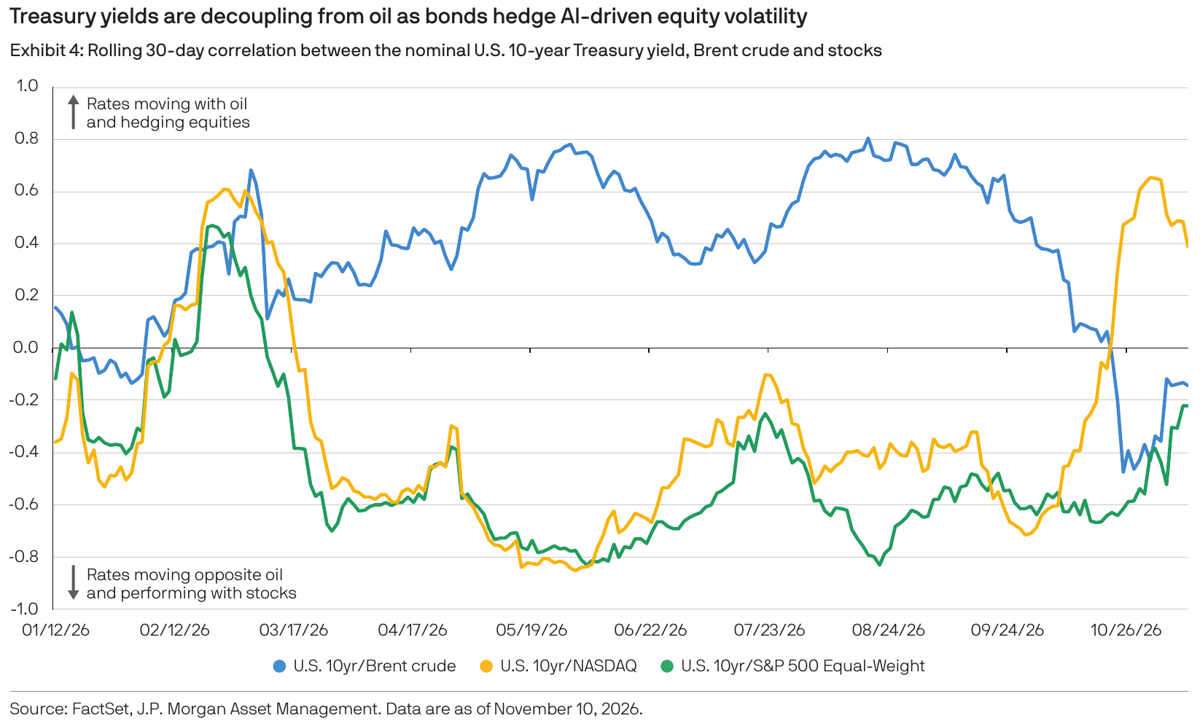
Fed tightening and supply-side inflation shocks have challenged fixed income’s role as a portfolio diversifier. However, it’s worth emphasizing that yields remain attractive, and encouragingly, bonds have recently proven they can still be an effective hedge.
Treasury yields tracked oil for most of 2026, rather than moving against equities. More recently, yields have become strongly correlated with the NASDAQ, i.e., when the AI trade weakens, Treasuries have benefited. High-quality duration can therefore still provide portfolio ballast in 2027, particularly amid sensitivity to hyperscaler capital spending, even if rates remain elevated and rangebound.
03 Equities
U.S. equities enter 2027 with a strong fundamental backdrop and the potential for a more favorable market environment. Corporate earnings have been exceptional in 2026, with expectations for S&P 500 earnings growth more than doubling from 15% at the start of the year to 33% today, an unusually strong pace for a non-recovery year. Yet despite these upgrades, the S&P 500 has gained just 10.9% year-to-date, as valuation multiples have contracted 17.4%.
Looking ahead, consensus expects earnings growth of 16% in 2027 and 17% in 2028. If companies can deliver, earnings should remain a powerful tailwind for equities. Easing uncertainty around interest rates, geopolitics and returns on AI investment could also support a recovery in multiples. Meanwhile, broadening earnings growth could provide a more balanced foundation for markets, as strength across sectors helps offset intermittent tech weakness.
Can the AI boom continue to deliver?
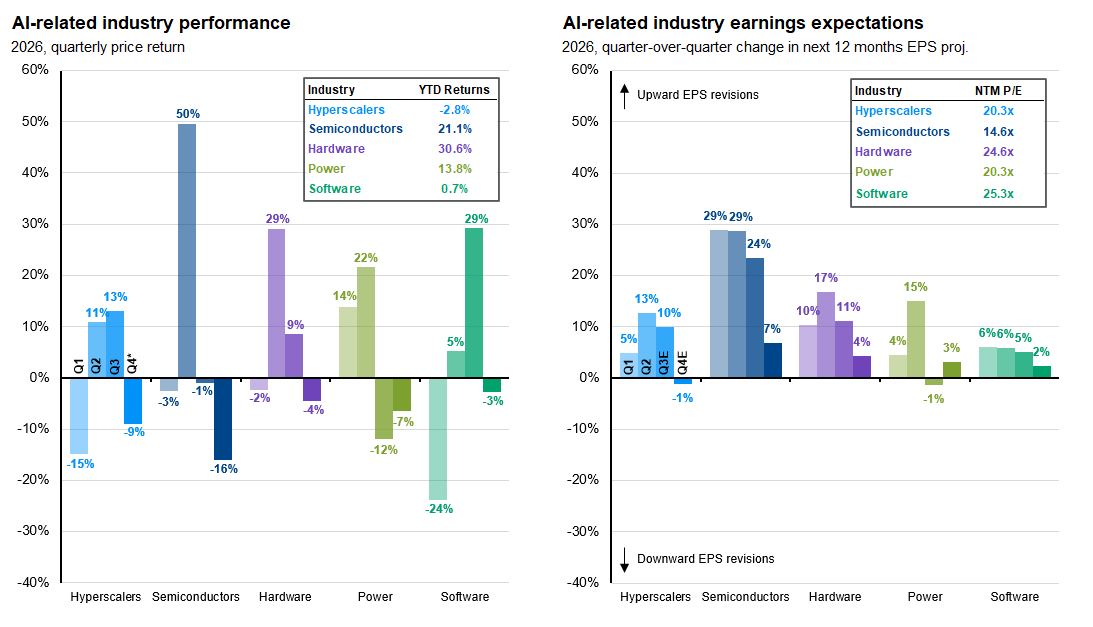
The AI buildout should remain a powerful earnings engine, although its rewards will be uneven. Consensus expects hyperscaler capital spending growth to slow from 93% in 2026 to 44% in 2027, but upward revisions appear likely. Strong cloud demand, expanding AI workloads and persistent power and computing bottlenecks should benefit semiconductor manufacturers and suppliers of electrical equipment, networking and other critical infrastructure. These businesses remain among the clearest beneficiaries of the AI boom.
For the hyperscalers funding the buildout, the economics are more complicated. Strong cloud growth and contracted backlogs demonstrate robust demand, but investment is absorbing free cash flow and increasing reliance on costly external financing. AI also threatens some of the profitable legacy businesses helping fund the buildout. Investors must weigh these pressures against a multiyear opportunity whose full benefits will take time to materialize.
What could restore confidence in the AI trade? Primarily, evidence that spending is translating into durable value:
Revenue conversion: Cloud growth, AI workloads and contracted backlogs translating into realized, recurring revenues.
Improving economics: AI revenues growing faster than inference, power, networking and depreciation costs, supporting margins.
Capital discipline: Attractive incremental returns, sustainable financing and a path toward stronger free cash flow.
Progress here, alongside easing financing pressures and infrastructure bottlenecks, could support a recovery in valuations. Conversely, intensifying competition, disruption to legacy businesses or monetization lagging rising costs could prolong market skepticism, even amid robust demand.
Who will benefit as AI adoption spreads?
Alongside the buildout, corporate AI adoption is accelerating but remains early. Nearly two-thirds of large companies are building or deploying AI agents, yet barely one in 10 has scaled them across the business. On Ramp’s platform, the median AI-paying firm spends just $16 per employee monthly, versus over $800 for the top 10%. As useful and reliable applications emerge, spending should broaden across industries and functions.
That creates opportunities for adoption enablers: enterprise software, cybersecurity, data providers and consultants integrating AI into workflows. Early leaders may also be distinguished by proprietary data, domain or regulatory expertise and network effects. For most end users, however, productivity gains will likely take time to identify and remain difficult to measure.
AI will also be disruptive. The so-called “SaaSpocalypse” earlier this year showed how quickly markets can reassess earnings prospects and valuations when AI threatens established business models. Yet disruption also creates opportunities for incumbents to reinvent themselves and for successful adopters to gain a competitive edge. Over time, AI should support a more productive and profitable corporate America, but the path will be bumpy.
Several sectors also have less AI-centric earnings catalysts: health care from drug innovation and recovering fundamentals, financials from capital market activity and lending and select industrials from aerospace, defense and manufacturing investment. These additional tailwinds could help support markets when technology leadership falters.
Overall, less demanding valuations and a strong earnings backdrop leave us constructive on equities in 2027. But rapid technological change will challenge investors’ assumptions about future earnings and appropriate valuations, driving market dispersion and bouts of volatility.
04 International
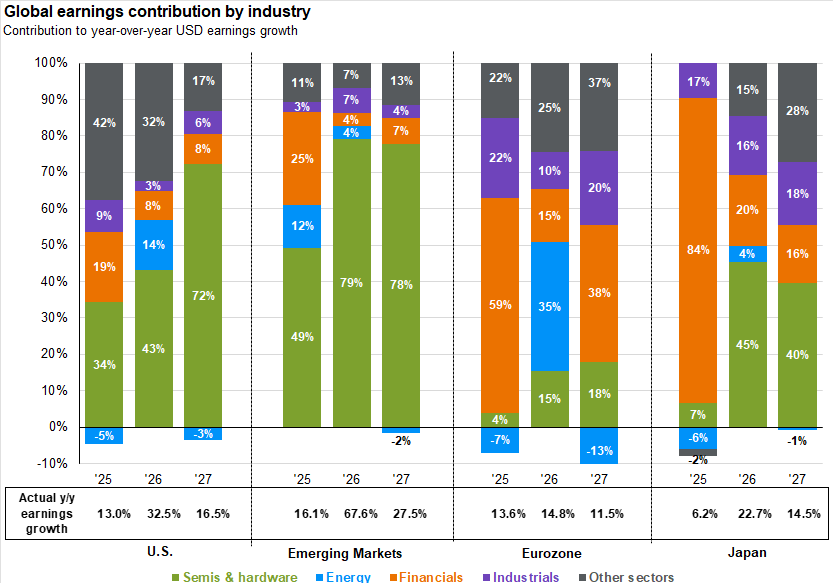
2026 was another solid year for international equities, with the MSCI All Country World Index ex-U.S. up 11.3% (as of Nov 10th) (in line with the S&P 500). This was the year that the earnings supercycle went global, with above-average earnings growth in all the major regions: emerging markets (EM) +66%, Japan +22% and the eurozone +15% (in U.S. dollar terms). Breaking down this year’s returns, it was all about earnings: The upward revisions to international earnings growth expectations boosted returns by 34%. On the other hand, multiples contracted 23% and currencies weakened versus the U.S. dollar by 2.0%. 2027 may see a different breakdown, with multiples doing the heavy lifting as investors better appreciate the continued robustness of global earnings.
There have been many factors behind these strong earnings, including solid global economic growth, moderately higher interest rates, elevated fiscal spending, higher energy prices and, of course, the AI-related capex cycle. As in U.S. equities, industries related to the AI buildout saw the strongest upward revisions to earnings expectations and, hence, the strongest returns. This meant that Asia was the star of the show given its heavy concentration in “hard tech,” especially semiconductors. EM Asia was up 14% (led by Korea and Taiwan) and Japan (led by its tech sector) was up 14%.
2027 should be another year of solid, above-average global earnings growth, albeit with some moderation versus 2026’s extraordinary surge (as in the U.S.). The AI buildout has been and is set to continue to be a major contributor to global earnings growth, especially in EM. Semis and hardware have contributed nearly 80% to EM earnings growth this year and a similar contribution is expected for next year as demand for chips and hardware is set to far outstrip supply for another year. This is also expected to continue to be a key driver for Japan, with these hard tech sectors expected to contribute a similar 41% to Japanese earnings growth next year.
But next year is unlikely to be a repeat of this year in terms of returns, as the AI story moves on to a new chapter. Investors are expected to remain wary of the AI capex phase itself, especially with the upcoming expected deceleration in 2028. Instead, investors are likely to remain focused on AI’s adoption and monetization. That means returns in markets like Korea and Taiwan may moderate, but does not mean there are no opportunities in Asia. China, Korea and Japan remain leaders in the “physical AI” market via industrial robotics, but investors have not given those companies credit (yet).
Next year should also see investors better appreciate other areas of solid earnings growth via higher multiples for non-AI heavy regions and sectors. This is especially true for Europe, which has been underappreciated this year given concerns about France’s fiscal situation and the potential effect of higher energy prices on consumers. Despite that, earnings have been solid, rising 15% year-over-year and 11% expected for next year. Japan also continues to stand out with 15% expected earnings growth, with 59% of that coming from non-hard tech sectors. These earnings are also being driven by secular over cyclical themes: fiscal spending on defense and infrastructure, corporate governance reform and the end of deflation/negative rates. This favors the value style, in particular, which can help diversify portfolios by region, thematics and style, something that will be valuable during the next inevitable AI-related equity market correction in 2027.
05 Alternatives
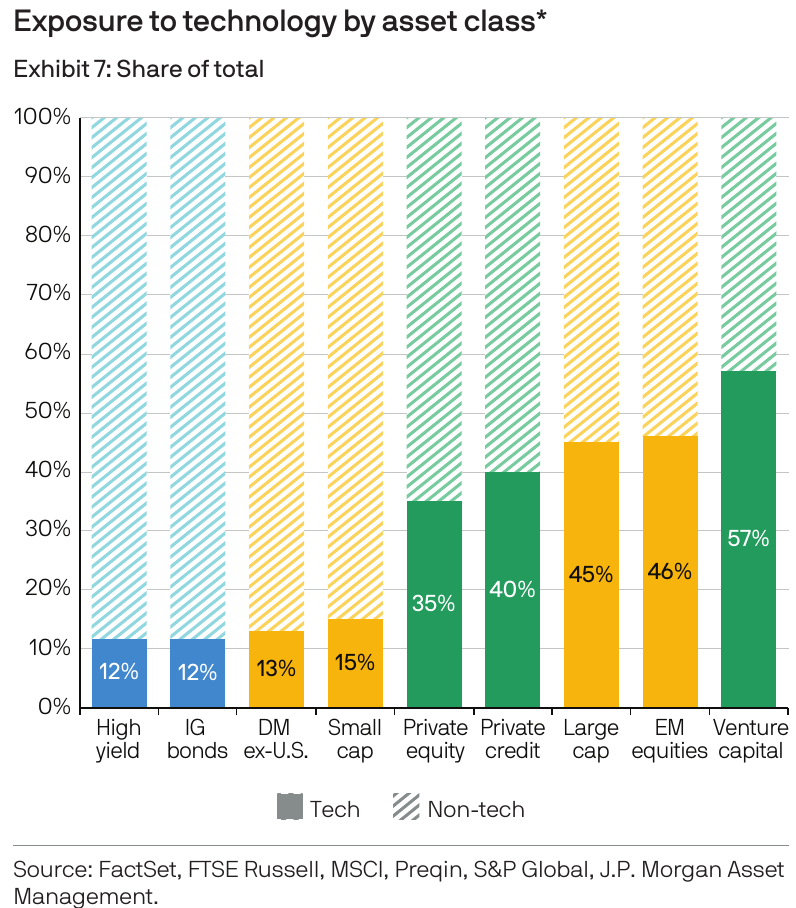
Alternatives have traditionally been viewed as sources of alpha in portfolios, but coming into 2027, the diversification benefits are arguably just as important for investors looking to preserve long-term gains. In the face of highly concentrated and technology-focused public markets, the breadth of the private markets opportunity set and the ability to access genuinely differentiated sources of return are important factors.
Genuine hedging from tech volatility can be found in sectors that are inherently unconnected to the AI trend such as real estate, infrastructure or private equity. More nuanced exposures to areas of the AI buildout theme that are not available on public markets today, such as pre-IPO companies or financing of high-growth tech companies, can be accessed through investments in venture capital or private credit.
Alternatives are not immune to the macro environment, and in 2027 investors in alternatives must evaluate their portfolios in the context of rising interest rates and persistent inflation. Markets have now spent several years adapting to more expensive capital, and modest additional tightening does not dramatically change the investment calculus. But a more demanding financing environment means that managers cannot easily add costly leverage to enhance returns, and must add value in different ways.
Private equity: Back to basics
In private equity, higher financing costs put the focus on finding unique and compelling high-growth companies to invest in, as well as squeezing out margin expansion through operational improvements.
Many of today’s leading AI companies, and potentially some of the next decade’s winners, remain privately held. Private equity and venture capital therefore provide important access to innovation that public markets alone cannot capture.
Outside of the tech space, there is potential for healthy returns and diversification in the small and middle market of private equity, where established businesses in traditional industries can benefit from new capital, commercial expansion and technology adoption. The beneficiaries of AI need not all be companies developing the technology. Many will be smaller businesses that use it to improve productivity within their own specialty domains.
Private credit: Resilient, but under scrutiny
Despite the headlines warning of looming risks in private credit, the asset class has demonstrated resilience. Higher interest rates cut both ways: Since most private credit is in the form of floating-rate loans, coupon income quickly resets higher for investors, but debt-service burdens also rise for the borrowers.
The microscopes have been out and searching for cracks since 2022, and they are unlikely to be put away in 2027 as rates continue to rise. Investors should monitor signs of strain, including greater use of payment-in-kind interest, and assess underlying credit quality and manager capability.
Redemption requests at some interval funds, particularly those with large exposures to software loans (perceived as a risk by some in the age of AI), have tested investor confidence. This is an important learning opportunity for a maturing market. Investors need to assess whether a fund’s structure suits their time horizon and liquidity needs. Private credit can enhance returns over the long run. But, like all alternatives, it comes with the trade-off of potentially lower liquidity.
Real assets: Recovery and reinvestment
Real estate is showing signs of recovery, but the diversity of the market (spanning residential, commercial and industrial property) means that many trends are at play under the surface.
Financing costs and refinancing needs remain challenges for sectors like office. But there are reasons for optimism elsewhere. The same higher rates that have challenged property valuations have also constrained new development. Over time, growing demand can improve the supply-demand balance and lead to higher property valuations. Higher mortgage rates mean that more families are renting rather than buying homes, which can be a tailwind for portfolios containing apartment buildings.
Infrastructure benefits from a number of broad mega-trends. Rising electricity demand and aging power grids mean there is a great need for investment in new and replacement infrastructure. Energy-hungry data centers are accelerating the urgency, but much of the spending addresses the more mundane tasks of modernizing energy systems and building the resilience required for decades to come.
Hedge funds: Opportunities in dispersion
For hedge funds, 2026 brought substantial movements in interest rates, currencies, commodities and equity markets. These created opportunities for macro and relative-value strategies, although abrupt reversals also caught some managers offside.
For hedge funds, volatility is opportunity, and so, looking ahead, we see a favorable environment for skilled active managers. The market’s intense focus on AI has contributed to valuation dispersion and, in some cases, left less fashionable sectors overlooked.
06 Asset allocation
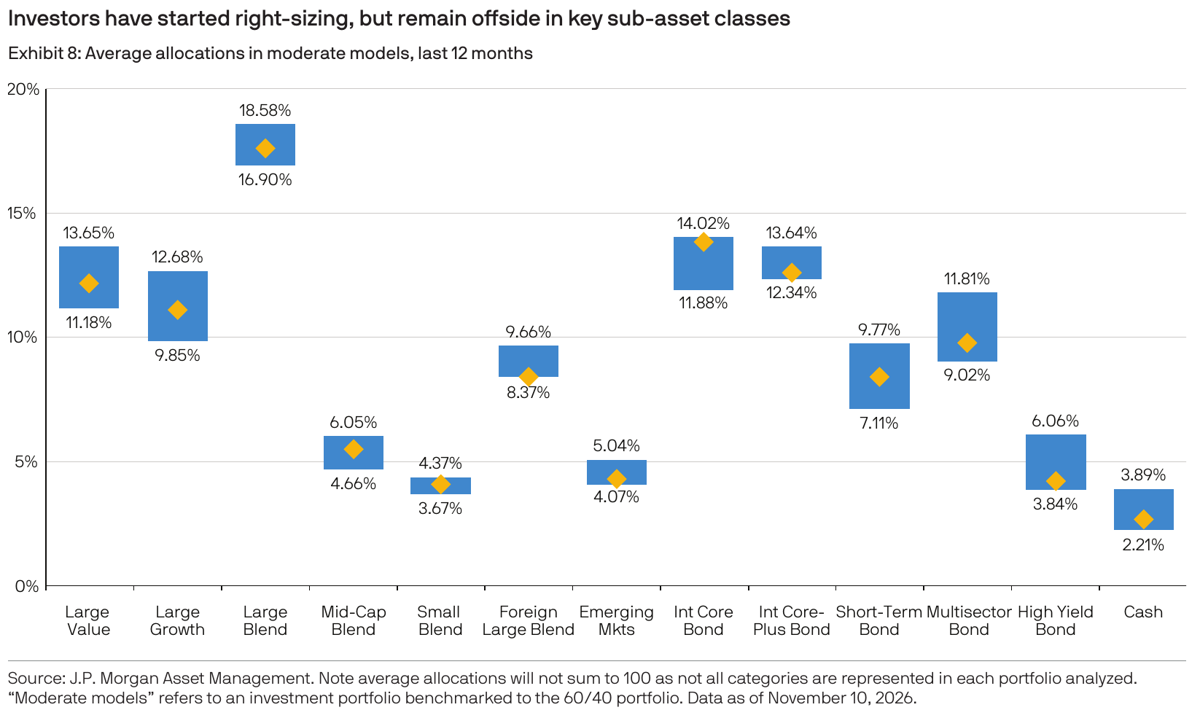
Over the course of many years, truly diversified portfolio construction (cross-asset and cross-geography exposure) had slowly become unpopular. This is because certain assets had consistently outperformed their counterparts: stocks over bonds, growth equity over value and U.S. over “international.” In 2025, that changed: The opportunity set shifted dramatically, with bonds rallying and the ex-U.S. equity market surging. Looking back on 2026, it appears that many investors were successful in “right-sizing” their portfolios to re-position in the face of those shifts.
When thinking about portfolio construction in 2027, the benefits of diversification should be more apparent than ever, and investors must ask themselves a series of outcome-oriented questions: Are they looking for income, capital preservation or growth? Are they tolerant of volatility or risk-averse? And is liquidity a concern? The answers inform allocation decisions, and both traditional and alternative assets play a role.
How these assets will perform is tied to the macro backdrop. Here, the picture is as muddled as ever: Growth is cooling but not cold, with a low unemployment rate obscuring a meaningful slowdown in job creation and tepid wage growth, and consumption progressing unevenly between the wealthiest and the less fortunate; headline inflation is persistently warm on higher energy prices, but core price growth is in check; and significant policy changes are underfoot. All of this has translated into a dramatic repricing in interest rates across the curve, which has led in part to volatility in markets.
Beneath this volatility the opportunity set has shifted again. Fixed income faces near-term headwinds with a recent Fed pivot, but the asset class is arguably more attractive thanks to higher starting yields. However, while allocations to intermediate core bonds have increased to near 12-month highs, 80% of investors remain underweight duration relative to the Bloomberg U.S. Aggregate. This may be an opportune time to revisit that allocation, as yields have arguably repriced too aggressively and could have room to drift modestly lower. That said, investor sentiment will ultimately inform the appropriate strategy: Concerns around a slowing economy would suggest an extension in duration, for example, as current yields make bonds an effective ballast against recession. The credit conversation follows a similar path: While a benign macro backdrop supports a greater allocation to credit, the slowing economy would encourage an emphasis on active management.
In equities, the AI trade has broadened out beyond the “Magnificent 7” over the past several years and now encompasses names across both the value and growth parts of the U.S. stock market. While greater participation is encouraging, the concentration is unnerving, and between deep AI penetration and a major index rebalancing, portfolios that have shifted U.S. equities toward a more balanced value and growth allocation continue to be exposed to elevated levels of stock-specific risk. In addition, interest in foreign markets has remained resilient after rebounding in 2025. Over the course of the year, the average allocation to ex-U.S. equities has risen from 20% to 25%, a meaningful increase but still well below what is considered “diversified.”
These allocations lead to missed opportunities: Structural shifts in foreign markets, which led to improved fundamentals in 2025, have persisted, allowing them to continue to compete with the added benefit of minimal AI exposure in developed markets outside of the U.S. Moreover, while the breadth of U.S. equity market performance once again hasn’t improved as much as initially expected, it is trending in the right direction: The “Magnificent 7” has accounted for less of 2026’s S&P 500 performance than in previous years and earnings growth continues to broaden out. That said, with a continued earnings supercycle already embedded in forward estimates, today’s compressed multiples are only as attractive as those earnings prove durable, which argues for a bigger role in 2027 for select value sectors whose earnings are less dependent on the AI theme, though growth should continue to fare well as the long-term secular force of AI continues to mature. In other words, portfolios should be balanced.
For alternatives, the outcome-oriented approach toward portfolio construction is particularly relevant. Public equity returns increasingly hinge on AI-related earnings following through, while heavy AI-related issuance is adding to bond supply and could limit any rally in bonds if stocks falter. With both sides of the traditional portfolio increasingly tied to the same theme, alternatives less exposed to AI, such as real estate, infrastructure and select private equity, can offer a more differentiated source of diversification. These assets will also become increasingly approachable despite some headline risk, as regulatory shifts and technology continue to “democratize” access through lower minimums and greater liquidity. For this reason, the traditional stock/bond framework of “60/40” should be reformed into one that also includes alternative assets: a “60/40+,” for example, where, depending on desired outcome, alternative assets are folded in to complement public holdings, should result in stronger, less correlated returns with reduced volatility.
All told, while the traditionally diversified portfolio may not be as relevant as before, this is because it has evolved, not because it is unnecessary. In fact, as policy change reshapes the global landscape and the investment backdrop shifts, rebalancing into a well-diversified portfolio is more critical than ever. Unfortunately, that rebalancing has a cost: taxes. For this reason, investors should also incorporate tax management into portfolio construction in 2027, with an emphasis on ETFs for their tax efficiency and “tax loss harvesting” to improve after-tax outcomes.
Six sections. One year of moderation.
-
 01 Economy3-min read
A path of moderation
“Economic growth should continue to reflect a very divergent and K-shaped economy.”
 Read the economy section
-
 02 Fixed income3-min read
Swapping hawks for doves
“Yields remain attractive, and encouragingly, bonds have recently proven they can still be an effective hedge.”
 Read the fixed income section
-
 03 Equities3-min read
Strong growth amid disruption
“The AI buildout should remain a powerful earnings engine, although its rewards will be uneven.”
 Read the equities section
-
 04 International3-min read
Giving credit where credit is due
“2027 may see a different breakdown, with multiples doing the heavy lifting as investors better appreciate the continued robustness of global earnings.”
 Read the international section
-
 05 Alternatives4-min read
Diversification, not just alpha
“Coming into 2027, the diversification benefits are arguably just as important for investors looking to preserve long-term gains.”
 Read the alternatives section
-
 06 Asset allocation4-min read
From 60/40 to 60/40+
“While the traditionally diversified portfolio may not be as relevant as before, this is because it has evolved, not because it is unnecessary.”
 Read the allocation section
Frequently asked questions
The 2027 Year-Ahead Investment Outlook, “Finding Balance in a Moderating Economic Environment,” is the Market Insights team’s view of the year ahead. In brief:
- We expect 2027 to be a year of economic moderation as less fiscal stimulus and a deceleration in the AI buildout constrain growth and lower tariffs, lower energy prices, mild wage increases and strong productivity gains all lead to cooler inflation.
- After one or two further rate hikes, we expect the Fed to go on hold. Falling inflation and continued economic growth should prevent a sharp rise in Treasury yields or credit spreads, and bonds should continue to provide reasonable income even after inflation.
- AI should continue to drive equity returns and earnings in 2027. However, risks around AI funding and regulation point to the need to diversify across AI innovators, enablers and adopters, as well as sectors less impacted by the AI boom.
- Technology will remain a key driver of foreign stocks in 2027, but less exclusively so than in 2026 and with more volatility, suggesting investors should take an active approach toward international equity investing, including adding European and Japanese stocks that are less tech-heavy than EM indices.
- Alternatives can play an important role in stabilizing portfolios given less potential for bond market gains to offset stock market losses.
- Following super-strong U.S. equity performance in recent years, many investors may find that they have more exposure to mega-cap tech stocks than they intended, pointing to the need for thoughtful and tax-efficient rebalancing.
Economic growth should slow, reflecting less fiscal stimulus, a deceleration in still-growing AI-related capital spending and weak demographics impacting both labor supply and consumer demand.
The economy:
- Political gridlock after the midterm elections will likely rule out any further fiscal stimulus or tax breaks, and, without this, we expect overall real consumer spending growth that is closer to 1% than 2%.
- State and local government spending will be subdued due to very slow growth in the tax base for sales taxes, property taxes and personal income taxes.
Markets:
- Elevated fiscal deficits and debt-service costs will sustain Treasury financing needs, while government and corporate issuance compete for investor capital.
- We foresee more than $2 trillion of net privately held Treasury borrowing in 2027.
- Japan: Japan also continues to stand out with 15% expected earnings growth, with 59% of that coming from non-hard tech sectors. These earnings are also being driven by secular over cyclical themes: fiscal spending on defense and infrastructure, corporate governance reform and the end of deflation/negative rates.
Heavy borrowing from both sovereign issuers and corporations financing the AI buildout could limit any rally in bonds if the stock market falters.
- Treasury supply: While we expect the Treasury to rely on bills and shorter-dated issuance rather than abruptly increasing long-bond supply, it does not erase the effects of persistent deficits and rising debt levels.
- Corporate issuance: We expect roughly $265 billion of hyperscaler USD-investment-grade issuance in 2027, up from $225 billion this year to finance AI infrastructure. This volume has tested investors’ appetite for duration and has caused technology spreads to widen, but more issuance does not mean a broad deterioration in credit.
- Europe: Next year should also see investors better appreciate other areas of solid earnings growth via higher multiples for non-AI heavy regions and sectors. This is especially true for Europe, which has been underappreciated this year given concerns about France’s fiscal situation and the potential effect of higher energy prices on consumers.
AI should continue to drive equity returns and earnings in 2027. However, risks around AI funding and regulation point to the need to diversify across AI innovators, enablers and adopters, as well as sectors less impacted by the AI boom.
- For the hyperscalers funding the buildout, the economics are more complicated. Strong cloud growth and contracted backlogs demonstrate robust demand, but investment is absorbing free cash flow and increasing reliance on costly external financing.
- Intensifying competition, disruption to legacy businesses or monetization lagging rising costs could prolong market skepticism, even amid robust demand.
- Both U.S. and EM equity indices are heavily exposed to the AI boom, underscoring the need for active management and broader international exposure.
- Rapid technological change will challenge investors’ assumptions about future earnings and appropriate valuations, driving market dispersion and bouts of volatility.
What could restore confidence in the AI trade? Primarily, evidence that spending is translating into durable value:
- Revenue conversion: Cloud growth, AI workloads and contracted backlogs translating into realized, recurring revenues.
- Improving economics: AI revenues growing faster than inference, power, networking and depreciation costs, supporting margins.
- Capital discipline: Attractive incremental returns, sustainable financing and a path toward stronger free cash flow.
Alternatives have traditionally been viewed as sources of alpha in portfolios, but coming into 2027, the diversification benefits are arguably just as important for investors looking to preserve long-term gains.
- Private equity: Back to basics. In private equity, higher financing costs put the focus on finding unique and compelling high-growth companies to invest in, as well as squeezing out margin expansion through operational improvements.
- Private credit: Resilient, but under scrutiny. Despite the headlines warning of looming risks in private credit, the asset class has demonstrated resilience.
- Real assets: Recovery and reinvestment. Real estate is showing signs of recovery, but the diversity of the market (spanning residential, commercial and industrial property) means that many trends are at play under the surface. Infrastructure benefits from a number of broad mega-trends.
- Hedge funds: Opportunities in dispersion. For hedge funds, volatility is opportunity, and so, looking ahead, we see a favorable environment for skilled active managers.
- That being said, investors should recognize the exposure of many alternative assets to the AI theme dominating public markets and diversify among alternatives accordingly.
The outlook is written by J.P. Morgan Asset Management’s Market Insights strategists:
- Dr. David Kelly, CFA, Managing Director, Chief Global Strategist
- Gabriela Santos, Managing Director, Chief Market Strategist - Americas
- Meera Pandit, CFA, Executive Director, Global Market Strategist
- Jack Manley, Executive Director, Global Market Strategist
- Jordan Jackson, Executive Director, Global Market Strategist
- Aaron Mulvihill, CFA, Executive Director, Global Alternatives Strategist
- Marina Valentini, Executive Director, Global Market Strategist
- Stephanie Aliaga, Vice President, Global Market Strategist
- With research support from Sahil Gauba, Grant Papa, Diago Mosqueira, Aashka Patel and Noble Cooper, Research Analysts.
The Market Insights program provides comprehensive data and commentary on global markets without reference to products. Designed as a tool to help clients understand the markets and support investment decision-making, the program explores the implications of current economic data and changing market conditions.
When thinking about portfolio construction in 2027, the benefits of diversification should be more apparent than ever, and investors must ask themselves a series of outcome-oriented questions:
- Are they looking for income, capital preservation or growth?
- Are they tolerant of volatility or risk-averse?
- And is liquidity a concern?
- The answers inform allocation decisions, and both traditional and alternative assets play a role.
You can explore J.P. Morgan Asset Management's Year-Ahead Investment Outlook right here: each section has its own page, the full report is available as a PDF download, and an audio executive summary with a full transcript sits at the top of this page.
Meet the Strategists