

Week in review
- China Q3 GDP expanded 4.5% y/y
- Japan Sep inflation rose 2.1% y/y
- Bank of Korea kept interest rates unchanged at 3.00%
Week ahead
- Australia Sep and Q3 inflation
- Federal Reserve interest rate decision
- Bank of Japan interest rate decision
Thought of the week
The Fed, ECB, BoJ, RBNZ and BoT are all set to meet this week. While current market pricing implies that only the RBNZ will move forward with an interest rate hike, a hawkish bias is nonetheless expected across central banks as renewed inflation pressure broaden the global tightening cycle. However, the pace of tightening has varied, and is likely to continue to vary across markets. Among the more proactive central banks have been the BSP in the Philippines, which surprised with a 50bps rate increase last week, and the BoK in Korea, which delivered back-to-back rate hikes in July and August, before pausing last week. As such, while markets are still pricing in more tightening, looking further ahead, the magnitude of additional hikes is notably smaller than those with central banks lagging the tightening cycle. The difference in the timing and magnitude of policy tightening, should central banks follow current market pricings, could create pockets of opportunity across currencies and relative duration positions for active fixed income strategies.
Market implied policy interest rate change
Basis points
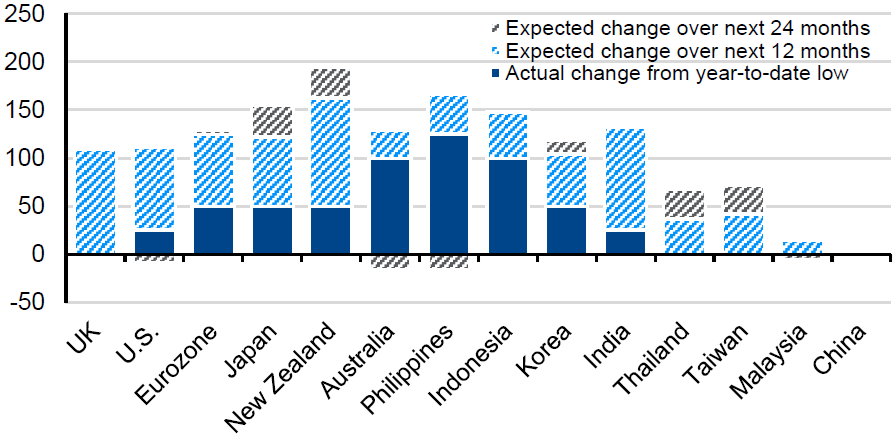
Source: Bloomberg, J.P. Morgan Asset Management. Market expectations are based on forward cash rates. Interest rate for China refers to 7-day reverse repo rates. Past performance is not a reliable indicator of current and future results. Data reflect most recently available as of 23/10/2026.
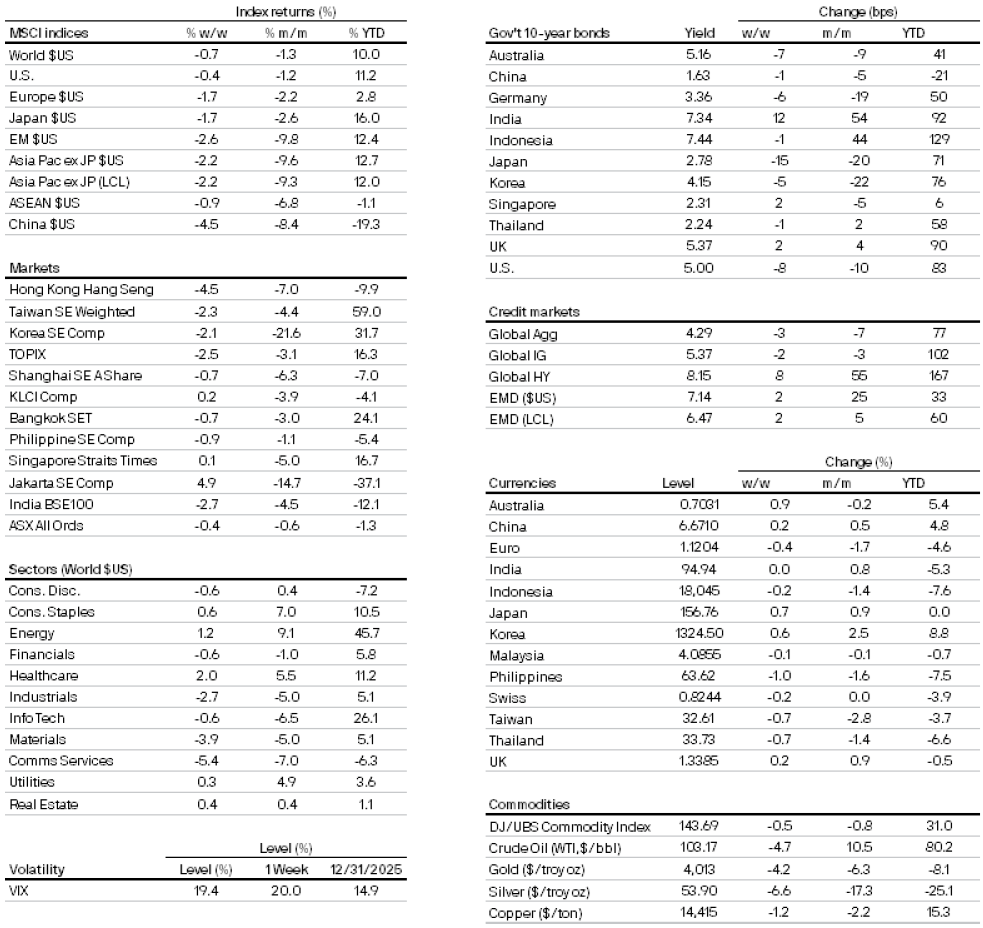
Market data
300a4900-f9d9-11e8-839f-fe2ee17e7f12
All returns in local currency unless stated otherwise.
Currencies’ return are based on foreign currencies per U.S. dollar. An appreciation of the foreign currency against the U.S. dollar would be positive and a depreciation of the foreign currency against the U.S. dollar would be negative.
Feel free to call our InvestorLine or email us if you would like further information about our Funds or J.P. Morgan DIRECT Investment Platform services: