logo
  • Funds

      Fund Listing

      • All Funds
      • Fund Explorer
      • Fund Distribution
      • Fund Documents

      Capabilities

      • Equities
      • Fixed Income
      • Multi-asset
      • ETF Investing
      • Active research

      Featured Funds

      • Equity High Income Strategies
      • China Equity High Income Fund
      • Asia Equity High Income Fund
      • Global Equity High Income Fund
      • Fixed Income Solutions
    • Insights

        Market Insights

        • Market Insights Overview
        • Guide to the Markets
        • Weekly Market Recap

          Start each week with J.P. Morgan Asset Management’s one-page snapshot of top headlines, market performance, chart of the week and more.

        • On the Minds of Investors
        • Podcasts
        • Mid-Year Outlook 2026
        • Multimedia
        • Guide to Alternatives

        Portfolio Insights

        • Portfolio Insights Overview
        • Global Asset Allocation Views
        • Global Fixed Income Views
        • Global Equity Views
        • Alternative Insights

        ETF Insights

        • ETF Insights overview
        • Guide to ETFs
      • Investment Ideas
          • What's new
          • Retirement and long-term investing
          • Sustainable investing
          • ETF knowledge
        • Personal Investing

            Knowing the Basics

            • All Personal Investing
            • Mutual Funds 101
            • Taking the First Step in Investing
            • Ways to Diversify Your Portfolio

            J.P. Morgan DIRECT Investment Platform

            • Open an Account Online
            • Start Investing
            • Invest regularly: Monthly Fund Investment
            • J.P. MORGAN DIRECT: Digital Share Class
          • Retirement Services
              • All Retirement Services
              • ORSO Services
              • MPF Services
              • Retirement Fund Centre
            • Self Service Center

                Fund Listing

                • Fund Explorer
                • Announcement
                • Fund Documents
                • Distribution History
                • Risk Rating

                Self Services

                • All Self Service Center
                • Morgan Direct Demo
                • JPM Bot
                • Forms & Literature
                • FAQ
                • Open an Account
                • Privileges and News
              • About Us

                  About Us

                  Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

                  • Overview
                  • Awards
                  • Diversity, Opportunity and Inclusion
                  • Contact Us
                  • Announcements
                  • Our Leadership Team

                  Tools & Resources

                  • Insights App
                  • Library
                  • Investment return calculator
                • Language
                  • English
                  • 中文/ Chinese
                • Account Login
                • Open an Account
                You are about to leave the site Close
                J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
                CONTINUE Go Back
                On the Minds of Investors

                Implications of U.S.-Iran agreement to reopen the Strait of Hormuz

                TH
                Tai Hui

                Chief Market Strategist, Asia Pacific

                Published: 15/06/2026
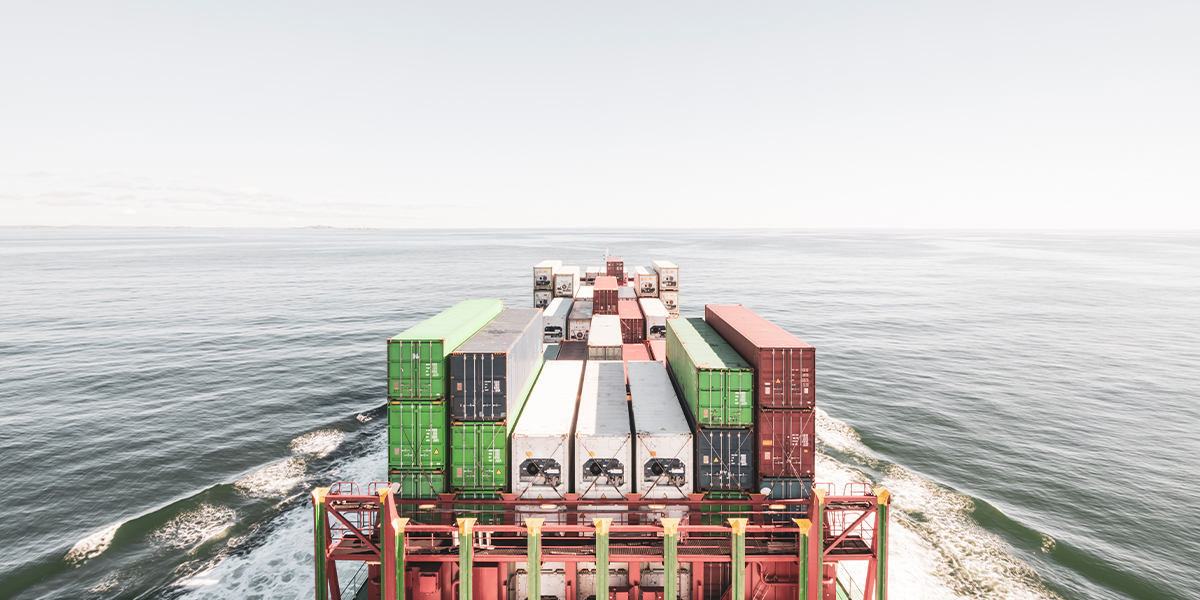
                Reopening the Strait is clearly a positive for the global economy, as disruptions in energy and petrochemical supplies can introduce stagflation risks.

                In Brief

                • An agreement to reopen the Strait of Hormuz reopening would reduce a major source of global economic risk.
                • Supply normalization may take weeks, if not months, with insurance costs, damaged infrastructure, and reserve rebuilding keeping energy prices elevated.
                • Investors may see a risk-on rotation into lagging sectors, Asian markets, and longer-duration bonds, while energy security and defense spending remain longer-term themes.

                What we know so far

                U.S. President Trump announced that a deal has been reached to extend the ceasefire and reopen the Strait of Hormuz. This has been confirmed by Iran’s deputy foreign minister, as well as by Pakistan and Qatar, the mediators in these negotiations. An official signing ceremony is expected to take place this Friday in Switzerland. While U.S. President Trump has announced similar deals in the past, confirmation from Iran and the mediators increases the likelihood that this agreement will proceed.

                Details of the agreement remain limited at this point, and the situation can still change even after the memorandum of understanding (MOU) is signed. This is unlikely to be the end of negotiations, as durable consensus on Iran’s nuclear program—and easing tensions among the Gulf countries—would be difficult to achieve sustainably. Moreover, there have been sporadic military actions from both sides since the initial ceasefire was reached in early April. The conflict between Israel and Hezbollah in Lebanon also remains a wildcard for this peace process. Nonetheless, the agreement to reopen the Strait of Hormuz would be the most relevant part for investors. 

                What does this mean for the global economy?

                Reopening the Strait is clearly a positive for the global economy, as disruptions in energy and petrochemical supplies can introduce stagflation risks. While markets may be quick to price in recovery, a return to normalization would take time.

                The first hurdle will be convincing insurers and shipping companies that it is safe for vessels to transit the Strait of Hormuz. Even with the reopening, insurance premia for ships passing through the Strait could remain elevated, increasing the cost of oil, gas, and other products from the region.

                It will also take time for energy production, refining, and logistics capacity to return to pre-conflict levels. A reasonable estimate for normalization is weeks, if not two to three months. This does not account for production facilities that may have been damaged by Iranian attacks; some could take two to three years to repair and bring back online.

                Economies and governments may also seek to replenish inventories and strategic reserves in case the situation in the Middle East deteriorates again. Overall, this suggests energy prices are unlikely to fall back to pre-conflict levels in the near term.

                For central banks, reopening the Strait should provide some relief, as the initial inflation shock from energy prices may not yet have fully filtered through to inflation expectations. This would allow the U.S. Federal Reserve to hold rates this week and continue monitoring. The European Central Bank (ECB) raised policy rates last week, as it was already on a tightening path ahead of the conflict due to building inflationary pressures. If energy prices remain calm on a sustained basis, this should give the ECB more flexibility to adjust policy later in the year.

                What does this mean for investors?

                Unsurprisingly, the immediate market reaction is a risk-on rally. This could prompt further rotation, benefiting recent laggards. Non-tech sectors may play catch-up if a major source of economic uncertainty is receding. Consumer-related companies, energy-intensive industries, and transportation could benefit.

                In Asia, ASEAN and India have seen performance hindered by energy shortages and inflation pressures. An eventual resumption of energy imports should help support these markets. This also opens a window for investors to diversify away from technology, which has already performed well year-to-date. This type of rotation calls for active management in equity allocation.

                The prospect of peaking policy rates could also support adding duration in selected government bond markets, as well as a modest tightening of credit spreads. Improved risk appetite could also renew pressure on the U.S. dollar.

                Beyond the immediate market reaction to a deal and the reopening of the Strait, investors may have questions about the longer-term implications of this conflict.

                First, energy security is once again at the top of the agenda. The Russia–Ukraine conflict forced European governments to reassess energy dependence; the Middle East conflict has had an even more significant impact on many Asian economies. Where oil and gas are imported from should become a policy discussion for all governments. This also raises questions about energy sources and the role of non-fossil fuels, including renewables and nuclear power.

                Second, the U.S.–Iran conflict suggests that the scale of defense spending is not the only factor influencing outcomes, but also how that money is spent. High-volume, low-cost weapons—such as drones—gave Iran an advantage in controlling the Strait of Hormuz and threatening other Gulf states to gain leverage. The economics of defense is likely to evolve in the coming years, potentially driving rotation within the defense industry.


                e25d4ced-656a-11f1-ae84-d7bd183c4562

                About the Author

                Latest from the Author

                Monthly Views and Perspectives: Higher rates and AI scrutiny calls for portfolio diversification
                October 01, 2026 Tai Hui
                The problems with doing too much, or too little
                September 02, 2026
                Mid-term elections: How does a change in Congress change U.S. policies?
                June 11, 2026 Tai Hui
                How could the Middle East conflict evolve?
                June 11, 2026 Tai Hui
                What if oil hits USD 150?
                May 13, 2026 Tai Hui
                • Commodities
                • Economy
                • Energy
                • Equities
                • Fixed Income
                • Geopolitics
                • Interest Rates
                • Markets
                • Monetary Policy
                • Oil
                J.P. Morgan Asset Management

                • Terms of Use
                • Privacy Statement
                • Cookies Policy
                • Investment Stewardship
                • Self Service Center

                J.P. Morgan

                • J.P. Morgan
                • JPMorgan Chase
                • Chase

                Contact us:
                (For HK MORGAN DIRECT existing and prospective clients only)
                Investor Line: (852) 2265 1188
                Investor Email: hkmorgandirect.cs@jpmorgan.com
                Operating Hours: Mon – Fri 9:00 a.m. – 6:00 p.m.


                The information contained herein is intended only for use by Hong Kong residents. By using this information, you are representing and warranting that you are either residing in Hong Kong or the applicable laws and regulations of your jurisdiction allow you to access the information, and you confirm that you accept the Terms of Use as set out in https://am.jpmorgan.com/hk/. Investment involves risk. Past performance is not indicative of future performance. In particular, funds which are invested in emerging markets and smaller companies may involve a higher degree of risk and are usually more sensitive to price movements. Investors should carefully read and consider the fund offering document(s), which contain details on investment objectives, risk factors, charges and expenses of the fund, before making any investment decisions. Investors should read carefully the fund notes before making any investment decisions. Information in this website does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service, nor a distribution of information for any such purpose. Opinions and statements of financial market trends set out are for information purposes only, based on certain assumptions and current market conditions and are subject to change without prior notice. Investors should conduct their own verification. The views and strategies described may not be suitable for all investors. This website and the advertisements contained herein are issued by JPMorgan Funds (Asia) Limited. This website has not been reviewed by the Securities and Futures Commission of Hong Kong ("SFC"), with the exception of material relating to the JPMorgan Provident Plan that the SFC has pre-approved (however such pre-approval does not imply official recommendation by the SFC).

                Apple, the Apple logo, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. App Store is a service mark of Apple Inc.

                Copyright 2025 JPMorgan Funds (Asia) Limited. All rights reserved.