logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us
              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. Emerging markets and the negative yield conundrum for fixed income investors

            • LinkedIn Twitter Facebook WhatsApp

            Emerging markets and the negative yield conundrum for fixed income investors

            17/10/2019

            Frederick Bourgoin

            Zsolt Papp

            The flipside of the 30-year bond market rally is that developed market bond yields have been decreasing to record low levels and more recently even into negative territory. This poses a major problem for fixed income investors, which in some cases is materially exacerbated by the high cost of hedging. In response, developed market investors have been increasingly diversifying into non-core assets such as emerging markets (EM) or high yield (HY). However, these asset classes are gradually also being affected by the “negative yield disease”. In view of this, we argue that one option for investors is to take active FX risk.

            Significant problem for EUR and CHF-based investors

            Chart 1 shows the share of negative yielding bonds in developed and emerging government bond markets, respectively. Importantly, we not only looked at bonds in their respective reference currencies, but also at yields hedged to Swiss Franc (CHF) and Euro (EUR). The picture is quite sobering, in particular for CHF-based investors. 94% of the developed government bond market universe is negative yielding when hedged to CHF. The situation is only marginally less dramatic for EUR-based investors. This is also not an entirely new phenomenon: in fact, it’s been a dominant market feature since 2015 for CHF and 2016 for EUR based investors.
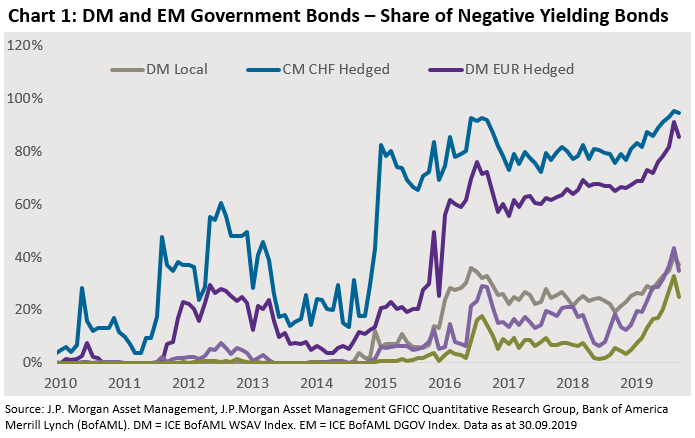
            Chart 1 also shows that EM is not immune. While there are no negative yielding bonds in the USD-denominated universe of EM government bonds, the share is already 25% hedged in EUR and 33% in CHF, respectively.

            Dramatic impact on yield levels

            The impact on yield levels is dramatic for some investors. DM government bonds hedged in CHF offer a yield of -0.65%, which begs the question if “fixed loss” might not be a more appropriate term instead of “fixed income” for Swiss Franc-based investors. The outlook for EUR and JPY-based investors is only marginally less dramatic with hedged yields of -0.31% and -0.16%, respectively.
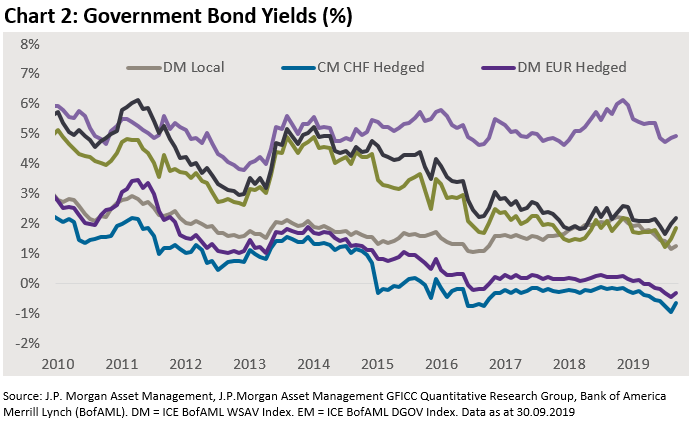
            In contrast, EM (and HY) hedged yields remain comfortably in positive territory. It may not sound like much, but a CHF-hedged yield of 1.9% for EM government bonds looks very appealing when compared to -0.61%. Moreover so, as adding EM debt to a global bond portfolio does not necessarily mean adding more risk. Giles Bedford showed earlier in September (No Longer “Why” but “How”: The case for emerging markets debt matures, September 26, 2019) how the role of EM in fixed income portfolios is changing as it offers a higher Sharpe measure than the Bloomberg Global Aggregate.

            In view of this, we would expect investors to increase diversification into non-core bond markets, especially as institutional allocation is still very low. According to Mercer, only 18% of European pension schemes have an average allocation of 5% to EM, which implies that there is ample room to increase exposure. Allocation to HY is equally very low. [1]

            Unhedged vs hedged yield

            In addition to diversification, we believe that investors will also have to consider taking active currency risk in order to avoid the negative yield trap. First, unhedged yield levels are much more attractive, as clearly shown in Chart 2. Second, unhedged returns for EM government bonds have been significantly higher as hedging can wipe out as much as 60% of the return in some cases. Table 2 shows the performance of Swiss and Euro government bonds vs EM government bonds since entering the zero / negative yield spiral in early 2015. Third, this problem is likely to last and negative yields could even get more negative, as Jason Davis showed in his blog last week (Negative Rates – How low can you go? October 10, 2019). 
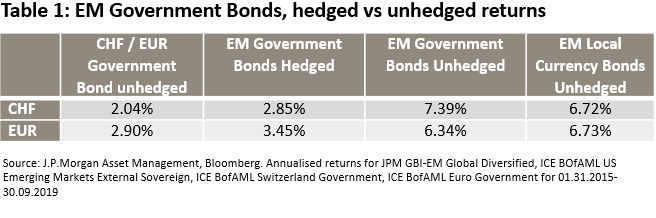
             In sum, there are several valid reasons why investors should consider taking active currency risk. One approach would be to invest in a traditional USD-denominated bond strategy, as illustrated by the ICE BofAML DGOV index, and hedge in the reference currency. Another approach would be to invest in EM local currency bonds, such as represented by the JPM GBI-EM Global Diversified index. Table 1 shows that this would have generated similar returns to USD-denominated bonds for EUR and CHF-based investors.

            The latter leads to the question of whether it is a good moment to take active currency risk? We know from (sometimes painful) experience that in crises EM currencies can go lower and therefore valuation analysis has to be taken with a grain of salt. Nevertheless, Chart 3 shows that EM FX is currently trading at long-time lows and not far off the historical low. This would therefore lend support to the view that current levels could offer an attractive point of entry.
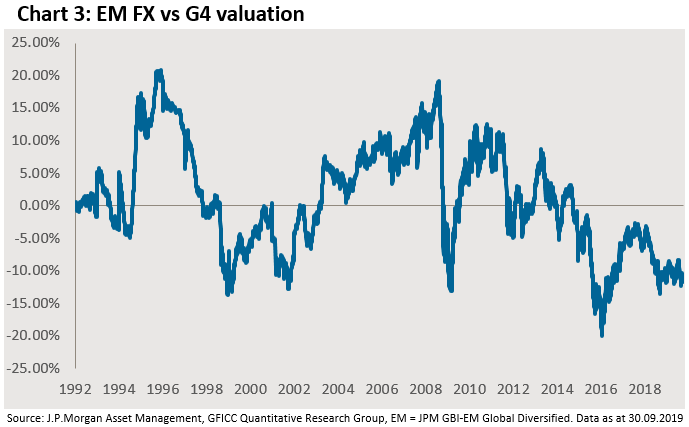
            So how do investors react to the idea of taking active currency risk? What we can observe is that strategies actively investing in local currency Rates and FX have seen significant inflows. Unconstrained bond funds attracted USD 57bn so far this year and EM local currency bond strategies (retail and institutional) USD 6.4bn. This is still below the amount going into EM hard currency strategies (USD 48.7bn) but it nevertheless illustrates that investors are prepared to take active currency exposure.

            In sum, the growing share of negative yielding bonds requires investors to diversify away from core fixed income. EM bonds are offering a solution to this problem. However, as the high cost of hedging is eating into the income achieved in EM bonds, investors will also have to consider taking active currency risk in their portfolios. Flow of funds indicates that there is already some investor appetite, and as negative yields are likely here to stay (and potentially grow), we would expect demand for active currency solutions to increase.

            [1] Mercer, European Asset Allocation Survey 2019

            • Emerging Markets
            • Eurozone
            • Rates
            • Currency

            RELATED ARTICLES

            Add extra guacamole for a dollar!

            Emerging Markets Local Currency debt emerged as one of our best ideas at our most recent investment quarterly meeting. This isn't just about the US Dollar; we like what we see in local EM.

            Read more

            Emerging Markets: Don’t Fight the Central Banks

            The opportunity cost of not investing in EM debt remains very high. Most importantly the same applies for the rest of fixed income: don’t fight the central banks.

            Read more

            A new era for alpha generation in local emerging markets?

            The global savings glut has been driving asset price valuations for the last decade or so. Emerging Markets and investors need to prepare for a potential new world.

            Read more
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.