logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us

              About us

              Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back

            <p>2027 Long-Term Capital Market Assumptions</p>

            The 31st annual edition explores how economic nationalism, faster tech adoption and shifts in capital flows are reshaping returns over the next 10 to 15 years – supporting faster growth but also more inflation volatility, and calling for thoughtful diversification.

            1. Home
            2. Insights
            3. Portfolio Insights overview

            Productivity Returns: An investment surge lifts growth … and volatility

            A USD 15 trillion global capex supernova fuels higher growth and strong asset returns over the next 10 to 15 years. Productivity gains mitigate rising inflation risks and an aging workforce. Despite the tail risks, a resilient economy drives resilient markets.

            Three forces shape the future and drive returns

            Economic nationalism boosts domestic investment but risks a crosscurrent of inflation volatility. Technology adoption is the fair wind filling the global economy’s sails. Rising domestic investment drives capital rewiring, resulting in shifts in public and private capital flows.

            The best developed world growth outlook in 15 years

            A global investment surge, centered on AI and extending to 2040, boosts total factor productivity by 50%, to 120bps, pushing our U.S. real GDP growth forecast up to 2.1% and developed world nominal growth up to 4.2%. The mix of GDP-to-inflation is the most favorable since the pandemic.

            U.S. equity upgrades, a global bond renewal and a first look at bitcoin

            Profit margins of over 15% push our U.S. large cap equity forecast up 80bps, to 7.5%, leading to our developed market equity forecasts overtaking our emerging market equity forecasts. Higher real yields drive global aggregate bond forecasts from a low of 2.1% in 2021 to 5.3% today – the highest in two decades. And for the first time, we put a range on bitcoin returns, though we do not yet include bitcoin in our main covariance matrices.

            Alternatives for return enhancement, diversification and inflation resilience

            We upgrade diversified hedge funds by 140bps on sustained alpha trends and higher rates – with alpha to play for, manager selection is vital. Real asset returns are resilient in the face of persistent inflation volatility, with global transportation returning 8.1%, global core real estate 7.9% and global infrastructure 7.1%.

            Greater opportunities to diversify, greater rewards for doing so

            A balanced global stock-bond portfolio rises 60bps, to 7.0%, but higher stock-bond correlation demands further diversification. Alternatives can boost risk-adjusted returns: Allocating 30% to diversified alternatives can push returns up to 7.5% and boost Sharpe ratios by 21% compared with a simple balanced portfolio. Diversifying relative to themes as well as across assets can further strengthen portfolio resilience.

            Source: J.P. Morgan Asset Management; data as of September 2026

            Topics

            Matrices

            Our expectations for returns, volatilities and correlations. Use our interactive version to download the excel in your chosen currency.


            The assumptions are not designed to inform short term tactical allocation decisions. Our assumptions process is carefully calibrated and constructed to aid investors with strategic asset allocation or policy-level decisions over a 10- to 15-year investment horizon.

            Download Excel and PDF matrices by currency

            • Excel
            • PDF

            Assumptions

            Examine our return projections by major asset class and the thinking behind the numbers.

            Long-Term Capital Market Assumptions: Methodology Handbook

            A companion volume to dive deeper into our LTCMAs’ building blocks

            • Macroeconomic
            • Public markets
            • Private markets
            • Portfolio Implications

            Macroeconomic Assumptions

            AI leaders pull ahead, and inflation paths diverge

            Key Insights

            Economic nationalism and technology adoption shape long-term growth and new patterns of global capital flows, lifting our developed market (DM) growth assumptions.


            Stronger DM productivity, from AI adoption and capital deepening plus higher investment in tech, defense and energy, outweigh aging demographics and immigration and trade restrictions.


            Emerging market (EM) growth holds steady.


            Inflation, unchanged in aggregate, encompasses near-term pressures from trade and subsiding AI investment.


            U.S. inflation declines modestly, despite strong capital spending, large deficits and economic nationalism – forces that, by contrast, end Europe and Japan’s low-inflation era. Central banks, tariffs and trade produce mixed EM inflation projections.

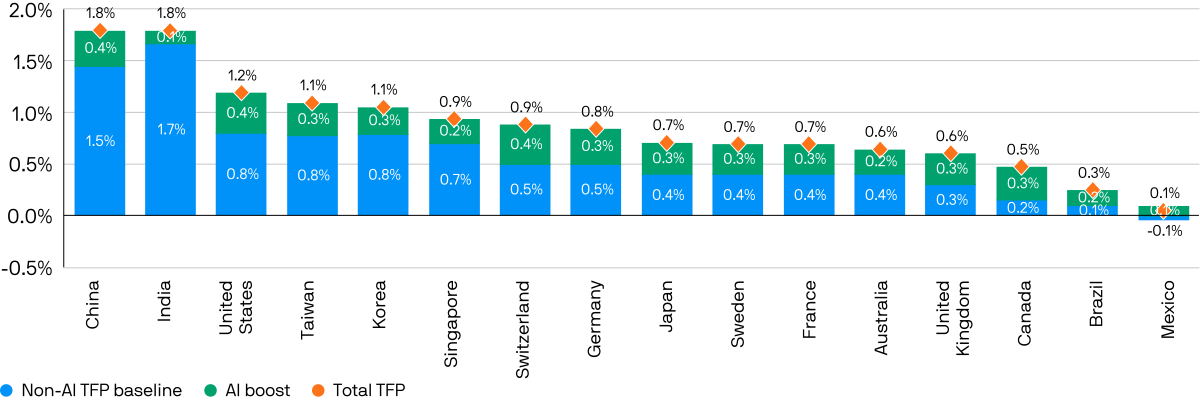
            The scale of AI’s boost to total factor productivity varies widely

            AI contribution to TFP
            Macroeconomic

            Source: J.P. Morgan Asset Management; data as of September 30, 2026. The non-AI TFP baseline is each economy’s assumed trend productivity growth before any AI contribution.

            Public markets assumptions

            Strong but uneven returns in a changing world

            Key Insights

            Higher cash rate assumptions and rebuilt term premia lift government bond returns to near two-decade highs and starting yields look attractive. Duration will be a less reliable hedge with inflation and fiscal risks.


            The USD depreciates more slowly, mainly vs. Asian currencies, and retains its reserve status.


            In credit, spreads are tight, yields look attractive but dispersion is rising. Leveraged loans show more distress; our high yield outlook is constructive as index quality improves.


            Global equities deliver solid, profit-driven returns; tech adoption makes us optimistic, especially in the U.S. due to AI-driven productivity gains.


            We debut bitcoin coverage, but unstable correlations to other assets impair a strategic allocation.

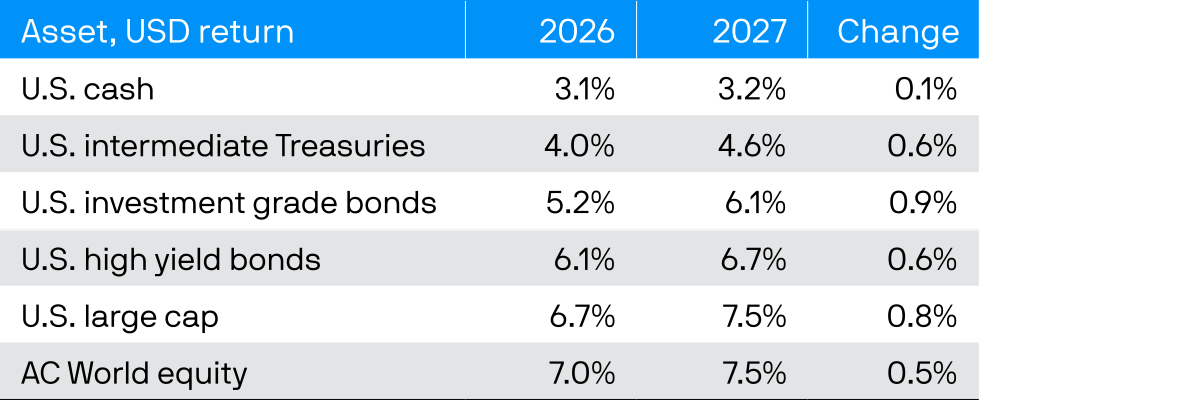
            A balanced portfolio earns a respectable return over the next 10 to 15 years

            Public market return assumption changes vs. prior edition of LTCMA
            Public markets

            Source: J.P. Morgan Asset Management; data as of September 30, 2026.

            Private markets and alternative asset assumptions

            New forces lift private markets; greater dispersion offers alpha

            Key Insights

            Economic nationalism, technology adoption and capital rewiring drive economic growth and inflation volatility. We lift our return assumptions across private markets but expect widening performance dispersion.


            Real assets gain as economic nationalism prompts concern over energy security and strategic resilience. Technology adoption supports opportunities in infrastructure, transportation/logistics and real estate.


            In financial alternatives, outcome dispersion widens. Private equity’s return potential depends on value creation and operational efficiencies, such as deploying artificial intelligence (AI).


            As capital flows deepen, portfolio construction benefits from pairing return-enhancing private market exposures with time-tested diversifiers, including real assets and hedge funds.

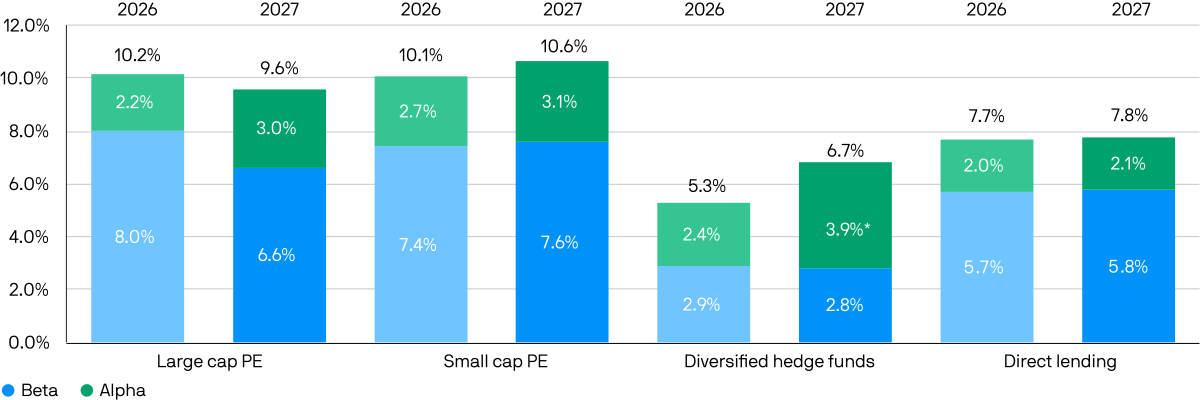
            Rising alpha estimates across financial alternatives will be matched by an increase in performance dispersion

            Financial alternatives’ expected returns and drivers
            Private markets

            Source: J.P. Morgan Asset Management; data as of September 30, 2026. Alpha is defined as the intercept (or, in the case of private equity, the sum of the intercepts), except for direct lending, where alpha is defined as the excess return over the expected leveraged loan spread.
            * The alpha boost seen in hedge fund returns comes in part from methodology enhancements this year.

            Portfolio Implications Assumptions

            How intentional thematic exposure can build portfolio resilience

            Key Insights

            We take a glass half-full view of the impact of our three themes on returns, with a balanced portfolio returning 7% and a balanced with alternatives returning 7.5%. But the volatility of inflation, rates and equities will likely move higher. Stock-bond correlation will be more positive and unstable. In other words, investors need fortified portfolio resilience to different types of shocks.


            That resilience should include a holistic view of the thematic exposure in portfolios, evaluating both public and private markets. This year we present a framework that allows an investor to increase or decrease exposure to a particular theme. Investors need to be intentional about thematic exposure, as portfolios are becoming increasingly concentrated, especially to the tech adoption theme.

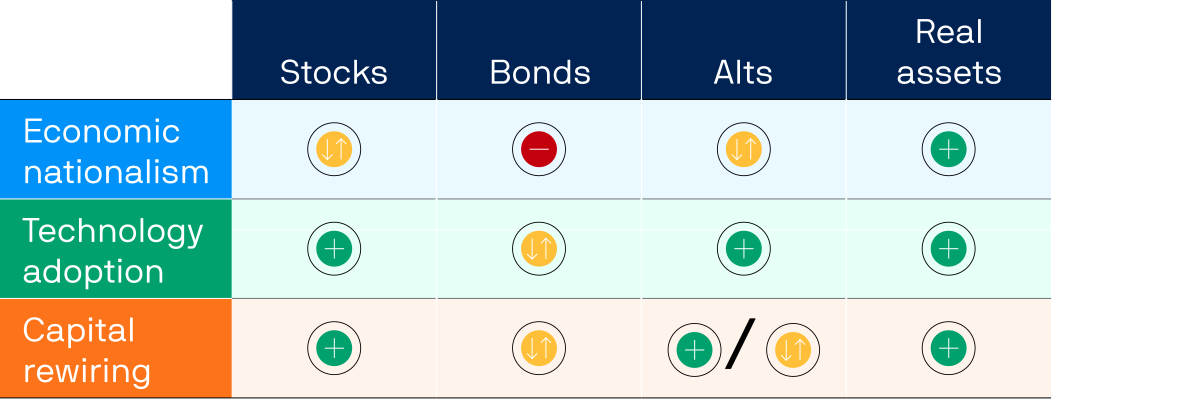
            Relative winners and losers vary across themes

            Asset market impacts of themes
            Portfolio Implications

            Source: J.P. Morgan Asset Management; data as of September 30, 2026.

            Download this year's Long Term Capital Market Assumptions report
            2027 Long-Term Capital Market Assumptions

            Frequently asked questions

            J.P. Morgan Asset Management’s annual LTCMAs provide return, risk and correlation forecasts for more than 200 major asset classes in 20-plus base currencies, over a 10- to 15-year horizon. Our LTCMAs represent the work of more than 90 of our researchers, portfolio managers and economists worldwide, using a process refined over 31 years. A publication expands on the data, analyzing trends and themes.

            Designed to help pave the way to stronger portfolios, these forecasts drive J.P. Morgan Asset Management’s strategic asset allocations and power the tools we use to advise clients. They help asset allocators, financial advisors and others build portfolios, evaluate trade-offs and stress-test performance against objectives, in pursuit of their long-term goals.

            We center the 2027 edition on three forces with durable implications: Economic nationalism (governments’ more domestically oriented posture); faster diffusion of technological innovation (tech adoption) and the reconfiguration of how and where public and private funds are deployed (capital rewiring). These reshape returns’ level and dispersion across regions, sectors and asset classes. With a global capex boom, they support higher growth while creating more inflation volatility.

            Resilient economies support resilient markets, but with wider outcomes – raising the rewards for thoughtful diversification.

            We forecast a rise in long-term returns from a balanced-plus portfolio – including alternative assets. We expect faster economic growth to boost profits and yields, lifting a balanced portfolio’s long-run returns from last year’s forecast. In equities, U.S. profit margins are more resilient than emerging markets’. In fixed income, higher real yields improve the case for government bonds, while an “up in quality” mindset and tighter spread assumptions improve our corporate credit forecast.

            Higher inflation volatility, ongoing risk of currency debasement and growing opportunities to capture active alpha reinforce alternatives as essential diversifiers and potential return drivers.

            We believe AI will drive a meaningful, durable uplift to productivity over 10 to 15 years. Improved productivity is the main force returning U.S. GDP growth to a faster pace over a decade. AI diffusion and the resulting productivity boost will likely be gradual, most significant in the 2030s and beyond. This is vital to our 2027 forecast. Steady uptake should limit rapid, economy-wide job displacement while giving supply chains time to adapt.

            For more than three decades, we’ve gathered 90-plus industry-leading portfolio managers, economists and research analysts on three continents, led by John Bilton, Global Head of Strategic Research, Multi-Asset Solutions. Authors and leadership team members include Dr. David Kelly, Chief Global Strategist; Karen Ward, Chief Market Strategist in EMEA; Tai Hui, Chief Market Strategist in Asia; Gabriela Santos, Chief Market Strategist for the Americas, Pulkit Sharma, Head of Alternatives Investment Strategy & Solutions and David Lebovitz, Head of Alternatives Research and Strategy.

            Be the first to get additional resources and insights from our team

            Share your details and we’ll keep you updated as new insights and resources are released.

            This field is required.

            This field is required.

            This field is required.

            This field is required.

            This field is required.

            This field is required.

            By providing the above information you are agreeing to receive J.P. Morgan Asset Management communications regarding this series.

            58fa1f96-c36b-11f1-a9f3-d1e9c787777c

            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.