logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us
              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. Treasury’s 20-20 vision

            • LinkedIn Twitter Facebook Line WhatsApp

            Treasury’s 20-20 vision

            14/05/2020

            Owen Hawkins

            On May 20, 2020 the Treasury will issue $20bn of new 20-year bonds. Formally announced last week, this re-introduction of 20-year issuance was widely anticipated and will be followed by $17bn of monthly reopenings. The new 20-year will feature auctions in the refunding months (February, May, August, and November) and maturities aligned with existing 10 year and 30 year issuance. In justifying the new tenor, the Treasury cited primarily the need to manage their increased borrowing and the growing demand for long bonds by liability driven investors (“LDI”).

            While the market had been expecting this announcement since January, the size of issuance nevertheless surprised given expectations for initial 20-year issuance were around $13bn. In order to make room and avoid meaningfully extending their maturity profile, the Treasury was expected to reduce 7-, 10- and 30-year issuance and/or issue more bills to balance the duration impact. However, as we now know, the COVID-19 crisis created unprecedented fiscal spending requirements and rendered both aforementioned concerns moot. Along with the $20bn 20-year, the Treasury upsized issuance across the curve and intends to maintain higher cash balances through bill issuance given the uncertainty of future spending needs.

            On the demand side, the LDI flow, generally consisting of life insurers and corporate defined benefit pensions, will be significant buyers of 20-year bonds. This investor base has long dated liabilities that often require hedging with similarly long duration assets. Their liability profile also tends to feature significant exposure in the 15 to 25-year part of the curve. For LDI investors looking to match their curve exposure, there has historically been a limited offering between 10s and 30s, creating natural demand for 20-year issuance.  We see this in the other markets with a large LDI investor base, such as Japan and the UK, where 20-year issuance is well absorbed.

            Despite the relative illiquidity of the 20-year sector at present, it has historically traded rich to fair value. This is due in part to the scarcity of available bonds (see chart). From 2001 to 2006, the Treasury ceased issuance of 30-year bonds which has created a gap in the current curve. On top of this, the Federal Reserve has purchased nearly their maximum 70% of outstanding issuance in the 2036 to 2041 maturity range via open market operations (both in 2020 as well as earlier quantitative easing). 

            Long Treasuries Outstanding by Maturity
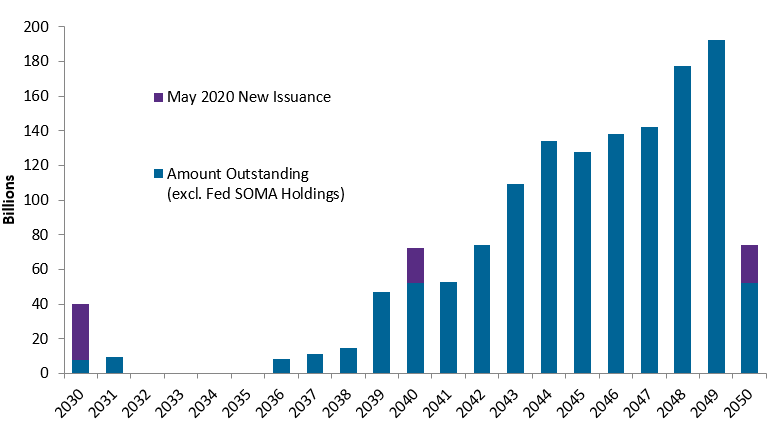
            Source: Bloomberg, US Treasury as of 5/12/2020

            As the 20-year issuance builds over time, we’d expect the curve to cheapen given a better matching of supply and demand and more trading activity. We’ve witnessed much of this cheapening already following the October 2019 announcement recommending 20-year issuance, as well as after further detail was released in January and May 2020. The impact of Fed buying remains a significant unknown however, as they’ve essentially ceased purchases in the 20-year sector which likely contributes to the cheapening. The Fed will certainly be buyers of the new issuance though.

            Beyond the first order implications for rates, the introduction of 20-year issuance will also impact other debt markets. For corporates, long bonds price off either the 10-year or 30-year Treasury, with the roll occurring around 15 years to maturity. With new on-the-run 20-year bonds, these will presumably be used for pricing corporates once a sufficient issue size is developed. This may help richen a part of the credit curve that has historically traded cheap due to the lack of a natural hedge. After the initial 20-year announcement in January, however, much of this trade may have already played out.

            The other side of the coin is corporate supply. 20-year corporate issuance has picked up in recent years as companies termed out debt given the historically low rate environment and looked to diversify their maturity profile in the process (rather than having just a large block of 30-year debt outstanding). Now we may see an uptick in 20-year corporate issuance, though existing debt profile preferences and the cost of long debt are much more likely to drive issuance patterns.

            So while there may be a handful of relative value opportunities yet to be priced out, meaningful changes to the shape of rates and credit curves via factors like LDI portfolio construction, futures contract deliverables and corporate bond hedges will likely play out over a longer horizon. Fortunately, the Treasury has signaled that 20-year issuance will be a consistent and sizable component of their borrowing in the years to come. 

            • Rates
            • COVID-19
            • US Treasury

            RELATED ARTICLES

            But what about the deficit?

            On the heels of Moody’s rating downgrade of US Treasuries and continuing budget negotiations in the US Congress, higher uncertainty has resulted in a re-pricing of term premium in the bond market.

            Read more

            The forest and the trees

            When constantly watching financial markets and following the 24-7 news flow, it can be easy to get caught up in the trees and miss the forest.

            Read more

            FOMC statement & potential impact on fixed income

            Looking beyond the disappointing press conference, we believe the FOMC is employing a proactive risk management approach as opposed to a reactionary policy.

            Read more
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.