logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us

              About us

              We harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. Singapore Dollar – no longer defying gravity

            • LinkedIn Twitter Facebook Line WhatsApp

            Singapore Dollar – no longer defying gravity

            20/02/2020

            Aidan Shevlin

            Weak growth, elevated currency

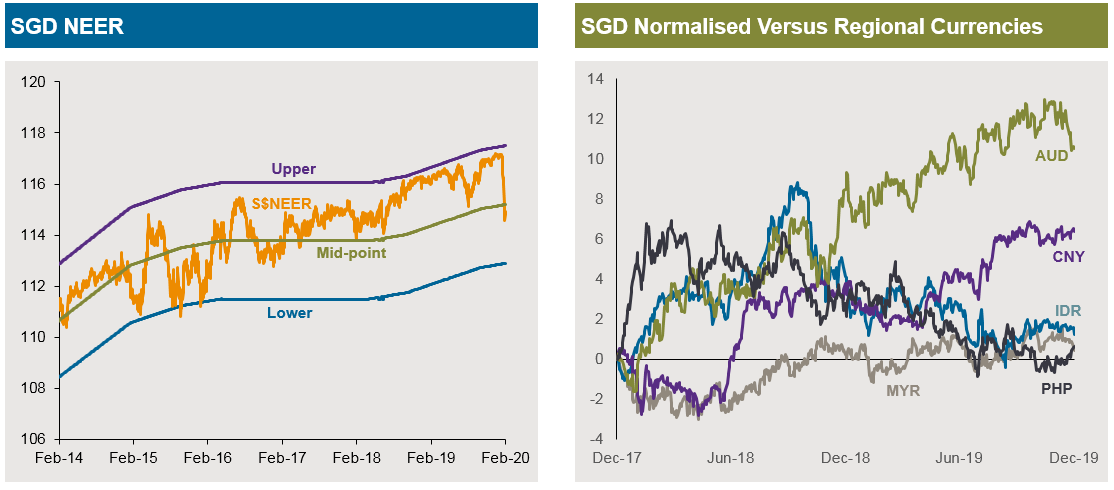
            For the majority of 2019, the Singapore nominal effective exchange rate (S$NEER) defied economic gravity, tightly adhering to the top end of its trading range (Fig 1a), while the SGD outperformed many regional currencies (Fig 1b). 

            However, the potentially large negative impact of the of the Covid-19 virus has prompted a reappraisal of weaker economic data and muted inflation – triggering a notable dovish shift by the Monetary Authority of Singapore (MAS) with significant implications for the SGD and short term interest rates.

            Fig 1: The MAS controls the S$NEER; SGD has outperformed regional peers in 2018 & 2019
            Source: Citibank, Bloomberg & J.P. Morgan Asset Management.  Data as at 12th February 2020

            Trade tensions encourage a MAS pivot

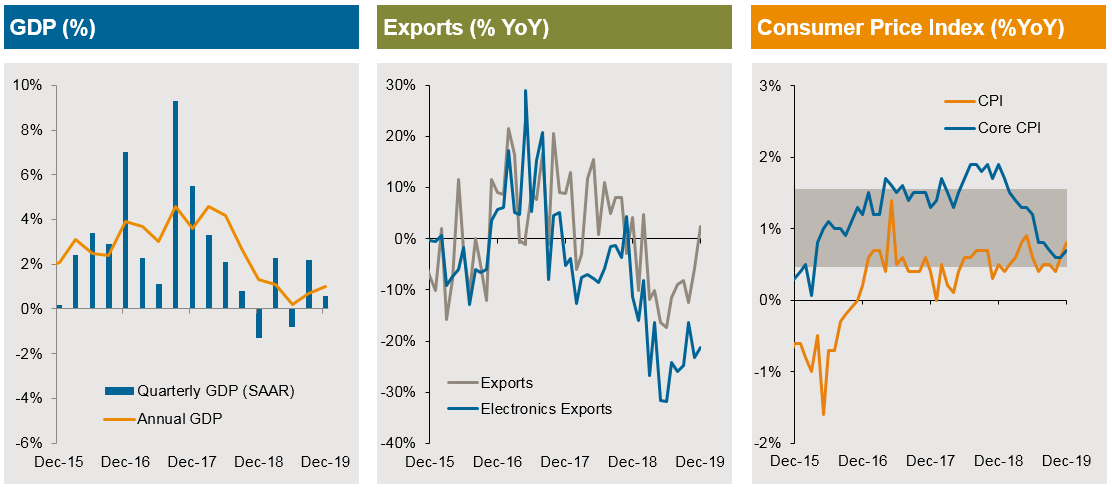
            The Singapore economy faced multiple headwinds in 2019 from weaker domestic growth, anemic price pressures and a heightened exposure to global trade tensions (Fig 2).  At its April 2019 monetary policy meeting the MAS ended its hawkish hiking cycle, leaving rates unchanged and downgrading its GDP and core inflation targets.  Subsequently, weaker than expected growth and further downward revisions to its key targets nudged the central bank to cut the slope of its S$NEER at its October policy meeting, the first easing in over 3.5 years.

            The MAS’s modest monetary policy adjustments stood in stark contrast with more aggressive rate cuts by global and regional peers – leaving the S$NEER at the top of its trading range and SGD stronger relative to other Asia-Pacific currencies

            Fig 2: Singapore monetary policy depends on trade and inflation
            Source: Bloomberg & J.P. Morgan Asset Management.  Data as at 15th February 2020

            SAAR = seasonally adjusted annualized rate

            Despite the policy pivot, Singapore’s economic growth hit a decade low of 1.0%y/y in 2019 as escalating global trade tensions weighted on the Lion city’s open, export dependent economy.  Fortunately, lower global interest rates and record tourist arrivals and spending supported a moderate stabilization while the phase 1 US/China trade truce in early January raised the potential of an economic recovery in 2020.

            Evolving uncertainty

            The unexpected Covid-19 outbreak, with its negative implications for international trade, domestic productivity and tourism has triggered significant uncertainty and concern - especially after Singapore raised its disease outbreak response condition level.

            The imposition of travel restrictions on Chinese visitors – the largest source of spending in 2019 - has already dramatically impacted tourism, with significant ramifications for the aviation, hospitality and consumption sectors.  In addition, the delayed return of many Chinese workers will impact the construction sector, while manufacturing and export sectors will be negatively affected by China’s delayed re-opening following Chinese New Year holidays. Acknowledging the downside risks, the government downgraded its 2020 growth forecast by 1% to a range of -0.5% to 1.5%.[1]

            Rapid fiscal and monetary support

            Responding to media queries, on 4th February 2020, the MAS commented[2] that “there is sufficient room within the policy band to accommodate an easing of the S$NEER in line with the weakening of economic conditions as a result of the 2019-nCov”.  Such inter-meeting statements are rare and highlight the central banks concern.  The de-facto easing triggered an instant market response, with the S$NEER declining sharply below the mid-point of its trading range for the first time since 2017 while the SGD weakened considerably versus the USD.

            The MAS confirmed its next policy meeting would occur on schedule in April – allaying concerns of an inter-meeting cut.  Given the S$NEER band still has a mild appreciation bias, most economists expect the central bank to either flatten the S$NEER slope or lower the S$NEER trading band.

            Implications for cash investors

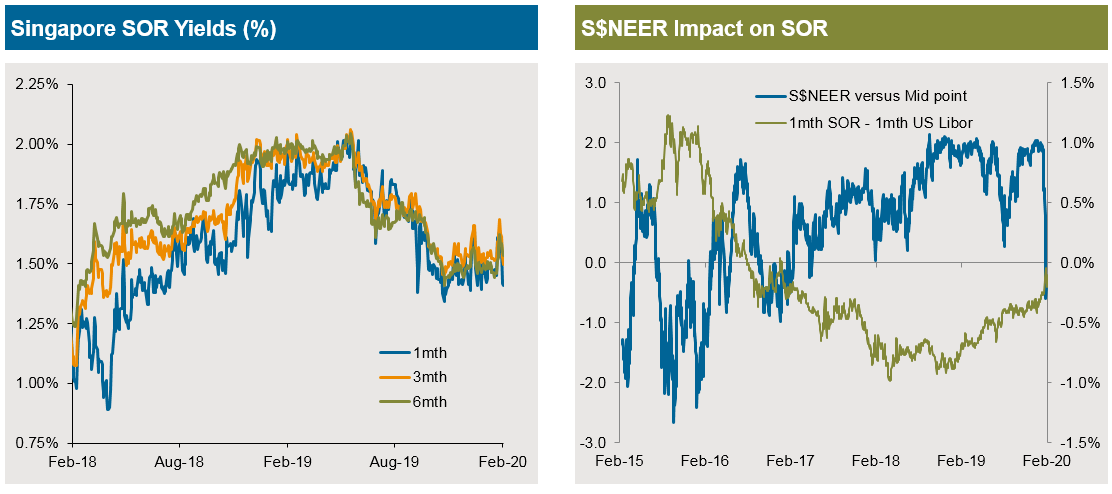
            In 2019, Singapore Swap Offer rate (SOR) yields declined (Fig 3a) as the US Federal Reserve (Fed) switched to a dovish policy stance with three rate cuts.  However, even as yield curves flattened, SOR yields outperformed their US Libor equivalents, with the spread between the two short term interest rates contracting to a 3.5-year point tight.

            Fig 3: Singapore SOR yields are impacted by movements in S$NEER
            Source: Citibank, Bloomberg & JPMorgan Asset Management as at 12th February 2020

            Historically, SOR yields tend to increase when the S$NEER weakens – especially as it declines below the mid-point of its trading range (Fig 3b).  With the Fed on-hold for the foreseeable future and the MAS expected to ease S$NEER policy at its April meeting, it is likely SOR yields could climb further, creating attractive investment opportunities for cash investors who are able to lock in longer tenor securities.

            [1] https://www.mti.gov.sg/Newsroom/Press-Releases/2020/02/MTI-Downgrades-2020-GDP-Growth-Forecast-to--0_5-to-1_5-Per-Cent

            [2] https://www.mas.gov.sg/news/media-releases/2020/comments-by-mas-on-the-monetary-policy-stance

            • Liquidity
            • APAC

            RELATED ARTICLES

            China’s Interest Rate Pivot

            While China’s post-Covid-19 economic data is showing signs of normalization, the government’s focus on stability will have significant implications for monetary policy and interest rates

            Read more

            IOER – does the latest fed move have any practical implications for cash investors?

            The Fed’s interest on excess reserves (IOER) shot to prominence following an unprecedented adjustment by the central bank. We explore its impact on investors.

            Read more

            PBOC: small move, strong signal

            We look at why the People’s Bank of China’s (PBoC) made its recent and notable dovish pivot and its implications for investors

            Read more
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.