logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us
              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. Potential pathways for higher yields

            • LinkedIn Twitter Facebook WhatsApp

            Potential pathways for higher yields

            13/09/2018

            Andrew Norelli

            If the Three Phases Model turns out to be an accurate-enough framework for market dynamics during 2018, then longer-term interest rates will rise in aggregate over the course of the year. Not in a straight line though, but rather in a sine wave higher, then lower, and then higher once again. In many ways this feels like an unsatisfying way to get higher rates, and it probably doesn’t lead to dramatically higher yields anyway.

            Yet I and many of my fellow market participants seem to feel intuitively that rates should be higher. In the old days, if we had the level of growth the US is currently enjoying, 10-year Treasury yields would be higher than they are now. This intuition is supported by quantitative models also, for example the Taylor Rule, the Nominal GDP versus 10-year yield linkage, and the ACM term premium model all suggest rates are far too low. When you couple the intuition with the math, and layer on top the obvious increase in Treasury supply from the budget deficit and Quantitative Tightening, it feels downright weird that Treasury yields aren’t higher.

            Much of my constructive view on rates (during Phase 2) has been rooted in the idea that because potential growth is slow, the labor market is tight, and the fiscal stimulus is ill-timed, monetary policy should welcome tighter financial conditions explicitly to slow down realized growth. Unless and until financial conditions begin to materially impact the economic data, the Fed should and would act to constrain inflation pressure. In practice, that meant continuing gradual hikes and balance sheet reduction. This leads to a flatter curve and weak-ish risk markets, together with anchored inflation expectations and long-end rates (Phase 2).

            The nagging feeling in the back of my mind remains constant though, that rates should be higher intuitively. So I am continually vigilant for what sequence of events from here could lead to durably higher long term rates. Some of these I’ve mentioned in this forum over the past year, but my current list is:

            1. Evidence that the accumulated effects of monetary policy tightening to date, inclusive of balance sheet reduction, are slowing the economy toward its potential growth rate unnecessarily quickly. In order to maintain its shot at an eventual soft landing, the Fed pauses, allowing risk-on sentiment to fully swing back into markets (not just in US equities). This results in a bear steepening, with the front-end of the curve anchored by low policy rates, but long-term Treasury yields going higher through both real rates and break-even inflation rates. When the Fed takes a pause, ultimately it lifts the market expectation of terminal policy rate to something restrictive rather than neutral, and also pushes out in time the end of the tightening cycle. Term premiums also expand as global risk aversion abates.

            2. A durable surge in labor productivity, which would lift the potential growth rate of the US, while the realized growth rate can maintain the stimulus-fueled lofty levels. The gap between these two growth rates when the economy is at full employment represents inflation pressure, so shrinking the gap reduces inflation pressure, all else equal. In response, the Fed can slow down their tightening process, but ultimately arrive at a higher terminal rate because higher potential growth rates should allow higher equilibrium policy rates. The curve bear steepens in this case, led by real rates (as opposed to break-even inflation rates).

            3. If the Fed encountered a surge in inflation and actively chose to ignore it, intentionally opting to let the economy run hot. The Treasury curve bear steepens here too, but this time, it’s led by break-even inflation rates while real rates and the front end remain anchored by low policy rates. Alternatively, an inflation spike which triggers an appropriately aggressive Fed response results in a flatter curve, but whether the 10y yield goes up or down is less clear.

            4. If President Trump were to succeed in influencing the Fed to hold policy rates too low compared to what would be necessary to maintain their 2% Core PCE inflation target. In this case, the price stability mandate is compromised. So far there have been at least 1 tweet and 2 interviews in which he expressed “[t]ightening now hurts all that we have done.” This results in a bear steepening also, led by breakeven inflation rates with the front end artificially anchored.

            5. If the President via the Treasury were to actively intervene in the foreign exchange market to devalue the dollar, and/or purchase non-dollar securities. Same thing – bear steepening as inflation expectations become unanchored, and Fed loses one key element of financial conditions policy transmission mechanism: the free-float exchange rate.

            The key theme is that all of these cases involve the central bank leaning dovish, whether that’s justified or unjustified, intentional, or unintentional, which all together is a bit of a paradox. It’s much easier intuitively to link a Federal Reserve aggressively hiking rates with a higher 10y yield, but at this point, given what’s already understood in the market about US growth and the supply/demand dynamic for Treasurys, I think it is actually dovish policy of some kind which will ultimately lead to higher rates. A subset of this has been a key element of the Three Phases Model – in Phase 3 we expect higher Treasury yields concurrent with a dovish course correction which most closely resembles item 1 in this list. But durably (and significantly) higher 10-year yields probably require at least one of these 5 circumstances, or something similar.

            Rewind to August 24, 2018, Jackson Hole, WY. Fed Chair Jerome Powell gave a speech entitled Monetary Policy in a Changing Economy, which included a number of debatable and dutifully balanced passages. However, I cherry picked the following quotes and generally saw the speech as unnecessarily dovish:

            “Under Chairman Greenspan’s leadership, the Committee converged on a risk-management strategy that can be distilled into a simple request: Let’s wait one more meeting; if there are clearer signs of inflation, we will commence tightening. Meeting after meeting, the Committee held off on rate increases while believing that signs of rising inflation would soon appear. And meeting after meeting, inflation gradually declined….

            “In retrospect, it may seem odd that it took great fortitude to defend ‘let’s wait one more meeting,’ given that inflation was low and falling. Conventional wisdom at the time, however, still urged policymakers to respond preemptively to inflation risk…

            “While inflation has recently moved up near 2 percent, we have seen no clear sign of an acceleration above 2 percent, and there does not seem to be an elevated risk of overheating. This is good news, and we believe that this good news results in part from the ongoing normalization process.”

            For now anyway, inflation seems to be in the eyes of the beholder. Given what could be said about the chart below and whether or not Core PCE is accelerating, and explicit references both to Greenspan’s fortitude in not hiking rates and an explicit lack of overheating risk, the speech looked dovish to me. It had elements of items 1 and 3 from my list above, and maybe even a hint of number 4.
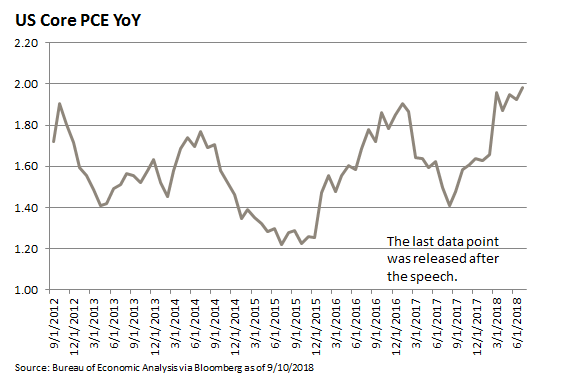
            For these reasons, I viewed the speech as a short-term bearish signal for Treasurys and I think Powell’s remarks more than any other catalyst are what sent 10-year yields back toward the high end of the range in recent days. However, it’s just one speech, and I don’t think any of my proposed pathways to higher rates have been definitively satisfied. The average hourly earnings data last week offered more evidence that a dovish course correction is not yet justified by the data, and the Fed should see it that way. So, structurally, I think we’re still in for more Phase 2 price action: weak-ish risk markets, stronger dollar, and range-bound-to-lower yields. The recent market response to Jackson Hole merely lends some credence to the idea that dovishness of some kind would be the current pathway to higher yields.

            • Federal Reserve
            • Central Banks
            • Market Views
            • Yields
            • Inflation
            • Monetary Policy
            • Economic Outlook

            RELATED ARTICLES

            Watch the lag: thoughts on core CPI (part 2 – an update)

            We analyze which economic indicators the Fed should pay attention to and which ones are false alarms.

            Read more

            The forest and the trees

            When constantly watching financial markets and following the 24-7 news flow, it can be easy to get caught up in the trees and miss the forest.

            Read more

            Getting the market back on its feet

            Market functionality needs to be restored no matter how anyone feels about the methods it may take to get there. If the current market conditions persist, the consequences may be severe.

            Read more
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.