logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us
              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. Key macro risks for bond portfolios in 2020

            • LinkedIn Twitter Facebook Line WhatsApp

            Key macro risks for bond portfolios in 2020

            21/02/2020

            Merveille Paja

            Markets will always be vulnerable to the “unknown unknowns,” the risks we don’t know we are unaware of. There are also the “known unknowns”—risks to which we can apply judgement and analysis in assessing the likelihood of particular outcomes and their ramifications. Last year, the main macro concerns for fixed income markets were intensifying trade wars, a hard Brexit, and an EU economic growth slowdown, some of which materialized.  Below is an outline of some of the known unknowns we believe fixed income investors should be focusing on this year.

            Slowdown in emerging markets and China: Coronavirus and trade war

            Although concerns around emerging markets were related to the escalation of trade wars last year, the coronavirus is now at the forefront of investors’ minds. Its impact on China’s growth through 2020 could be significant. Some analysts are forecasting zero or even negative growth for the first quarter and the timing and speed of a growth rebound in subsequent quarters remains uncertain. Data availability adds to the uncertainty around the scale of the issues and therefore the inability to evaluate the virus’s repercussions.  The risk of a trade war reescalation should also not be ignored, despite this year’s U.S. presidential election and the implementation of the so-called “Phase 1” trade deal.

            Global recession

            The impact of China’s slowdown on the global economy will likely be larger than that of the SARS epidemic of 2003, given China’s growing share of global GDP (currently about 20%, based on purchasing power parity[1]. Globally, the world is still in a slow growth, low inflation environment and the green shoots of growth seen toward the end of 2019 remain fragile and survey-based. Any reescalation of trade tensions between the U.S. and China or the U.S. and Europe could push global growth toward a sharp slowdown. If such risks were to materialize, major central banks would have little ammunition to ease—particularly the ECB, which has already pushed rates into deep negative territory.

            Higher-than-expected inflation

            While global growth continues to be slow, we see signs of inflation picking up in some emerging markets. We have seen an increase in inflation in China, India and Poland, mainly driven by an increase in food prices. Market participants don’t consider developed market inflation to be a material risk partly due to other items, such as global recession, growth slow down etc., and given historically low breakeven inflation (The EU five-year breakeven inflation rate is currently at 1.21%, a historical low). However any increase could easily surprise the market and make an inflation shock a reality.

            U.S. presidential elections: Market-unfriendly results?

            One of the biggest risks that could catalyze a correction would be if a corporate-unfriendly candidate gains momentum. We will be watching the results of Super Tuesday on March 3. So far, after the Iowa caucus and New Hampshire primary, Democratic presidential hopefuls Bernie Sanders and Pete Buttigieg are pretty close. We expect a risk-on scenario if the most market friendly candidate wins while we expect a risk-off scenario in the event that a non-market friendly candidate wins.

            Hard Brexit

            Despite the UK’s departure from the EU at the end of January 2020, there is still no certainty on a transition deal that would give the market more visibility out to 2021. It is difficult to forecast how Gilts would trade in the event that no UK-EU transitional trade deals were reached and if UK economic data weakened. Would there be a traditional risk off reaction, with lower yields in the short term—or would concerns about UK credit risks drive yields significantly higher for the medium term?

            Political unrest

            It is reasonable to assume that political risk will be a market issue again this year. Instability in Iran and the Middle East remains a risk as do North Korea’s potential nuclear capabilities. Social unrest in Latin America, particularly in Chile and Ecuador, remains a tail risk that could put pressure on oil prices and the bond market. Political rebellion and social unrest can also be seen in political upheaval in the Catalonia region of Spain and more recently in Hong Kong.

            Significant fiscal policy

            Momentum is toward more fiscal easing globally; over time this could drive yields higher, given greater bond supply and support for growth. We expect to see moderate fiscal easing in the eurozone, especially in Germany, with increased investment in the green sector. We could also see more fiscal spending in other areas of the EU, though it is currently uncoordinated and tentative. In the U.S., if the next president wins on a strong mandate with a majority in both houses of Congress, we could see another fiscal package implemented in 2021 that would likely give a boost to the U.S. economy. We also anticipate stronger fiscal support for growth in China, especially in the form of medical investment to contain the coronavirus epidemic.

            EU political risk

            Following the UK’s exit from the EU, the risk is that any other EU country could decide to take the same path; that raises the question of the likelihood of a potential eurozone breakup. In addition, market participants should closely monitor the risk that spreads on bonds of countries on Europe’s periphery could widen.

            Climate risk

            How to understand and measure climate risks on fixed income portfolios is evolving, but risks can be split broadly into physical and transition risks—meaning impacts on companies’ assets from adverse climate events—and risks from policy and consumer responses to climate change. For investors, factoring climate risks into fundamental credit analysis of various industrial sectors is critical. In 2020, it will be important to monitor closely any sectoral impacts from the European Green Deal set out in December 2019 and the subsequent European Climate Law expected to be passed in March.

            In evolving markets, it is important that client portfolios are stress-tested for a variety of outcomes and scenarios. We’ve highlighted some of the “known unknowns” that we are focusing on. There will be many views about their likelihood and impact. The table below shows our view of possible market reactions.
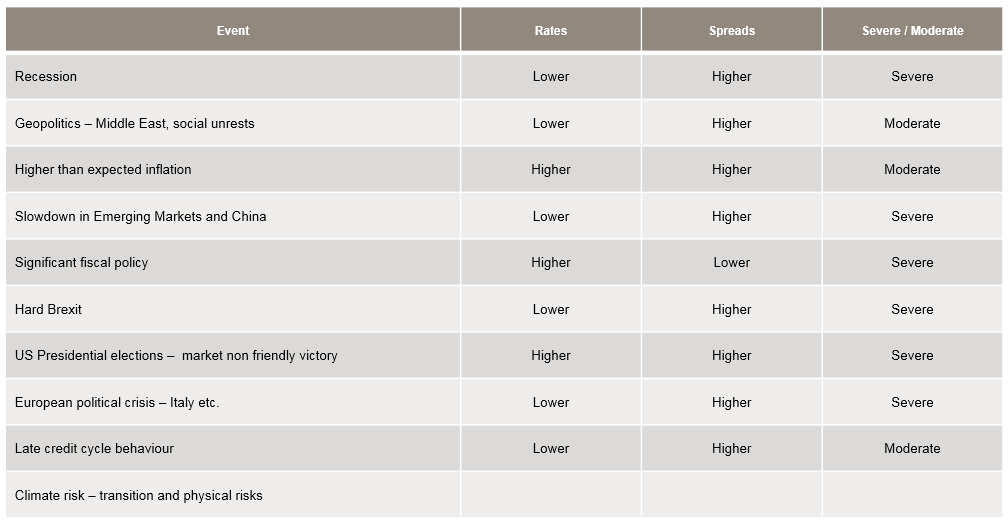
            What is likely to be more challenging are the unknown unknowns. Should they come, we will be vigilant and ready to respond.

            [1]https://www.imf.org/external/datamapper/PPPSH@WEO/OEMDC/ADVEC/WEOWORLD/CHN

            • Economic Outlook
            • Market Views

            RELATED ARTICLES

            Watch the lag: thoughts on core CPI (part 2 – an update)

            We analyze which economic indicators the Fed should pay attention to and which ones are false alarms.

            Read more

            The forest and the trees

            When constantly watching financial markets and following the 24-7 news flow, it can be easy to get caught up in the trees and miss the forest.

            Read more

            FOMC statement & potential impact on fixed income

            Looking beyond the disappointing press conference, we believe the FOMC is employing a proactive risk management approach as opposed to a reactionary policy.

            Read more
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.