logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us

              About us

              Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. Confirmation, Conflict, Hope

            • LinkedIn Twitter Facebook Line WhatsApp

            Confirmation, Conflict, Hope

            02/06/2020

            Bob Michele

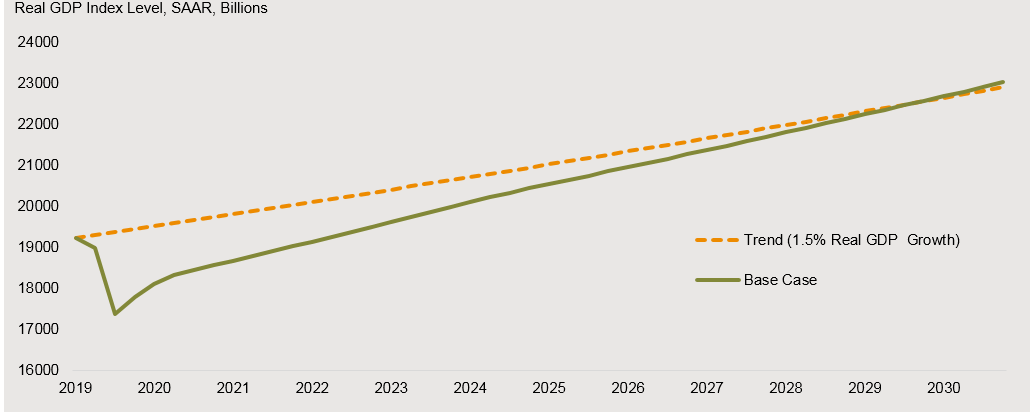
            Over the last couple of months, we have received a lot of criticism for our economic forecast. In attempting to model what a recovery could look like following the pandemic, we were estimating that it would take about 10 years to close the output gap and return to something approximating full employment.

            Real GDP GFICC Base Case Forecast verus Trend Growth starting Q4 2019
            Source: J.P. Morgan Asset Management, BEA and Bloomberg as of 6/1/2020

            Of course, the push back centered on the overwhelming fiscal and monetary policy response which has been a multiple of what was experienced during the Great Financial Crisis (GFC)…and deployed in weeks as opposed to years. It is true that if GDP is modeled on an annualized quarterly basis, the recovery will look like a ‘V’ with the bottom being put in 2020 Q2. This is what we saw during the GFC. But if GDP is modeled versus its long term potential, it will take about 10 years to return to that trend line. Hence, our view of a check mark shape recovery…..again, similar to what we saw after 2008 when it took about 8 ½ years to return to the economy’s long term potential.

            This week, the Congressional Budget Office released a letter to Democratic Leader Charles Schumer effectively confirming our original analysis. https://www.cbo.gov/system/files/2020-06/56376-GDP.pdf

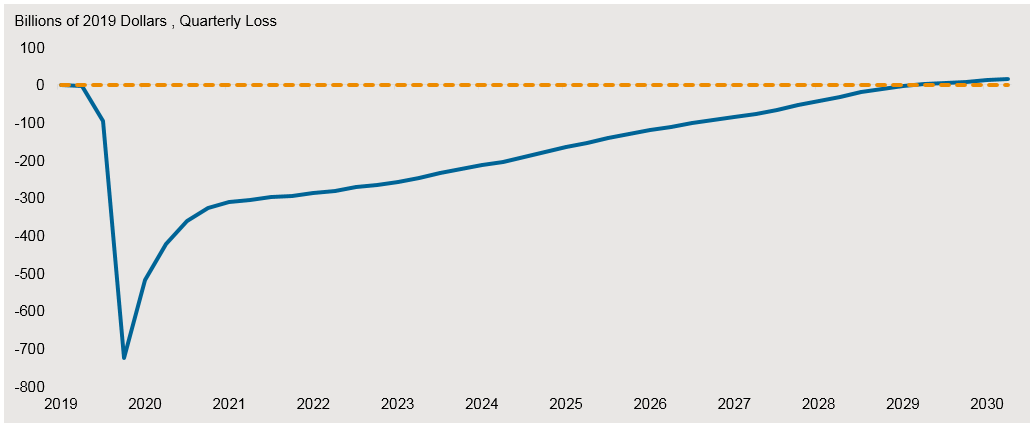
            In a normal year, the CBO forecasts economic variables going out 10 years bi-annually. Following the coronavirus, their January 2020 forecast looked woefully out of date. In May, they took their first stab at projecting the new economic reality out to 2021 warning that unemployment could still be double digits for much of that time. Now, with some more time to gather information, the CBO is looking out to 2030 and has formally revised its growth estimates lower for every year until 2029. We should note that their original forecasts were already more rosy than ours (and they also use a higher trend growth rate) but this at least implies the output gap won’t be closed till at the earliest 2027 according to their new estimates.

            Difference in Real Gross Domestic Product Between CBO’s May 2020 and January 2020 Projections
            Source: CBO as of 6/1/2020 

            The importance of both our analyses is to highlight that the road to recovery will be long and challenging. Inflation will remain low and unemployment will be unacceptably high. This is an unfolding reality that policy makers (public and private) must accept and begin to deal with.

            Like everyone, I am very disturbed by the events of the last week. I have worried for months that on June 5th, we might see an unemployment rate in the US print at over 20% just as the equity markets are rising back toward their highs. The pandemic is disproportionately taking a toll on our underserved and minority communities while the aggregate policy response seems to be inflating asset prices once again. Growing frustration was bound to erupt and the horrible death of George Floyd became the unfortunate catalyst. Like some others, I am worried - but hopeful - that there can be a path to recovery which is promising for all.

            I do not blame the Federal Reserve or the other central banks for their policy response. They have done what was needed to help underwrite the amount of debt needed to fund a recovery. Trillions upon trillions upon trillions. What all policy makers should take away from the GFC is that austerity – a concentrated focus on deleveraging and paying down debt – is the wrong policy response for the foreseeable future. And by all policy makers, I mean central bankers, politicians and corporate CEOs. At a time when unemployment is high, policy makers should be looking for longer term solutions and investments.

            Perhaps an infrastructure spend of $1T in the US spread out over 3-5 years instead of the 10 years mooted a few years ago would be a good use of public funds? It would create jobs, provide genuine stimulus in contrast to what we believe is currently aid and assistance, and encourage more durable consumption. And surely, the pandemic has highlighted deficiencies in our healthcare system which could be addressed at both the Federal and local levels of government. And this time, corporate CEOs need to be incented to invest in capex rather than to deleverage and then buy back stock or raise dividends. Certainly corporate investment and spending could be undertaken to catch up to the work-from-home/stay-at-home movement. I am sure that everyone has very good ideas of their own which could be added to this list.

            I realize that all of this will exacerbate the debt burden. But the central banks are helping to make the cost affordable and the potential benefits are appealing.  History has taught us that every crisis will present opportunities. Let’s hope this time the opportunity is broadly diverse and inclusive.

            • Economic Outlook
            • Market Views

            Related Content

            Watch the lag: thoughts on core CPI (part 2 – an update)

            We analyze which economic indicators the Fed should pay attention to and which ones are false alarms.

            Read more

            The forest and the trees

            When constantly watching financial markets and following the 24-7 news flow, it can be easy to get caught up in the trees and miss the forest.

            Read more

            FOMC statement & potential impact on fixed income

            Looking beyond the disappointing press conference, we believe the FOMC is employing a proactive risk management approach as opposed to a reactionary policy.

            Read more
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.