logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us

              About us

              Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. A “structural reform” for the kids

            • LinkedIn Twitter Facebook WhatsApp

            A “structural reform” for the kids

            20/07/2017

            Andrew Norelli

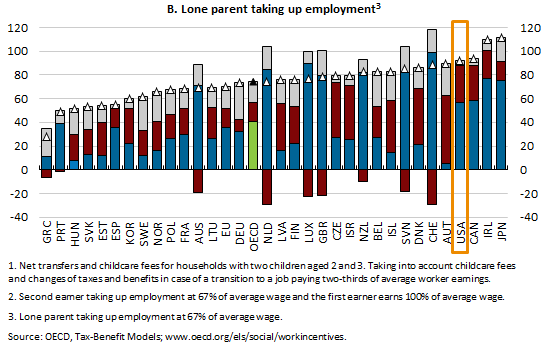
            The Group of 20’s stated goal is “strong, sustainable, balanced, and inclusive growth.” Amen to that. The quality-of-life triple threat of low productivity, unfavorable demographics, and stifling income inequality would all be licked if the G20 achieves that goal. The challenge of course is how to get there. Policy makers, economists, and the group itself all fall back on the tried-and-true prescription of “structural reforms.” That catch-all phrase is prominent in their publications, but one usually has to dig deep to uncover the specifics of what, really, these folks are recommending. For the US, infrastructure investment, tax reform, and regulatory reform—to the extent they rigorously address inefficiency, productivity, or inequality—would all count. Today, however, I want revisit in more detail a different proposal that I’ve discussed in the past, and expand on it with three key charts from the Organisation for Economic Co-operation and Development (OECD).

            In short, a wholesale change in the US approach to childcare could have a profoundly positive impact on growth and quality of life. The idea is unusual, in that it is motivated by two factors which are often in conflict but here are aligned: first, a clinical focus on key macroeconomic outcomes, and second, deferential attention to small-scale outcomes for human individuals which improve the opportunities, incentives, and quality of life for families in the economy. The result could unlock significant gains in both productivity and hours worked, while at the same time counteract rising inequality—the three keys to sustainable and inclusive growth.

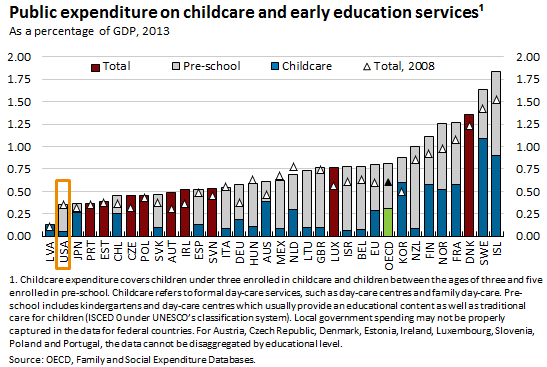
            The United States government spends the second-least on preschool and childcare of the 32 individual countries plus the EU, measured as a whole, studied by the OECD:
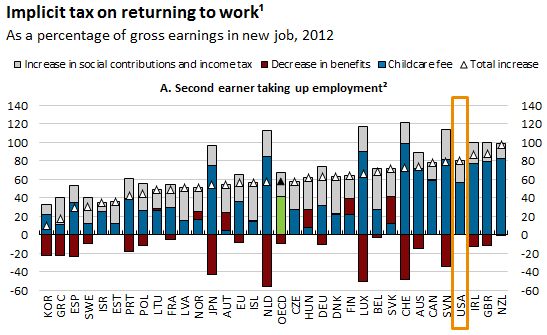
            When parents consider re-entering the workforce, childcare costs are a significant deterrent to doing so. For single parents, as well as the second earner in a two-parent household re-entering the workforce in the United States, the implicit tax rate is the fourth-worst in the OECD. It totals some 80%+ of gross pay just for taxes, childcare, and benefit reductions:
            The result is an inefficient system, where primary caregivers are compelled to provide in-home childcare in lieu of participating in the wider economy. The impediments persist as children grow and their care needs are only partially met by primary school, with summer holidays and significant portions of the traditional workday hours still not covered. Parents are forced to accept jobs which can accommodate a certain schedule, rather than jobs which allow them to maximize their productivity, earnings, and participation in the economy.

            If the United States treated childcare like public education, where every parent who wished could enroll their children in all-day, enriching childcare at little or no out-of-pocket cost, the economic benefits on both a macro and micro scale could be substantial:

            1. Job creation: the many primary caregivers who are talented and passionate about the work could do it professionally (and this is a job that is not easily automated!). The infrastructure needs on an upfront and ongoing basis are also potentially significant, requiring skilled construction work, regardless whether the programs are publicly or privately administered.

            2. Increased labor force participation and hours worked: the implicit “re-entry tax” would be removed as a serious disincentive to join the labor force and barrier to pursuing new skills training.

            3. Increased productivity: individuals, as they see fit, can pursue jobs to maximize their quality of life, earnings, and contribution to the economy, at a level greater than the (purely monetary) cost of caring for 1.9 children per day, which is the average number of children under 18 in each household with children.

            4. Decreased inequality: childcare is a benefit for all families, paid for by the existing progressive tax system.

            5. The first four are dispassionate assessments of the raw 1st order macroeconomic effects, which would be critical to justifying the expense and helping pay for it over the short term, but there is a bigger issue at the heart of the proposal with longer-term implications. Providing all children with equal access to robust early childhood education, reliable care, and a structure through which other basic health and nutrition needs can be met efficiently and consistently will help strengthen the youngest generation of Americans. They are the future US economy.
               

            Clearly any program like this, whether it’s done with physical structures, extensions of the public education system, or through vouchers and refundable tax credits would be costly. However, the realistic potential growth uplift outlined above allows “dynamic scoring” to be used with confidence for at least partial self-funding. Dynamic scoring uses future growth expectations, realized in the form of higher tax revenues, to fund current expenditures. The concept is frequently abused because growth forecasts are too optimistic, but in this case the pure economic effects are pretty simple. Near term funding through progressive taxation can provide a plausible bridge to a period of sustainably higher and more inclusive growth. Higher sustainable growth with less inequality allows a larger share of the economy to eventually make meaningful tax contributions. The ability of the economy to sustain less progressivity in the tax code ought to be a “win” for both political parties.

            Any structural reform which can plausibly create jobs, increase labor force participation, increase productivity, and reduce inequality would produce meaningful progress toward “strong, sustainable, balanced, and inclusive growth.” Reforming the childcare system could potentially do all of this, while encouraging participation and engagement in the economy by all parents who wish to do so.

            • Fiscal Policy
            • Latest

            RELATED ARTICLES

            FOMC statement & potential impact on fixed income

            Following the Fed's announcement, find our latest market views from the Global Fixed Income, Currency & Commodities Team (GFICC).

            Read more

            'Blue ripple' and the USD outlook

            The ‘Blue wave’ the market had prepared for now appears to be more of a ‘Blue ripple’ and currency markets are adjusting to a different political outlook.

            Read more

            How green are green bonds?

            With the influx of green, social and sustainable credit issuance this year, we take a closer look at whether these bonds present good value.

            Read more
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.