logo
  • My Collections
    View saved content and presentation slides
  • Portfolio Analysis
  • Log out
  • Funds
      Contact Us

      Fund Listing

      • Mutual Funds
      • ETFs
      • ETF Range
      • How to Invest

      Capabilities

      • All Funds
      • Alternatives
      • Equities
      • Fixed Income
      • ETF Investing
      • Active research
      • Model Portfolios

      In Focus

      • Investing for Income
      • Investing for Fixed Income
      • Investing for Global and EM Equities
      • Investing for Sustainability
      • Investing for Alternatives
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        • Guide to Investing in Asia

          The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

        • Weekly Market Recap

          Finding balance in Chinese equities: export sectors could gain from progress on trade, while domestic-facing companies cushion against global trade volatility.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Solving for Fixed Income

          Exploring how the current environment has affected fixed income's traditional role and the many other opportunities that can accomplish its traditional objectives.

        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        Portfolio Insights

        • Portfolio Insights Overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Equity Views

          The profit outlook is cloudier, but we still expect modest growth. Many of our investors favor quality financials and industrials, avoiding high-priced defensives.

        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Sustainable Investing

          Sustainable Insights

        • Alternatives Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Investment Ideas
          Contact Us
          • Latest ideas
          • Alternatives Outlook
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Multimedia
            • Insights App
            • Digital Portfolio Insights
            • Announcements
          • About Us
              Contact Us
              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Spectrum: Our Investment Platform
              • Our Leadership Team
              • Our Commitment to Research
            • Contact Us
              • My Collections
                View saved content and presentation slides
              • Portfolio Analysis
              • Log out
            • Financial Professional Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            On the Minds of Investors

            Energy Infrastructure: AI’s power play

            AW
            Adrian Wong

            Global Market Strategist
            Published: 04/11/2025
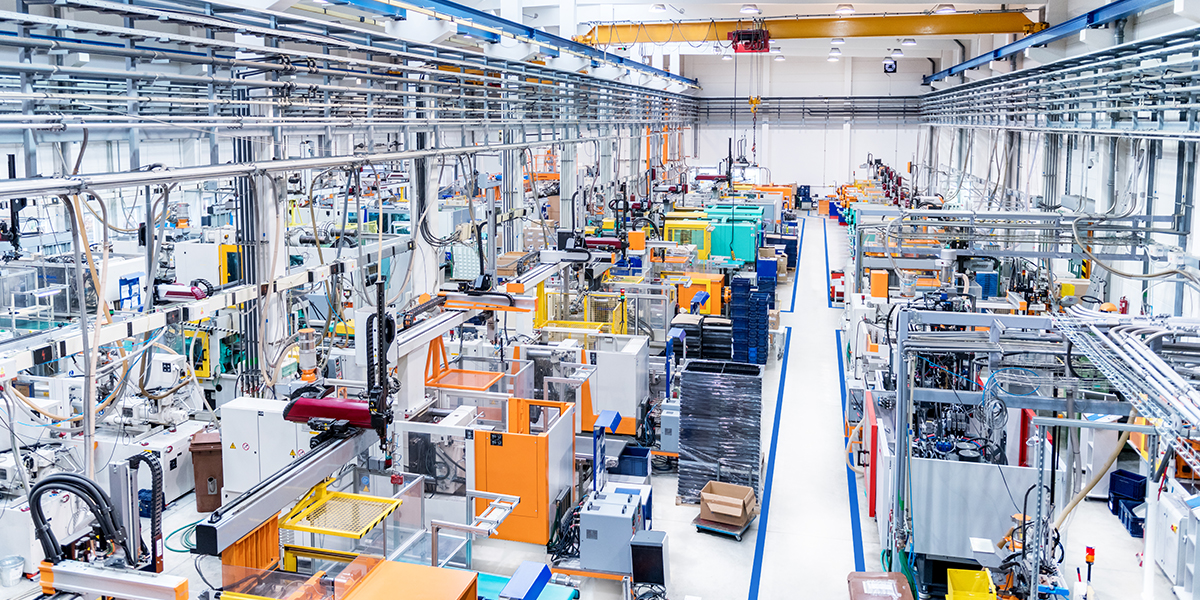
            The exponential surge in AI workloads in recent years has fueled further consumption needs for data centers and energy.

            In Brief

            • The exponential surge in AI workloads in recent years is fueling greater consumption needs for data centers and energy.
            • The confluence of rising energy consumption and multiple supply constraints is upsetting the energy demand-supply balance.
            • Private utilities and energy infrastructure assets stand out as a compelling way to tap the AI theme because of the low correlation of their returns to the public equity market.

            Artificial intelligence (AI) has emerged as the defining theme of the last few years, driving transformative demand across both the U.S. and Asian equity markets. From hyperscalers, developers and fabless companies, to chip manufacturers and cloud operators, the surge in AI adoption has had a pronounced impact on public market performance. While capital expenditure announcements on AI data center investments have grabbed investor attention, the critical issue of energy supply for these facilities has received comparatively less attention. However, this may represent a secular shift in global energy demand and reshape the investment landscape within the electricity supply sector, particularly in private infrastructure.

            This note covers the interplay between energy demand and AI data centers, energy supply and the current constraints, and the investments that are set to benefit from this demand-supply imbalance.

            How power hungry are AI data centers?

            Since the late 2000s, improvements in data center operational and hardware efficiency have offset the rising levels of electricity consumption driven by internet adoption and digital services. However, the emergence of cloud computing, streaming services, and social media platforms from the mid 2010s has tipped the balance, leading to a reacceleration in data center electricity demand. The exponential surge in AI workloads in recent years has fueled further consumption needs for data centers and energy (Exhibit 1).

            Despite advances in computing efficiency, the scale and intensity of AI computations have outpaced these gains. The growth in the average data center’s power load capacity has increased more than tenfold from only 6.2 megawatts (MW) a decade ago to 67.2 MW today (Exhibit 2). To contextualize this, a hyperscale AI-focused data center now consumes as much electricity as 100,000 households, with the largest facilities either under construction or announced expected to match the consumption of 2 million and 5 million households, respectively. Importantly, the market is experiencing an extremely tight supply environment, as reflected in the very low vacancy rates for data center capacity, highlighting the urgency and scale of the challenge of meeting future energy needs.

            Globally, data centers accounted for approximately 1.5% of total electricity demand in 2024, ranking just behind the top ten electricity-consuming economies1. Additionally, demand for AI and the power required to fuel data centers is expected to maintain its rapid expansion, with consensus forecasts anticipating a 13% annualized growth in data center energy demand over the next decade, potentially tripling their share to 4.5% of global electricity consumption. 

            Is energy supply catching up?

            Despite a broad range of potential electricity sources, several constraints limit the ability to meet the surging energy demand from data centers.

            Most new electricity supply projects require construction periods exceeding two years. This makes renewables, such as solar and natural gas, more viable options for delivery within that time frame. Longer-term solutions, such as coal, hydropower, and nuclear plants, may be phased in to address future demand.

            In response to the urgent need for capacity expansion, some companies are now attempting to bring decommissioned nuclear power plants back online. This approach offers a way to quickly add large-scale, reliable power, though it comes with regulatory and refurbishment challenges.

            Permitting for new energy projects is a lengthy process. From environmental assessments and land use approvals to safety and emission standards compliance, these complex approvals can extend the deployment time for energy construction, adding significant delays to the timeline for when new power supply comes online.

            Tariffs have also emerged as an obstacle, particularly for solar and wind power, as this raises the cost of construction for new installations, while the Trump administration’s position on renewables presents additional challenges.

            Supply chain bottlenecks may further complicate the outlook. For example, as energy demand surged over the last two years, the sudden increase in new turbine orders is straining upstream manufacturers, which have received limited  investment to increase production capacity over the past two decades as a result of flat energy demand growth. With order backlogs continuing to grow, expected turbine delivery times have extended correspondingly, delaying the deployment of new natural gas plants and adding incremental demand to existing plants.

            Investment implications

            The confluence of surging energy demand expected from AI data centers and limited near-term supply expansion is tipping the energy demand-supply balance after decades of muted growth. This transition is likely to favor energy producers and suppliers capable of bridging the emerging power gap – particularly those with scalable natural gas, nuclear, or renewable generation capacity. However, the opportunity set extends beyond generation itself. The build-out of transmission lines, grid interconnection, and supporting infrastructure also requires significant capital investment, creating a multi-year tailwind for companies across the broader electricity value chain. 

            For investors, private utilities and energy infrastructure assets stand out as another pathway to gain exposure to AI’s capital expenditure cycle, outside of traditional tech equities, while  offering the additional benefit of a low correlation with public equity returns (Exhibit 3). As well as being an additional source of diversification, infrastructure assets typically offer steady, predictable income streams, especially as demand for reliable power accelerates. Importantly, in an environment of elevated valuations and concentration within public markets, private infrastructure investments represent an alternative means to participate in one of the most consequential investment themes of the decade - energy transition. 


            1China (10.0k TWh), the U.S. (4.4k TWh), India (2.1k TWh), Russia (1.2k TWh), Japan (1.0k TWh), Brazil (0.8k TWh), South Korea (0.6k TWh), Canada (0.6k TWh), Germany (0.5k TWh), France (0.5k TWh), data centers (0.4k TWh). Source: Ember (2025) – with major processing by Our World in Data.


            09v3250411010026


            • Alternatives
            • Artificial Intelligence
            • Economy
            • Markets
            • Equities
            JPMorgan Asset Management

            • Terms & Conditions
            • Financial Services Guide
            • Privacy Policy
            • Cookie Policy
            • Investment Stewardship
            • Voting Policy
            • Unit Pricing Policy
            • Complaint Resolution
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Please note:  Following recent amendments to the Corporations Act, where unitholders have provided us with your email address, we will now send notices of meetings, other meeting-related documents and annual financial reports electronically unless the unitholder elects to receive these in physical form and notify us of this election. Unitholders have the right to elect whether to receive some or all of such Communications in electronic or physical form, the right to elect not to receive annual financial reports at all and the right to elect to receive a single specified Communication on an ad hoc basis, in an electronic or physical form.


            All investments contain risk and may lose value. This advertisement has been prepared and issued by JPMorgan Asset Management (Australia) Limited (ABN 55 143 832 080) (AFSL No. 376919) being the investment manager of the fund. It is for general information only, without taking into account your objectives, financial situation or needs and does not constitute personal financial advice. Before making any decision, it is important for investors to consider the appropriateness of the information and seek appropriate legal, tax, and other professional advice. For more detailed information relating to the risks of the Fund, the type of customer (target market) it has been designed for and any distribution conditions please refer to the relevant Product Disclosure Statement and Target Market Determination which have been issued by Perpetual Trust Services Limited, ABN 48 000 142 049, AFSL 236648, as the responsible entity of the fund available on https://am.jpmorgan.com/au.