

Week in review
- U.S. Federal Reserve raised policy rate by 25bps to 3.75%-4.00%
- Bank of Japan raised policy rate by 25bps to 1.25%
- China Aug retail sales rose by 0.4% y/y, YTD FAI declined by 7.2% y/y
Week ahead
- Trump-Xi summit
- U.S. Sep flash PMI data
- China Sep loan prime rates
Thought of the week
The Fed delivered a unanimous 25-basis-point rate hike to 3.75%-4.00%, its first increase since July 2023, reaffirming that inflation remains the overriding policy concern. Updated FOMC projections point to one more hike before year-end, with rates expected to stay elevated into 2027. Growth and employment forecasts were nudged modestly higher while inflation is projected to ease only gradually, broadly consistent with a soft-landing path. Chairman Warsh’s more proactive stance on bringing inflation back to target was a notable signal from this meeting. With no immediate signs of inflation relief, particularly given ongoing tensions in the Middle East, the Fed may need to continue tightening to achieve its mandate. On the investment side, higher yields are making fixed income more attractive from a total return perspective, though near-term volatility at the long end from fiscal concerns and issuance warrants some caution. On equities, the combination of elevated rates and stretched valuations in parts of the market suggests a more selective approach is needed, with opportunities in rate-resilient sectors and international markets where valuations remain more undemanding.
Federal funds rate expectations
Market expectations for the fed funds rate
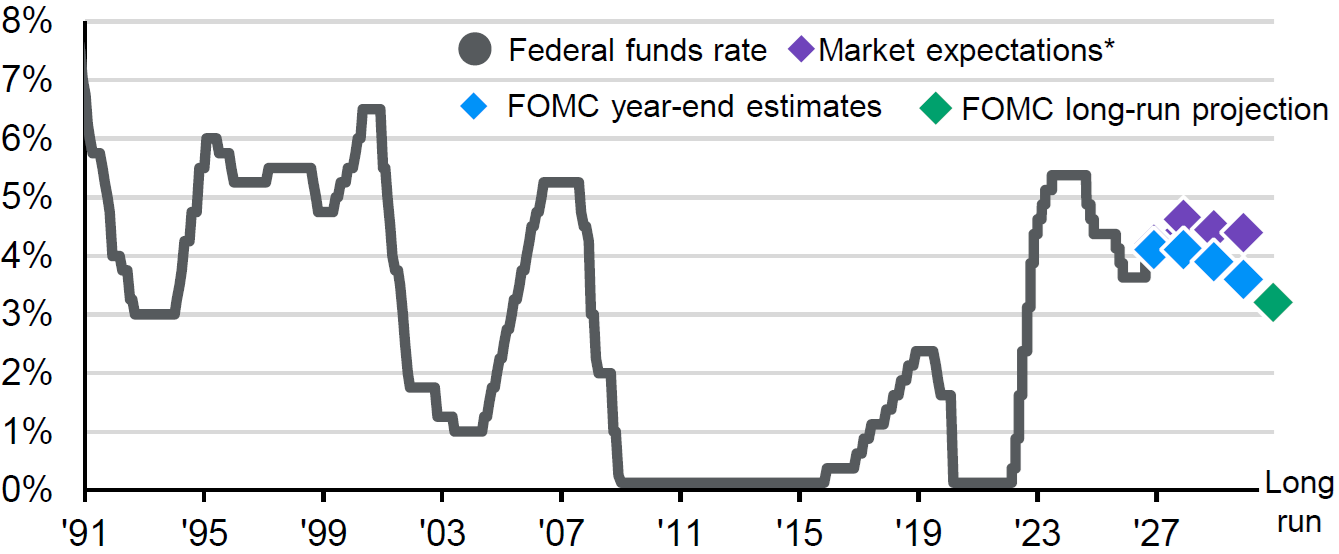
Source: Bloomberg, FactSet, U.S. Federal Reserve, J.P. Morgan Asset Management.
*Market expectations are based on overnight index swap rates. Federal Reserve projections shown are the median estimates of Federal Open Market Committee (FOMC) participants. Data reflect most recently available as of 16/09/2026.
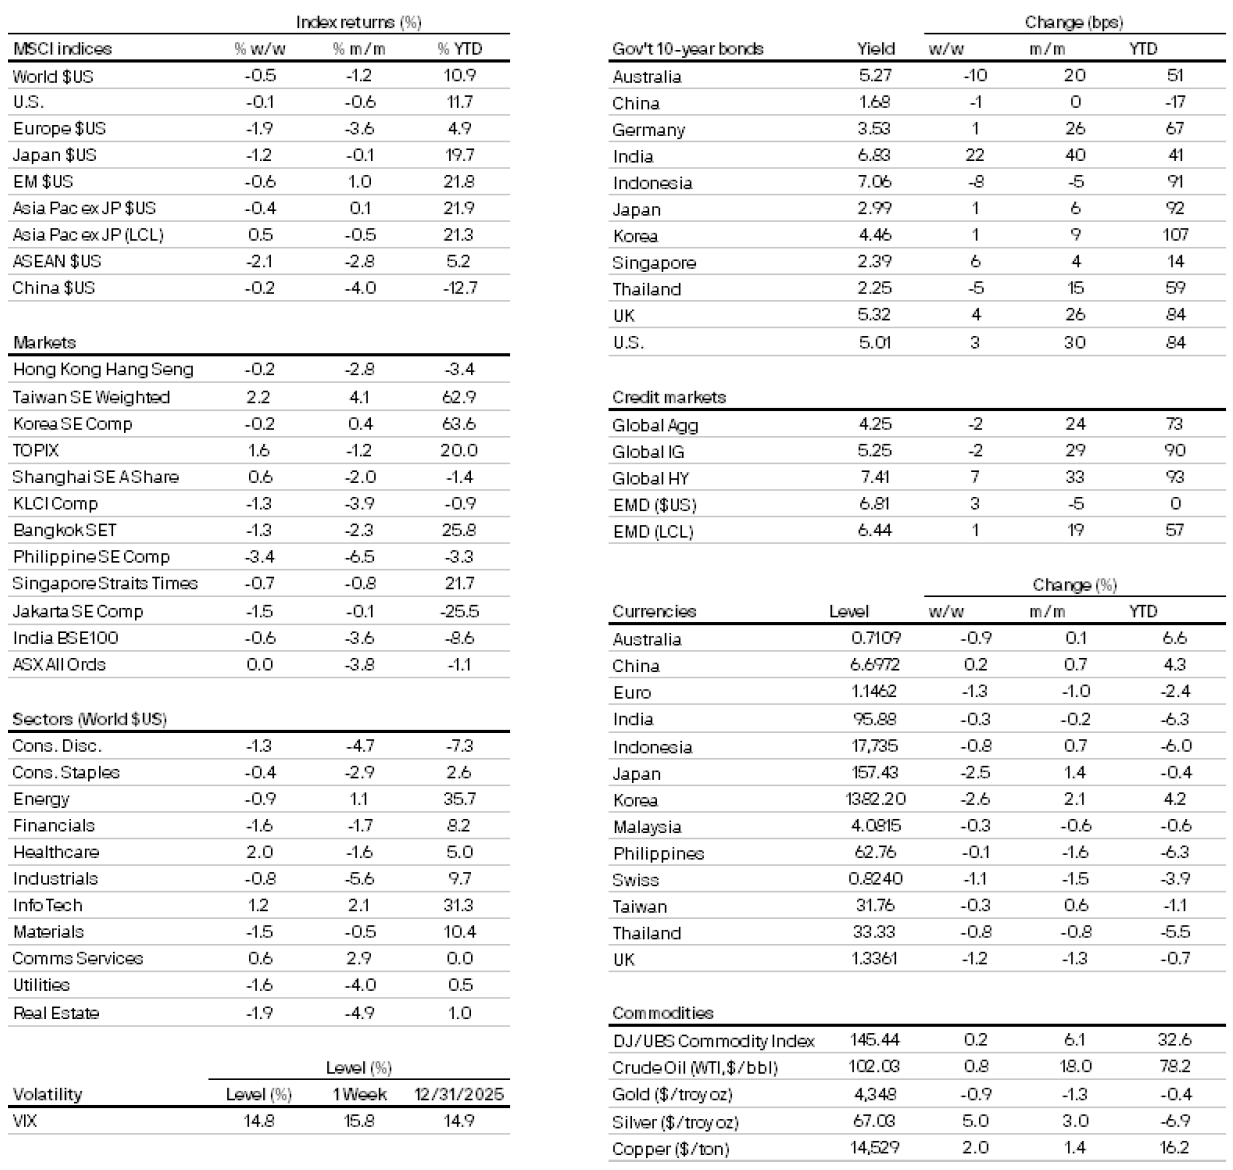
Market data
300a4900-f9d9-11e8-839f-fe2ee17e7f12
All returns in local currency unless stated otherwise.
Currencies’ return are based on foreign currencies per U.S. dollar. An appreciation of the foreign currency against the U.S. dollar would be positive and a depreciation of the foreign currency against the U.S. dollar would be negative.