


Week in review
- U.S. Federal Reserve held policy rate at 3.75%-4.00%
- Bank of Japan held policy rate at 1.25%
- European Central Bank held policy rate at 2.50%
Week ahead
- U.S. Oct employment data
- China Oct RatingDog PMI data
- Australia RBA monetary policy decision
Thought of the week
U.S. midterm election years have, on average, led to weaker equity performance, as political uncertainty weighs on investor sentiment. Yet 2026 has defied this seasonal pattern, with the S&P 500 gaining nearly 13% year-to-date, comfortably above the historical average of midterm election years at around 5%. Despite a sharp sell-off earlier in the year amid geopolitical tensions and inflation concerns, equities have staged a strong recovery, supported by resilient corporate earnings and continued AI-related investment. Nonetheless, much of this strength is concentrated among energy and technology stocks, underscoring an increasingly narrow leadership behind the headline market rally. With November’s midterm elections approaching, this year’s divergence serves as a reminder that while political cycles can influence market sentiment, earnings fundamentals and the breadth of market leadership will continue to be more important drivers of equity returns.
S&P 500 performance in midterm and non-midterm election years
Average historical price return vs. 2026, start of year = 100, 1980-2026
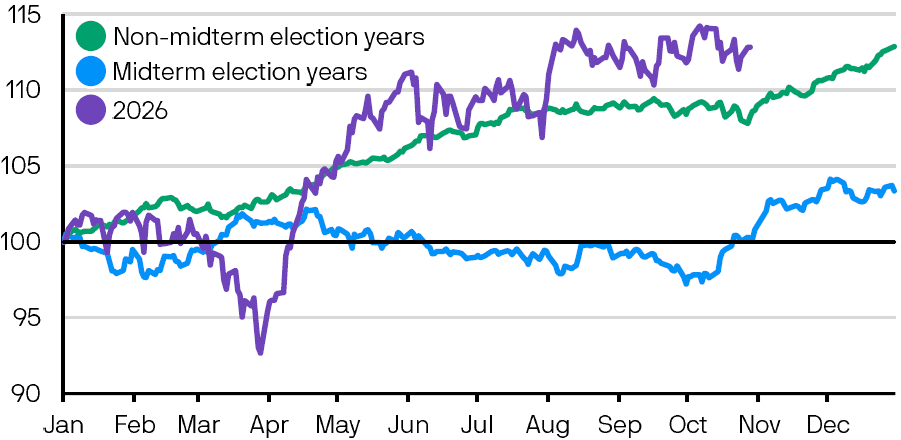
Source: FactSet, Standard & Poor’s, J.P. Morgan Asset Management. Past performance is not a reliable indicator of current and future results. Data reflect most recently available as of 28/10/2026.
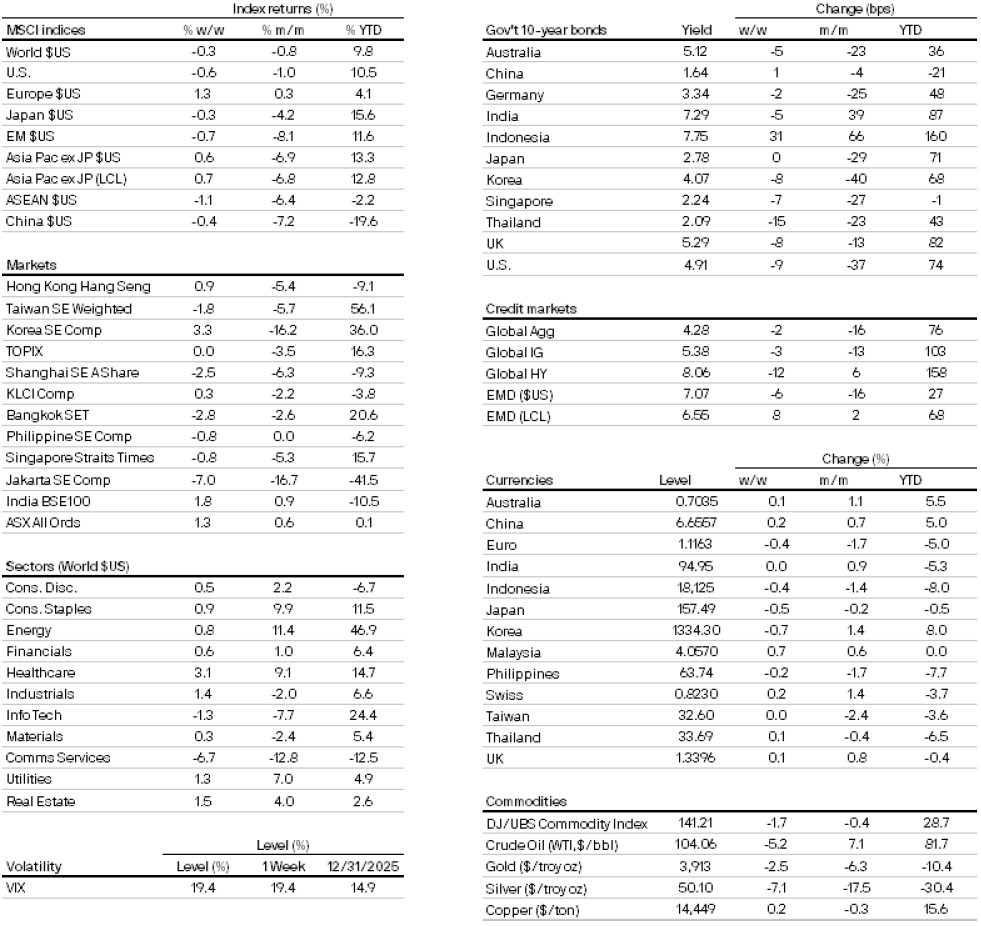
Market data
300a4900-f9d9-11e8-839f-fe2ee17e7f12
All returns in local currency unless stated otherwise.
Currencies’ return are based on foreign currencies per U.S. dollar. An appreciation of the foreign currency against the U.S. dollar would be positive and a depreciation of the foreign currency against the U.S. dollar would be negative.