JPAM_logo
  • My collections
    View saved content and presentation slides
  • Logout
  • Funds

      Fund Listing

      • All Funds
      • Fund Explorer
      • Fund Distribution
      • Fund Documents

      Capabilities

      • Equities
      • Fixed Income
      • Multi-asset
      • ETF Investing
      • Alternatives
      • Active research

      Featured Funds

      • Equity High Income Strategies
      • China Equity High Income Fund
      • Asia Equity High Income Fund
      • Global Equity High Income Fund
      • Fixed Income Solutions
    • Insights

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Weekly Market Recap

          Start each week with J.P. Morgan Asset Management’s one-page snapshot of top headlines, market performance, chart of the week and more.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Multimedia

          Interviews with Fund Managers and Investment Strategists bring you insights on global market trends and investment news.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        Portfolio Insights

        • Portfolio Insights Overview
        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Alternative Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        ETF Insights

        • ETF Insights overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

      • Investment Ideas
          • All Investment Ideas
          • What's new
          • Retirement and long-term investing
          • Sustainable investing
          • ETF knowledge
        • Resources
            • All Resources
            • Announcements
            • Forms & Literature
            • Investment Glossary
            • Library
            • Insights App
            • WhatsApp Communication
          • About Us
              • About us
              • Awards
              • Diversity, Opportunity and Inclusion
              • Our Leadership Team
              • Spectrum: Our Investment Platform
              • Our Commitment to Research
            • Partner With Us
            • Language
              • English
              • 中文/ Chinese
              • My collections
                View saved content and presentation slides
              • Logout
            • Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            Market Response

            Powell’s Final Act: Hold everything – rates, bias and Governor seat

            DK
            Dr. David Kelly

            Chief Global Strategist

            Published: 29/04/2026
            Market pricing has shifted hawkishly; the probability of a hike is now at 40% by next April.

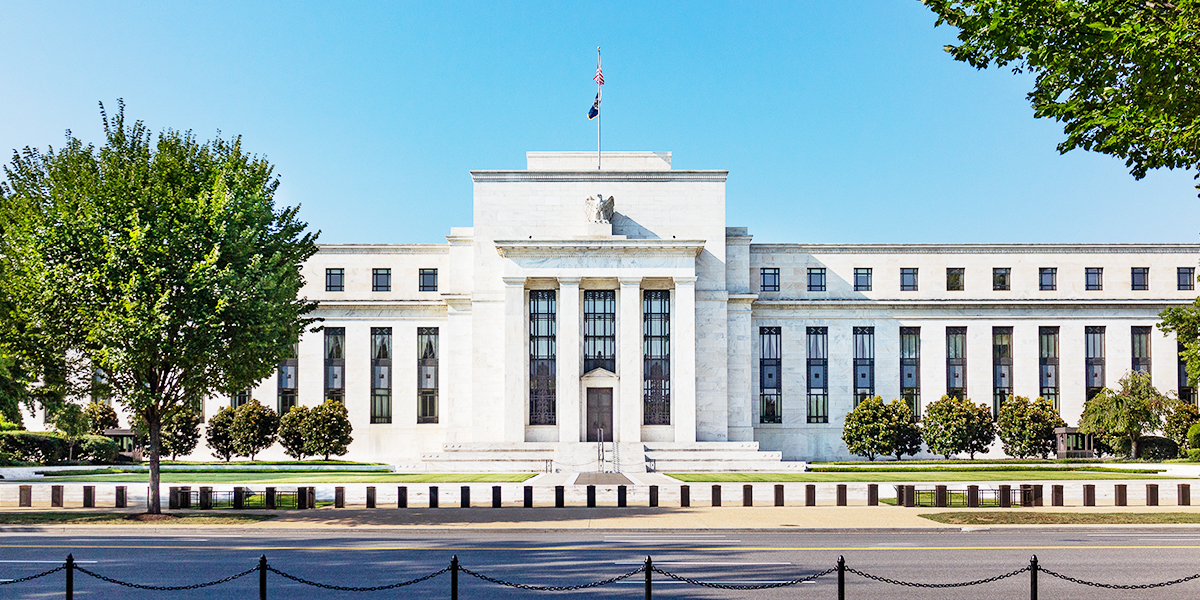
            The FOMC held the federal funds rate at 3.50%-3.75%. The key statement change: inflation language was upgraded from “somewhat elevated” to “elevated, in part reflecting the recent increase in global energy prices” – a direct acknowledgement of the Middle East driven oil shock. The easing bias in describing policy outlook was maintained, but not without opposition. Four members dissented, with Miran again, electing to reduce rates by 25bps, while Hammack, Kashkari and Logan agreed with policy on-hold but opposed keeping the easing bias, arguing the inflation backdrop no longer warrants it. 

            Key takeaways from the press conference:

            • Powell was forthcoming about his future at the FOMC and confirmed he will remain on the Board after his Chair term ends on May 15th for a period “to be determined”. His reasoning is due to the administration’s ongoing legal attacks against the Federal Reserve. He pledges to keep a low profile, support the incoming chair and avoid any shadow-Chair dynamic.  
            • Markets are fixated on the number of dissents; however, the committee is navigating two simultaneous supply shocks: tariff driven goods inflation and energy driven headline inflation, both of which are driving some members to lean more hawkish. Powell still expects tariff effects to show up as a one-time price level shift, though a wait-and-see approach around the energy spike may be more appropriate.
            • Powell remains committed to Fed independence. He argued Fed independence is about ensuring monetary policy decisions are made free of political considerations, which is foundational to U.S. economic credibility. He stated support for incoming Chair Warsh in maintaining the Fed as an independent institution.

            For investors, the Fed is likely to stay on hold for the foreseeable future. Pending price pressures are clearly seeping into more cautious views, but the bar to hike rates is still high. Given most of the committee feels current policy stance is within neutral, it can be patient as the conflict—and its ultimate impact on the economy and prices— unfolds. Market pricing has shifted hawkishly; the probability of a hike is now at 40% by next April. As a result, Treasury yields rose across the curve and stocks fell. 

            Altogether, the 8-4 voting split speaks to a lack of cohesion at the Fed during a time of elevated uncertainty, and this could get worse once Warsh replaces Powell. Moreover, the type of communication (statement, dot plot, etc.) and frequency may be more immediate changes under a Warsh-led Fed. We still support the Fed’s easing bias as supply shocks tend to be short-lived, however it’s important for investors to diversify across high-quality attractive yielding fixed income, stocks with resilient earnings growth, still actively valued international assets and a broad basket of commodities and real assets. 


            b4aab0cc-43db-11f1-897f-b52dde69af75
            • Economy
            • Markets
            J.P. Morgan Asset Management

            • Terms of Use
            • Privacy Statement
            • Cookies Policy
            • Investment Stewardship
            • Fund Notes
            • Offering Document(s)
            • Forms & Literature
            • Complaint Resolution
            • Guide to Using This Website
            • Sitemap

            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Important: This area of the website is intended only for distributors of JPMorgan Funds (Asia) Limited. Information is not intended for retail or public distribution. By using this information, you confirm that you accept the Terms of Use as set out in https://am.jpmorgan.com/hk/.

            Investment involves risk. Past performance is not indicative of future performance. In particular, funds which are invested in emerging markets and smaller companies may involve a higher degree of risk and are usually more sensitive to price movements. Investors should carefully read and consider the fund offering document(s), which contain details on investment objectives, risk factors, charges and expenses of the fund, before making any investment decisions. Information in this website does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service, nor a distribution of information for any such purpose. Informational sources are considered reliable but you should conduct your own verification of information contained herein. The above information has not been reviewed by the SFC, issued by JPMorgan Funds (Asia) Limited.

            Apple, the Apple logo, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. App Store is a service mark of Apple Inc.

            Copyright 2026 JPMorgan Funds (Asia) Limited. All rights reserved.