
Debt, debt everywhere: The implications of a high debt world
09/11/2020
Thushka Maharaj
Patrik Schöwitz
Sylvia Sheng
Jasslyn Yeo
Sean Daly
Key Points
- Asset classes’ performance will likely be affected by a new, high debt world in which investors, policymakers and economic systems have become more tolerant of large debt loads; high government and corporate indebtedness may also exacerbate market volatility in future recessions.
- For sovereign bonds, higher debt increases the long-term inflation risk premia we assume over our horizon for developed and emerging market (EM) debt. Active use of fiscal policy should create greater differentiation among bond markets, especially in emerging markets. In credit, high leverage keeps our investment grade spread assumptions above historical averages.
- For equities, high corporate debt should enable continuing high shareholder payouts – but revenue growth is the key metric determining if high debt helps or hurts returns, and the jury is still out. Developed market equities increasingly become a vehicle for income rather than capital appreciation, so investors may need to turn to EM equities and alternatives for return on capital.
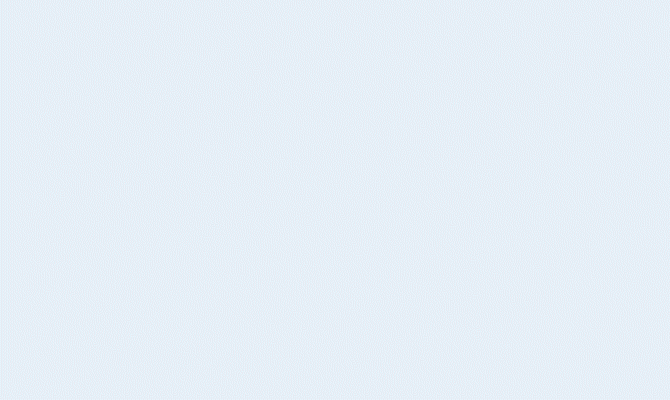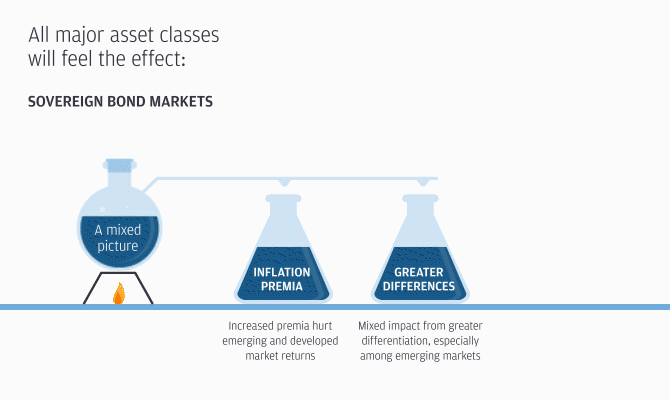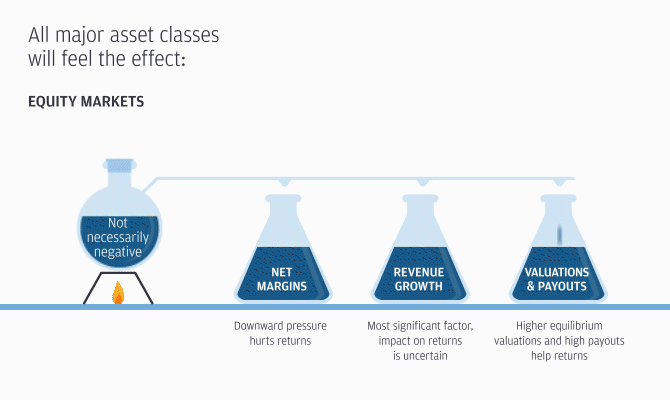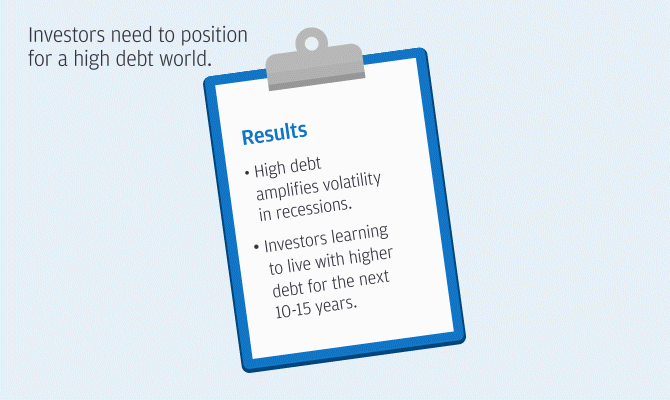
Our assumptions forecast a persistent, new, high debt reality. High and rising debt should affect most asset classes – public and private sectors, emerging and developed economies. One explanation: growing debt tolerance among investors increasingly willing to accept it, policymakers ready to adopt it and economic systems able to carry larger debt loads.
Aggressive central bank action suppressing interest rates over recent decades set the stage for a high debt world. Then, as the pandemic recession hit, central banks eased even further to enable fiscal stimulus packages. These conditions are likely to remain in place for an extended period.
What are the upshots for sovereign bonds? Higher debt levels increase the inflation risk premia we assume over our horizon for developed and emerging market debt (EMD). Active use of fiscal policy should lead to greater differentiation among bond markets, especially in emerging economies. (We have more confidence that U.S. policymakers can successfully raise inflation expectations than we do in the cases of Europe or Japan.) What has been a longtime co-movement of developed market (DM) government bonds is now at risk of dissipating over time, for developed market sovereign debt but most clearly in emerging markets.
After struggling with financial crises in the 1990s, many emerging market countries have implemented policy changes (including fighting inflation and issuing a larger share of debt in local currencies), leaving them more financially resilient. But this varies considerably across countries. Those with credible policy have been rewarded with DM-like yield curve performance. Others, slower to reform, have been penalised, even though central banks have started quantitative easing. Overall, we anticipate greater differentiation among EMD markets.
What are the implications of high debt for credit? U.S. corporations levered up in the last cycle, and we do not expect this to reverse – at least, not in the early part of this cycle – as strong monetary policy responses have provided cheap bridge financing. However, over time, rising rates should ultimately lead to deleveraging of balance sheets as the cost of debt servicing starts to rise again. High leverage metrics have the greatest effect on our investment grade spread assumptions, keeping them at 160 basis points, higher than the historical average.
For equities, high debt loads should continue supporting high shareholder payouts – although at reduced levels vs. recent years, driven by depressed earnings in the wake of the recent recession – while dragging on net margins. We expect revenue growth to be the key metric determining whether high debt helps or hurts equity returns, and the jury is still out. We expect the most pronounced effects in the U.S. market and the least in Japan. High debt also means equilibrium valuations well above historical levels.
What are the implications of a high debt world overall? Investors have to become accustomed to living in a high debt world. In this environment, DM equities increasingly become a vehicle for income rather than capital appreciation. Investors may have to turn to EM equities and alternatives for return on capital. We also expect high starting points for indebtedness to exacerbate market volatility in future recessions.
MORE THEMATIC INSIGHTS


For important information, please refer to the homepage.