
The fiscal decade: The promises, problems and potential of fiscal stimulus
09/11/2020
Dr. David Kelly
John Bilton
Michael Albrecht
Tilmann Galler
Tim Lintern
Nandini Ramakrishnan
Key Points
- In the decade ahead, a surge in fiscal stimulus will shape the new economic cycle.
- The real limiting factor on governments is likely not the level of debt but the level of debt service.
- Done right, fiscal stimulus can offer a quicker exit from recessions. Done wrong, it can undermine trust in government debt and national currencies.
In the decade ahead, we expect more active fiscal stimulus than at any time in modern financial history. And for the first time in many years, monetary and fiscal policy will be generally pulling in the same direction. How this new dynamic plays out could profoundly shape the economic cycle that began earlier this year in the aftermath of the coronavirus outbreak.
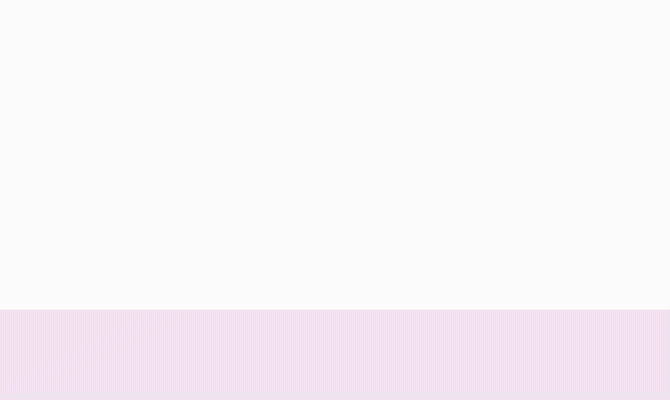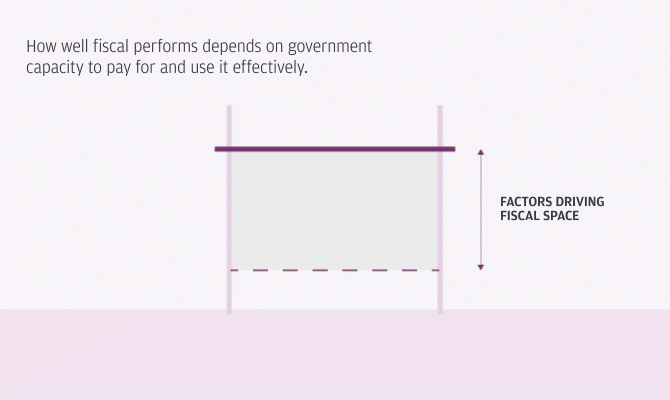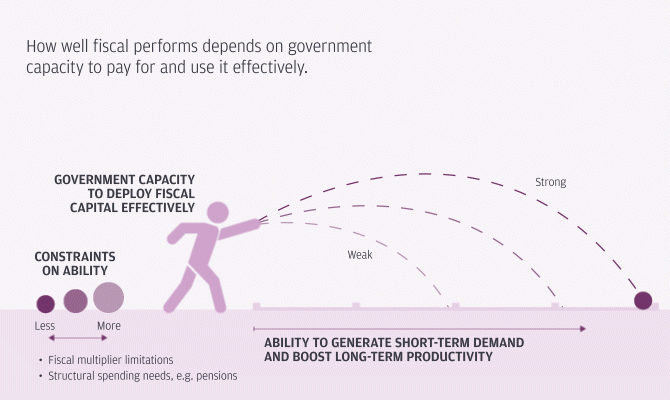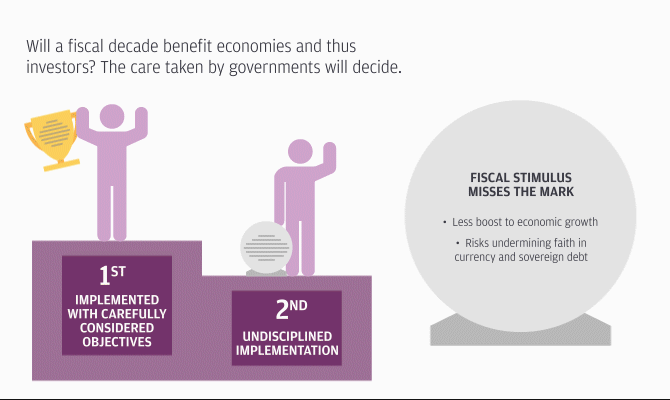
Two factors will determine how the story unfolds – a country’s capacity to deploy fiscal stimulus (its “fiscal capacity”) and its ability to make good use of the stimulus (its “fiscal effectiveness”).
A country with ample fiscal space can raise spending and expand deficits without causing its government bond yields to surge or its currency to be undermined. To estimate fiscal capacity, we combine our measure of fiscal space with a concept known as institutional robustness, assessed on factors such as ease of doing business and governance. A country with more robust institutions likely has greater capacity to boost spending.
Fiscal effectiveness refers to a government’s ability to spend capital in a way that boosts productivity. That ability will be restrained when the fiscal multiplier (how much an incremental dollar of government spending boosts GDP as it works through the economy) is low. Fiscal effectiveness may also be held back by structural issues that divert investment spending away from productivity growth, including pension obligations and health care spending, especially for economies with rapidly aging populations.
Done right, fiscal stimulus can offer a quicker exit from recessions and enables governments to provide broad social benefits. Taken to an extreme, though, undisciplined fiscal stimulus can undermine trust in government debt and national currencies.
How much debt is too much? The real limiting factor on governments is likely not the level of debt but the level of debt service. If interest rates and inflation remain very low, then governments can clearly increase borrowing without significant consequences. But when higher interest rates cause interest costs to absorb a significant share of a country’s budget, squeezing other areas of spending, both taxpayers and investors take notice.
This potential risk of higher interest rates in turn is largely driven by the risk of higher inflation. For almost four decades, inflation has trended downward in both developed and emerging economies. Some of that decline has been driven by greater income inequality, which has tended to reduce the demand for goods and services relative to their supply. Automation and the adoption of labor-saving technology also have kept inflation in check.
As the global economy recovers from recession, we could see a cyclical upswing in inflation. More importantly, if policymakers use fiscal policy to reduce income inequality, it might well increase the demand for goods and services while reducing the demand for financial assets such as bonds. That would increase both inflation and interest rates.
Given today’s starting point of low interest rates, low inflation and considerable slack in the global economy, active fiscal policy will likely define the decade ahead. Whether this turns into the decade of fiscal-powered economic progress or fiscal crisis will depend on the care with which governments and central banks deploy the tools they now seem ready to use.
MORE THEMATIC INSIGHTS


For important information, please refer to the homepage.