JP Morgan Asset Management - Home
  • My collections
    View saved content and presentation slides
  • Log out
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration

      Solutions

      • Funds Overview
      • Empower Share Class
      • Academy Securities
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy
      • Capitalizing on Prime Money Market Funds
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook

          Global Liquidity Investment Outlook

        • Tokenization
        • Case Studies
        • Partnership with fintechs
        • Leveraging the Power of Cash Segmentation
        • Cash Investment Policy Statement

        Market Insights

        • Market Insights Overview
        • Eye on the Market
        • Guide to the Markets
        • Market Updates

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency
        • Fixed Income
        • Long-Term Capital Market Assumptions
        • Sustainable investing
        • Strategic Investment Advisory Group
      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
          • Webcasts
        • About us

            About us

            Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

            • Overview
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Sustainable and social investing
            • Our Leadership Team
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My collections
              View saved content and presentation slides
            • Log out
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back
          1. Trading the thrill of the ECB chase

          • LinkedIn Twitter Facebook WhatsApp

          Trading the thrill of the ECB chase

          08/22/2019

          During July’s ECB monetary policy meeting, president Draghi managed to convince governing council members to make a number of dovish alterations to the opening statement (including references to lower levels of rates, tiering and QE), although he underwhelmed in the delivery of his dovish message during the press conference. Nevertheless, with Eurozone growth and inflation data continuing to disappoint and trade tensions, which have hit the export orientated German economy particularly hard, remaining elevated, we have maintained a view that the ECB will cut rates and restart QE at their September policy meeting.

          Market expectations of a substantial easing package from the ECB were reinforced by last week’s comments by the Finnish central bank governor Olli Rehn who emphasised the importance of the ECB outlining a ‘significant’ and ‘impactful’ stimulus package that overshoots market expectations. The impact of his comments were to significantly push Eurozone (and global) bond yields lower with roughly 2/3s of the Euro denominated investment grade bond market now trading with a negative yield. We believe the prospects of further significant easing by the ECB will be Euro negative, particularly as the ECB pushes Eurozone rates deeper into negative territory and investors reach for investments in other markets that offer more attractive yields. This trend has been apparent before each of the prior 4 ECB rate cuts in negative rate territory.
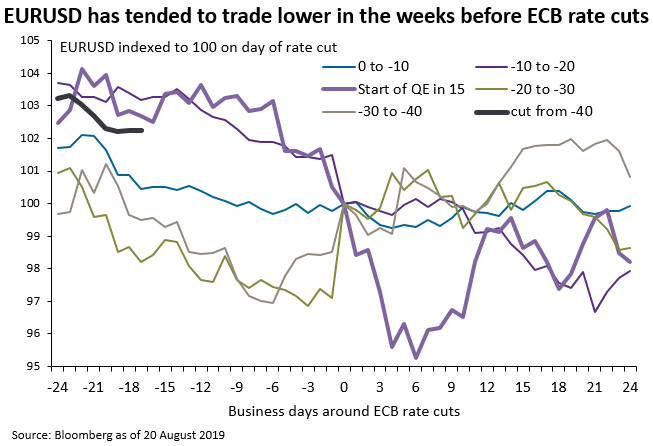
          EURUSD has tended to trade lower in the weeks before ECB rate cuts

          Evidence that significant changes in the ECB policy stance can drive domestic portfolio flows can be seen in the changes to domestic portfolio allocations as the ECB cut the deposit rate to negative levels in 2014 and prepared the market for the start of QE purchases. Domestic flows in Eurozone bonds turned sharply negative as investors fled abroad seeking higher yields. Substantial domestic fixed income outflows were featured throughout the period when the ECB was conducting QE and were partly responsible for suppressing the Euro’s value. It was only when the ECB signaled the end of QE was near that the trend in domestic fixed income outflows turned. With yields now substantially more negative than when the ECB first cut the deposit rate negative and the prospect of substantial QE purchases ahead, we anticipate Eurozone domestic investor fixed income flows will turn sharply negative again.
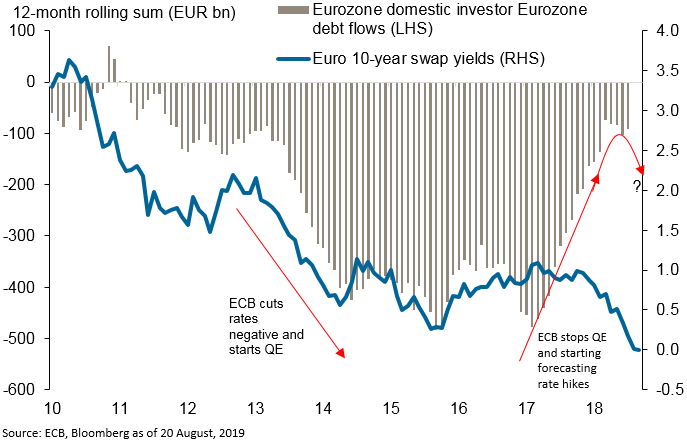
          EURUSD has tended to trade lower in the weeks before ECB rate cuts

          Beyond the September meeting, the outlook for the Euro is likely to become more nuanced as the market will need to weigh the increasingly prevalent smoke signals of German fiscal easing (likely Euro positive), a likely twitter storm from President Trump arguing that the Euro is being unfairly devalued, a global trade outlook that is likely to remain challenging, and easing by other central banks. It may be that once ECB easing has been delivered, the value of the Euro could stabilise or even bounce. However, we believe in the short-term it will be the prospect of sub-par growth and significantly more negative rates that will likely drive capital flows from Eurozone markets keeping the Euro under pressure over the next few weeks.

          • Monetary Policy
          • Central Banks
          • Eurozone

          RELATED ARTICLES

          Emerging markets and the negative yield conundrum for fixed income investors

          Record low bond yields pose a major problem for fixed income investors. We explore why taking active FX risk can be a solution for investors.

          Read more

          Negative rates – how low can you go?

          It seems the global financial system has gone crazy as rates continue to fall further negative. We review why and the impacts it has on the market.

          Read more

          The ECB's strategy review: Actions speak louder than words

          With the ECB quickly running out of tools and inflation still some way from their current target, the market will be keen to hear what comes next.

          Read more
          J.P. Morgan Asset Management

          • Investment stewardship
          • About us
          • Contact us
          • Privacy policy
          • Cookie policy
          • Sitemap
          • Accessibility
          J.P. Morgan

          • J.P. Morgan
          • JPMorgan Chase
          • Chase

          READ IMPORTANT LEGAL INFORMATION. Legal Disclaimer >

          The value of investments may go down as well as up and investors may not get back the full amount invested.

          Copyright 2026 JPMorgan Chase & Co. All rights reserved.