


Week in review
- China NBS Manufacturing PMI increased to 50.1 in September
- U.S. core PCE increased 0.2% MoM in August
- The Reserve Bank of Australia increased the interest rate by 25bps to 4.60%
Week ahead
- U.S. FOMC minutes
- Japan September consumer confidence
- U.S. ADP Weekly employment change
Thought of the week
Global bond yields pushed higher across major developed and Asian markets as resilient growth, sticky inflation, heavier issuance, and fiscal concerns pressured fixed income. Higher long-end yields can tighten financial conditions by lifting discount rates, weighing on duration-sensitive portfolios, and raising the hurdle rate for capital allocation. The selloff has also become more global in character: longer-dated government yields have reached multi-year or record levels in several markets, while policy expectations have shifted more hawkish as central banks respond to inflation risks tied partly to energy prices and supply pressures. Elevated yields may eventually attract demand from liability-driven investors and income-focused allocators. Investors should remain attentive to duration exposure, fiscal risk premia, and regional policy divergence, while recognizing that higher starting yields can improve forward-looking return potential if inflation and issuance pressures begin to stabilize.
10-year government bond yields
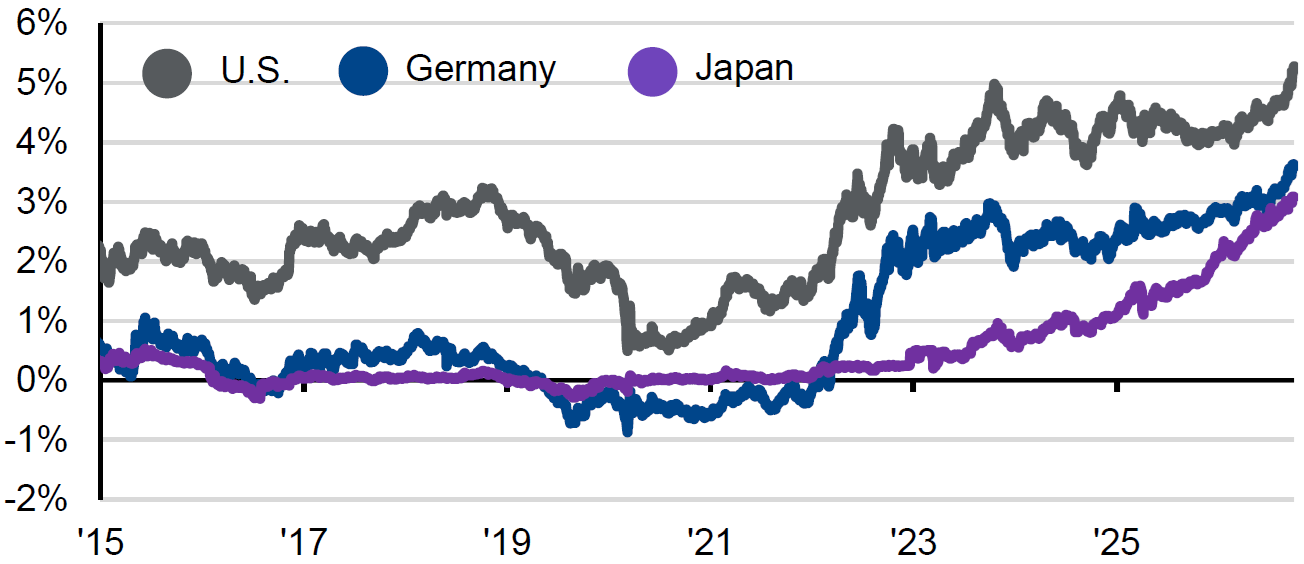
Source: FactSet, Tullett Prebon, J.P. Morgan Asset Management. Past performance is not a reliable indicator of current and future results. Positive yield does not imply positive return. Data reflect most recently available as of 30/09/2026.
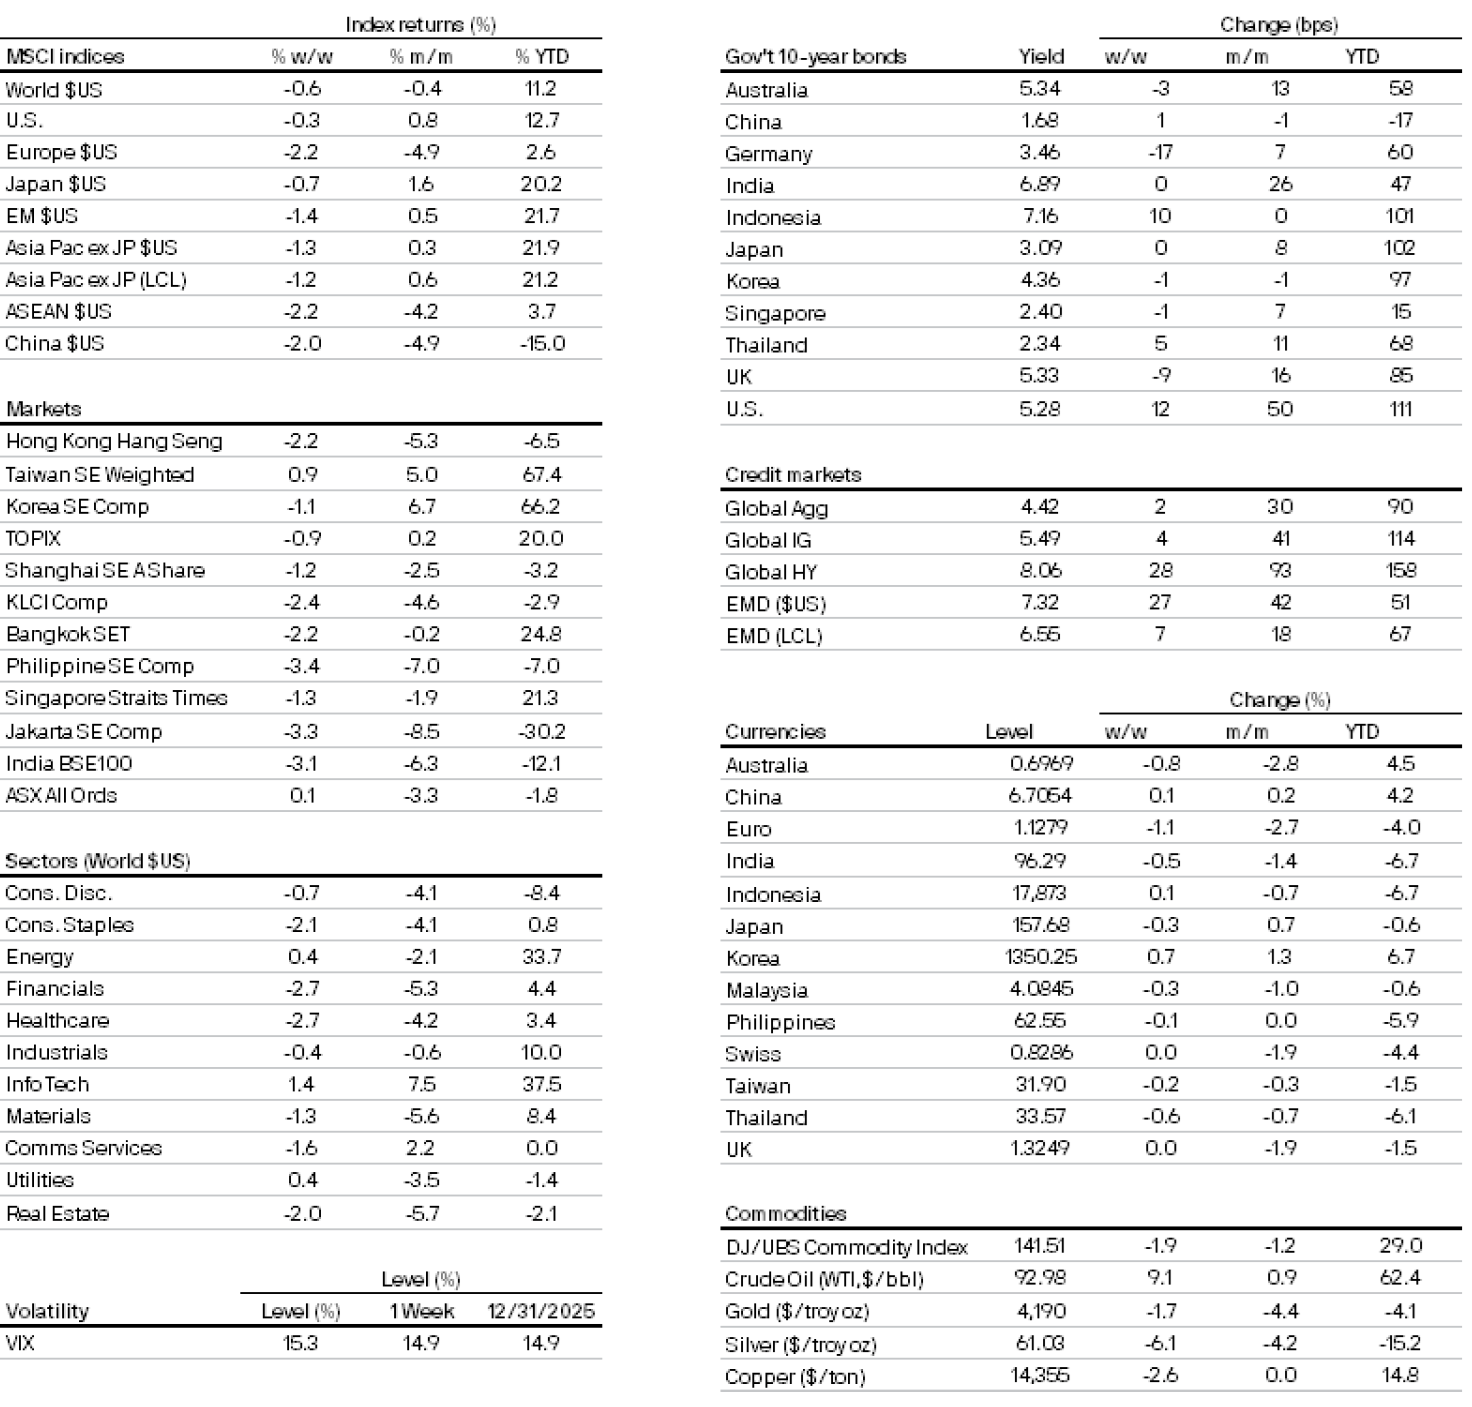
Market data
300a4900-f9d9-11e8-839f-fe2ee17e7f12
All returns in local currency unless stated otherwise.
Currencies’ return are based on foreign currencies per U.S. dollar. An appreciation of the foreign currency against the U.S. dollar would be positive and a depreciation of the foreign currency against the U.S. dollar would be negative.