JPAM_logo
  • My collections
    View saved content and presentation slides
  • Logout
  • Funds

      Fund Listing

      • All Funds
      • Fund Explorer
      • Fund Distribution
      • Fund Documents

      Capabilities

      • Equities
      • Fixed Income
      • Multi-asset
      • ETF Investing
      • Alternatives
      • Active research

      Featured Funds

      • Equity High Income Strategies
      • China Equity High Income Fund
      • Asia Equity High Income Fund
      • Global Equity High Income Fund
      • Fixed Income Solutions
    • Insights

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Weekly Market Recap

          Start each week with J.P. Morgan Asset Management’s one-page snapshot of top headlines, market performance, chart of the week and more.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Multimedia

          Interviews with Fund Managers and Investment Strategists bring you insights on global market trends and investment news.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        Portfolio Insights

        • Portfolio Insights Overview
        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Alternative Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        ETF Insights

        • ETF Insights overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

      • Investment Ideas
          • All Investment Ideas
          • What's new
          • Retirement and long-term investing
          • Sustainable investing
          • ETF knowledge
        • Resources
            • All Resources
            • Announcements
            • Forms & Literature
            • Investment Glossary
            • Library
            • Insights App
            • WhatsApp Communication
          • About Us
              • About us
              • Awards
              • Diversity, Opportunity and Inclusion
              • Our Leadership Team
              • Spectrum: Our Investment Platform
              • Our Commitment to Research
            • Partner With Us
            • Language
              • English
              • 中文/ Chinese
              • My collections
                View saved content and presentation slides
              • Logout
            • Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            On the Minds of Investors

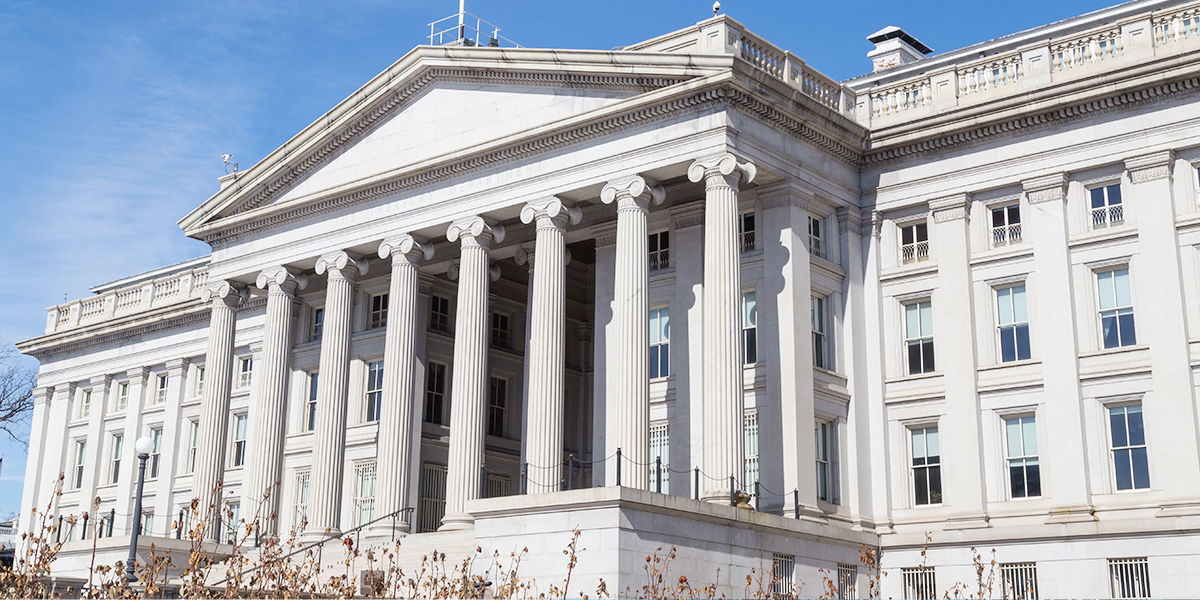
            The U.S. Supreme Court rules against reciprocal tariffs

            TH
            Tai Hui

            Chief Market Strategist, Asia Pacific
            Published: 23/02/2026
            We expect the latest Supreme Court ruling to help limit the overall impact from the administration’s tariff policy, despite medium-term uncertainty from other forms of tariffs with a more solid legal basis.

            What happened?

            In a 6–3 decision, the U.S. Supreme Court (SCOTUS) ruled that U.S. President Trump exceeded his authority by using the federal emergency powers law (IEEPA) to impose “reciprocal” tariffs globally, as well as targeted import taxes intended to address fentanyl trafficking. The tariffs on steel, aluminum, and automobiles were put in place under Section 232 of the Trade Act of 1962, and tariffs on Chinese electric vehicles, solar power panels and battery under Section 301 of the Trade Act of 1974 therefore are not directly affected.

            What has been the administration’s reaction?

            U.S. President Trump was unsurprisingly critical of the Supreme Court’s decision. He then imposed a 15% global tariff, effective on February 24, implemented under Section 122 of the Trade Act of 1974. This allows the administration to raise tariffs for 150 days due to trade imbalances, while congressional approval is required for any extension. According to the White House, some goods needed by the U.S. economy will be exempt, including critical minerals, agricultural products, pharmaceuticals, certain electronics (e.g., semiconductors) and automobiles. USMCA-compliant goods from Canada and Mexico will also be exempt.

            There are also other legislations the president could deploy that have more solid legal foundation—for example, the Section 232 and 301 tariffs mentioned above. However, these tariffs require lengthy investigations and are likely to be more narrowly based on specific products or markets.

            U.S. President Trump has already directed the Office of the U.S. Trade Representative to start a Section 301 investigation. U.S. Trade Representative Greer issued a statement noting that the investigation would cover “most major trading partners” and address concerns “such as industrial excess capacity, forced labor, pharmaceutical pricing practices, discrimination against U.S. technology companies and digital goods and services, digital services taxes…” China and the EU appear most exposed to these investigations.

            While the threat of tariffs remains, we see the latest court ruling as likely to limit the overall scope of tariffs going forward. Moreover, the upcoming midterm elections and voters’ focus on the cost of living should persuade the administration to be more cautious about broad tariffs that could raise prices.

            The ruling that IEEPA tariffs are illegal also blunts one of the president’s preferred foreign policy tools. U.S. President Trump has threatened to impose tariffs not just on issues of trade imbalance but also in other areas of foreign policy, although many of these threats were not implemented.

            Other questions to be answered

            SCOTUS did not clarify whether importers are entitled to refunds, leaving that issue to a lower court to resolve. If refunds are fully granted, they could total up to USD 170billion—over half the revenue generated by U.S. President Trump’s tariffs. However, significant uncertainty remains: only companies directly involved in the litigation may receive refunds. Otherwise, importers will need to file individual lawsuits with the Court of International Trade to claim reimbursement. Some companies, especially small and medium enterprises, may be in a disadvantaged position due to high litigation costs relative to the reimbursement amount

            There are also questions about trade deals with partners that have been struck in recent months, especially those that have not been ratified by their parliaments or are still under negotiation. Overall, we expect these governments to maintain dialogue given the prospects of other tariffs that could impact their exports, but the overall pace of negotiation could slowdown depending on the Trump administration’s next steps.

            Market implications

            The U.S. equity market reaction was fairly muted on Friday after the court ruling was announced. This is largely because of the uncertainties from the administration’s next steps and the potential refund process. The 10-year U.S. Treasury yield rose about 3 basis points (bps) after the announcement. This could be due to the market’s focus on lost tariff revenue adding to the federal government deficit. The short end of the yield curve also rose. The futures market on the Federal Reserve policy rate has not changed much either, despite very weak advance 4Q gross domestic product (GDP) data. Although the end of reciprocal tariffs could intuitively help reduce inflation, other tariffs could still introduce uncertainty.

            Overall, we expect the latest Supreme Court ruling to help limit the overall impact from the administration’s tariff policy, despite medium-term uncertainty from other forms of tariffs with a more solid legal basis. This should contain inflation in the U.S. at the margin, while tax rebates could provide a temporary boost to consumption in the near term. Margin compression for the corporate sector could be more concentrated in importers that are affected by Section 301 or Section 232 investigations and subsequent tariff implementation. There are sectors where the administration has shown more willingness to be lenient with tariffs, such as critical minerals and energy, foodstuffs, pharmaceuticals and semiconductors. In terms of trade partners, the end of IEEPA tariffs and the introduction of Section 122 tariff would create some winners and losers, at least temporarily. Brazil, China, and India would have seen the largest reduction in trade weighted tariff rates against the U.S., while the EU, Singapore, and the UK would have a modest increase. However, this could all change depending on the incoming Section 301 investigation as mentioned by the U.S. Trade Representative mentioned above, so market reaction may be limited and temporary. 


            b270c94f-0185-11f1-8070-0397328f61d0
            • Economy
            • Equities
            • Markets
            • Tariffs
            J.P. Morgan Asset Management

            • Terms of Use
            • Privacy Statement
            • Cookies Policy
            • Investment Stewardship
            • Fund Notes
            • Offering Document(s)
            • Forms & Literature
            • Complaint Resolution
            • Guide to Using This Website
            • Sitemap

            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Important: This area of the website is intended only for distributors of JPMorgan Funds (Asia) Limited. Information is not intended for retail or public distribution. By using this information, you confirm that you accept the Terms of Use as set out in https://am.jpmorgan.com/hk/.

            Investment involves risk. Past performance is not indicative of future performance. In particular, funds which are invested in emerging markets and smaller companies may involve a higher degree of risk and are usually more sensitive to price movements. Investors should carefully read and consider the fund offering document(s), which contain details on investment objectives, risk factors, charges and expenses of the fund, before making any investment decisions. Information in this website does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service, nor a distribution of information for any such purpose. Informational sources are considered reliable but you should conduct your own verification of information contained herein. The above information has not been reviewed by the SFC, issued by JPMorgan Funds (Asia) Limited.

            Apple, the Apple logo, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. App Store is a service mark of Apple Inc.

            Copyright 2026 JPMorgan Funds (Asia) Limited. All rights reserved.