JPAM_logo
  • My collections
    View saved content and presentation slides
  • Logout
  • Funds

      Fund Listing

      • All Funds
      • Fund Explorer
      • Fund Distribution
      • Fund Documents

      Capabilities

      • Equities
      • Fixed Income
      • Multi-asset
      • ETF Investing
      • Alternatives
      • Active research

      Featured Funds

      • Equity High Income Strategies
      • China Equity High Income Fund
      • Asia Equity High Income Fund
      • Global Equity High Income Fund
      • Fixed Income Solutions
    • Insights

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Weekly Market Recap

          Start each week with J.P. Morgan Asset Management’s one-page snapshot of top headlines, market performance, chart of the week and more.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Multimedia

          Interviews with Fund Managers and Investment Strategists bring you insights on global market trends and investment news.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        Portfolio Insights

        • Portfolio Insights Overview
        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Alternative Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        ETF Insights

        • ETF Insights overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

      • Investment Ideas
          • All Investment Ideas
          • What's new
          • Retirement and long-term investing
          • Sustainable investing
          • ETF knowledge
        • Resources
            • All Resources
            • Announcements
            • Forms & Literature
            • Investment Glossary
            • Library
            • Insights App
            • WhatsApp Communication
          • About Us
              • About us
              • Awards
              • Diversity, Opportunity and Inclusion
              • Our Leadership Team
              • Spectrum: Our Investment Platform
              • Our Commitment to Research
            • Partner With Us
            • Language
              • English
              • 中文/ Chinese
              • My collections
                View saved content and presentation slides
              • Logout
            • Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            On the Minds of Investors

            Inflation spillovers from the Middle East

            IH
            Ian Hui

            Global Market Strategist
            Published: 12/05/2026
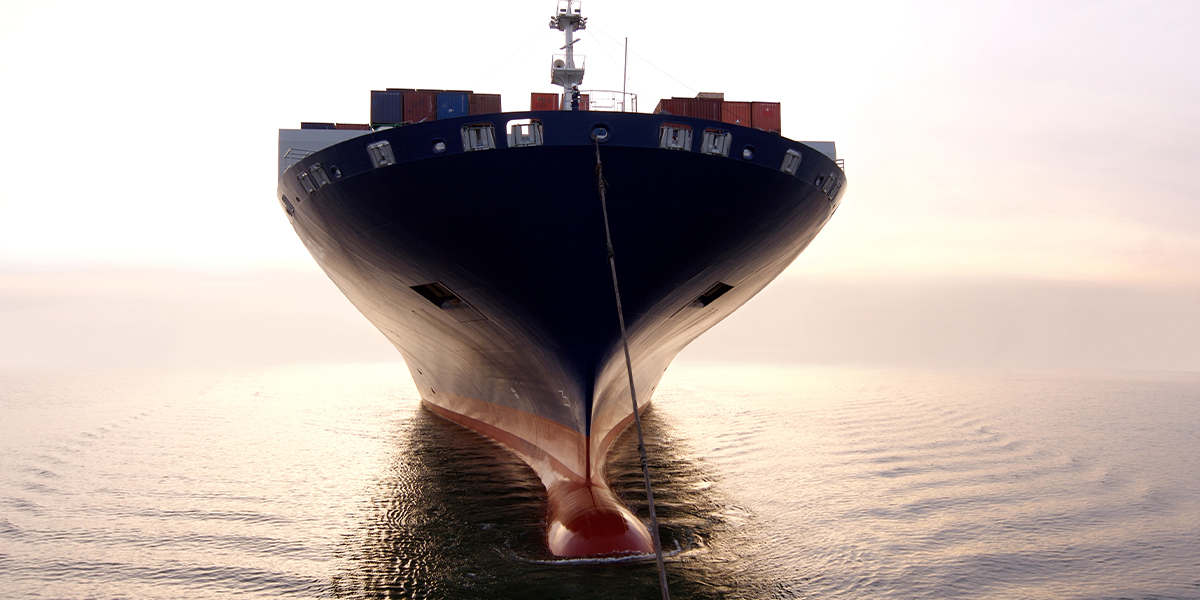
            The Strait of Hormuz is not only a corridor for energy, but also for bulk commodities and chemical cargoes that support manufacturing and agriculture.

            In Brief

            • The U.S.–Iran conflict risks becoming more than an oil story for Asia; disruption and uncertainty around the Strait of Hormuz can create broader shocks.
            • A key spillover is from energy prices and commodities into other areas of the global economy, raising prices, and potentially squeezing consumers and growth.
            • Effects might be mitigated by policy buffers, but this could be uneven. They are also likely to manifest with a lag; investors should avoid complacency even if the most recent data shows little issue.

            The outbreak of the U.S.–Iran conflict has significantly disrupted the flow of goods and energy from the Middle East. Most market attention is focused on the impact on oil and natural gas markets, as we have written about previously, and Asia is likely to be disproportionately impacted. While oil and the energy disruption might be the bigger headline when it comes to the inflation and growth outlook for Asia and the world, there will be consequences across many sectors of the economy as disrupted shipping through the Strait of Hormuz becomes a broader supply-and-logistics shock that pressures inflation higher. More persistent second-round effects and spillovers will begin to form in the background that will impact Asia.

            We should keep in mind that the region is a transit hub. The Strait of Hormuz is not only a corridor for energy, but also for bulk commodities and chemical cargoes that support manufacturing and agriculture. Even without a complete shutdown, sporadic interruptions and risk aversion can create congestion, reduce effective shipping capacity, and lift shipping costs.

            It is not just oil we have to worry about

            There is a risk that an oil shock turns into a food shock. Close to 20% of global fertilizer supply originates from the region, and prices for important fertilizer components like urea have surged. The region is also critical for sulfur, accounting for around half of global exports, which matters because sulfur is an important input in fertilizer production. Similar to what happened in the oil market in 2022, the outbreak of the Russia–Ukraine conflict offers a useful historical example. Ukraine was a significant producer of fertilizer, and the fighting saw prices soar. This was followed by food inflation rising by double digits several months later, as seen in Exhibit 1 below. A similar response is likely in our view, with food production facing a double dose of trouble in the form of higher fuel costs not only for transportation but also for agricultural equipment use. 

            Food inflation tends to respond with a lag. Much of what people eat today was grown months ago, so the bigger impact from higher urea prices is likely to show up in future harvests. A fertilizer shortage or sustained price spike can reduce yields in the next crop cycle, and farmers may pass on higher costs both in anticipation of further shortages and when the next harvest reaches the market. That lag can make early inflation data look benign and can tempt markets to assume the risk is low.

            Even if shipping conditions improve, normalization may take time: reopening the Strait of Hormuz would not instantly restore trade after production disruptions and shipping dislocation. If natural gas infrastructure has been damaged, that also points to more persistent supply constraints and elevated fertilizer prices. 

            Issues spiral beyond food prices into supply chains

            The Strait’s importance extends beyond energy and agriculture. The region is also meaningful for petrochemicals and chemical precursors used throughout manufacturing supply chains; disruptions there can raise input costs for packaging, textiles, consumer goods, and industrial components. Metals can be exposed as well, not only through higher energy costs in energy-intensive processing but also through shipping disruptions for raw materials; around 10% of global aluminum production passes through the region. For high-tech manufacturing, even niche materials can matter if supply is concentrated and inventories are limited. Around one-third of global helium production, which is needed for chip fabrication, goes through the chokepoint. The risk is not only price increases but also production scheduling problems when a single input becomes scarce.

            If inflation accelerates, a key question is whether consumers can draw down excess savings or reduce spending without triggering a sharper slowdown. In some markets, like China and South Korea, savings buffers still exist; in others, like the Philippines, savings buffers have been decreasing, and higher essentials inflation translates quickly into weaker non-essential spending. Because items like food purchases are non-discretionary and frequent, a rise in staples can feel more severe than an equivalent rise in fuel. It can erode purchasing power and sentiment, which will eventually cut into growth.

            Many Asian governments have responded with subsidies, price caps, tax cuts, targeted transfers, or administrative measures. Those tools can soften the short-term blow to consumers and help avoid a collapse in discretionary spending, but they come with trade-offs. If fiscal headroom is limited, more spending on offsets and subsidies can crowd out other priorities, including public investment, and can complicate the inflation fight if it sustains demand while supply remains constrained. Singapore, South Korea, and Taiwan are better positioned to deploy supplementary budgets due to strong corporate tax revenues from the tech and artificial intelligence (AI) boom, while markets like India, Malaysia, the Philippines, and Thailand face more limited fiscal space.

            Investment implications

            Even if the initial market reaction looks contained, the conflict’s inflationary impulse may still be working its way through the system with a lag. Disruptions to shipping lanes, fertilizer and chemical inputs, and energy-linked supply chains can translate into higher delivered costs over the coming months, particularly for food and manufactured goods, and these pressures can persist even after headlines fade if trade flows and production take time to normalize.

            We may see a split in performance along two key factors in Asia: markets focused on AI versus non-AI and energy importers versus exporters. Those markets riding the AI wave and less reliant on energy imports have a more positive outlook. The potential for higher inflation means higher rates are also more likely, which could mitigate the benefit of fixed income. It will pay to be selective in this space and to keep in mind which markets may see outsized reactions from their central banks.

            For investors, the key risk is complacency: second-round effects can arrive later and prove stickier than the initial move in oil, with knock-on implications for Asian growth, corporate margins, and policy settings. Until there is clearer evidence that logistics, input prices, and inflation data are stabilizing, it would be sensible for investors to remain cautious and to reduce risk exposure by increasing allocations to fixed income and defensive sectors.


            c1818e82-4d0e-11f1-b6c8-b951180a96cf
            • Commodities
            • Economy
            • Inflation
            • Markets
            • Oil
            • Transport
            J.P. Morgan Asset Management

            • Terms of Use
            • Privacy Statement
            • Cookies Policy
            • Investment Stewardship
            • Fund Notes
            • Offering Document(s)
            • Forms & Literature
            • Complaint Resolution
            • Guide to Using This Website
            • Sitemap

            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Important: This area of the website is intended only for distributors of JPMorgan Funds (Asia) Limited. Information is not intended for retail or public distribution. By using this information, you confirm that you accept the Terms of Use as set out in https://am.jpmorgan.com/hk/.

            Investment involves risk. Past performance is not indicative of future performance. In particular, funds which are invested in emerging markets and smaller companies may involve a higher degree of risk and are usually more sensitive to price movements. Investors should carefully read and consider the fund offering document(s), which contain details on investment objectives, risk factors, charges and expenses of the fund, before making any investment decisions. Information in this website does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service, nor a distribution of information for any such purpose. Informational sources are considered reliable but you should conduct your own verification of information contained herein. The above information has not been reviewed by the SFC, issued by JPMorgan Funds (Asia) Limited.

            Apple, the Apple logo, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. App Store is a service mark of Apple Inc.

            Copyright 2026 JPMorgan Funds (Asia) Limited. All rights reserved.