JPAM_logo
  • My collections
    View saved content and presentation slides
  • Logout
  • Funds

      Fund Listing

      • All Funds
      • Fund Explorer
      • Fund Distribution
      • Fund Documents

      Capabilities

      • Equities
      • Fixed Income
      • Multi-asset
      • ETF Investing
      • Alternatives
      • Active research

      Featured Funds

      • Equity High Income Strategies
      • China Equity High Income Fund
      • Asia Equity High Income Fund
      • Global Equity High Income Fund
      • Fixed Income Solutions
    • Insights

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Weekly Market Recap

          Start each week with J.P. Morgan Asset Management’s one-page snapshot of top headlines, market performance, chart of the week and more.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Multimedia

          Interviews with Fund Managers and Investment Strategists bring you insights on global market trends and investment news.

        • Guide to Alternatives

          Objective insights on alternatives industry trends, with charts and data across private equity, private credit, real estate, infrastructure and hedge funds.

        Portfolio Insights

        • Portfolio Insights Overview
        • Fixed Income

          We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Alternative Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        ETF Insights

        • ETF Insights overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

      • Investment Ideas
          • All Investment Ideas
          • What's new
          • Retirement and long-term investing
          • Sustainable investing
          • ETF knowledge
        • Resources
            • All Resources
            • Announcements
            • Forms & Literature
            • Investment Glossary
            • Library
            • Insights App
            • WhatsApp Communication
          • About Us

              About us

              Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

              • About us
              • Awards
              • Diversity, Opportunity and Inclusion
              • Our Leadership Team
              • Spectrum: Our Investment Platform
              • Our Commitment to Research
            • Partner With Us
            • Language
              • English
              • 中文/ Chinese
              • My collections
                View saved content and presentation slides
              • Logout
            • Login
            Log in
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            On the Minds of Investors

            Implications of U.S.-Iran agreement to reopen the Strait of Hormuz

            TH
            Tai Hui

            Chief Market Strategist, Asia Pacific

            Published: 15/06/2026
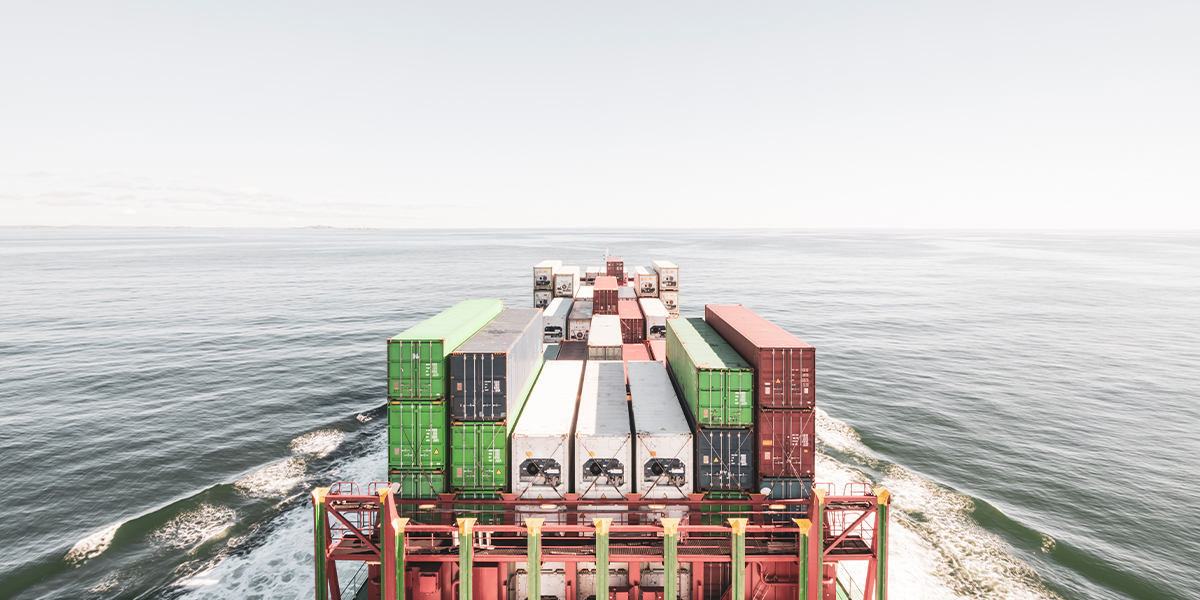
            Reopening the Strait is clearly a positive for the global economy, as disruptions in energy and petrochemical supplies can introduce stagflation risks.

            In Brief

            • An agreement to reopen the Strait of Hormuz reopening would reduce a major source of global economic risk.
            • Supply normalization may take weeks, if not months, with insurance costs, damaged infrastructure, and reserve rebuilding keeping energy prices elevated.
            • Investors may see a risk-on rotation into lagging sectors, Asian markets, and longer-duration bonds, while energy security and defense spending remain longer-term themes.

            What we know so far

            U.S. President Trump announced that a deal has been reached to extend the ceasefire and reopen the Strait of Hormuz. This has been confirmed by Iran’s deputy foreign minister, as well as by Pakistan and Qatar, the mediators in these negotiations. An official signing ceremony is expected to take place this Friday in Switzerland. While U.S. President Trump has announced similar deals in the past, confirmation from Iran and the mediators increases the likelihood that this agreement will proceed.

            Details of the agreement remain limited at this point, and the situation can still change even after the memorandum of understanding (MOU) is signed. This is unlikely to be the end of negotiations, as durable consensus on Iran’s nuclear program—and easing tensions among the Gulf countries—would be difficult to achieve sustainably. Moreover, there have been sporadic military actions from both sides since the initial ceasefire was reached in early April. The conflict between Israel and Hezbollah in Lebanon also remains a wildcard for this peace process. Nonetheless, the agreement to reopen the Strait of Hormuz would be the most relevant part for investors. 

            What does this mean for the global economy?

            Reopening the Strait is clearly a positive for the global economy, as disruptions in energy and petrochemical supplies can introduce stagflation risks. While markets may be quick to price in recovery, a return to normalization would take time.

            The first hurdle will be convincing insurers and shipping companies that it is safe for vessels to transit the Strait of Hormuz. Even with the reopening, insurance premia for ships passing through the Strait could remain elevated, increasing the cost of oil, gas, and other products from the region.

            It will also take time for energy production, refining, and logistics capacity to return to pre-conflict levels. A reasonable estimate for normalization is weeks, if not two to three months. This does not account for production facilities that may have been damaged by Iranian attacks; some could take two to three years to repair and bring back online.

            Economies and governments may also seek to replenish inventories and strategic reserves in case the situation in the Middle East deteriorates again. Overall, this suggests energy prices are unlikely to fall back to pre-conflict levels in the near term.

            For central banks, reopening the Strait should provide some relief, as the initial inflation shock from energy prices may not yet have fully filtered through to inflation expectations. This would allow the U.S. Federal Reserve to hold rates this week and continue monitoring. The European Central Bank (ECB) raised policy rates last week, as it was already on a tightening path ahead of the conflict due to building inflationary pressures. If energy prices remain calm on a sustained basis, this should give the ECB more flexibility to adjust policy later in the year.

            What does this mean for investors?

            Unsurprisingly, the immediate market reaction is a risk-on rally. This could prompt further rotation, benefiting recent laggards. Non-tech sectors may play catch-up if a major source of economic uncertainty is receding. Consumer-related companies, energy-intensive industries, and transportation could benefit.

            In Asia, ASEAN and India have seen performance hindered by energy shortages and inflation pressures. An eventual resumption of energy imports should help support these markets. This also opens a window for investors to diversify away from technology, which has already performed well year-to-date. This type of rotation calls for active management in equity allocation.

            The prospect of peaking policy rates could also support adding duration in selected government bond markets, as well as a modest tightening of credit spreads. Improved risk appetite could also renew pressure on the U.S. dollar.

            Beyond the immediate market reaction to a deal and the reopening of the Strait, investors may have questions about the longer-term implications of this conflict.

            First, energy security is once again at the top of the agenda. The Russia–Ukraine conflict forced European governments to reassess energy dependence; the Middle East conflict has had an even more significant impact on many Asian economies. Where oil and gas are imported from should become a policy discussion for all governments. This also raises questions about energy sources and the role of non-fossil fuels, including renewables and nuclear power.

            Second, the U.S.–Iran conflict suggests that the scale of defense spending is not the only factor influencing outcomes, but also how that money is spent. High-volume, low-cost weapons—such as drones—gave Iran an advantage in controlling the Strait of Hormuz and threatening other Gulf states to gain leverage. The economics of defense is likely to evolve in the coming years, potentially driving rotation within the defense industry.


            e25d4ced-656a-11f1-ae84-d7bd183c4562

            About the Author

            Latest from the Author

            Monthly Views and Perspectives: Reality bites for governments and AI investors
            November 01, 2026 Tai Hui
            Monthly Views and Perspectives: Higher rates and AI scrutiny calls for portfolio diversification
            October 01, 2026 Tai Hui
            The problems with doing too much, or too little
            September 02, 2026
            Mid-term elections: How does a change in Congress change U.S. policies?
            June 11, 2026 Tai Hui
            How could the Middle East conflict evolve?
            June 11, 2026 Tai Hui
            • Commodities
            • Economy
            • Energy
            • Equities
            • Fixed Income
            • Geopolitics
            • Interest Rates
            • Markets
            • Monetary Policy
            • Oil
            J.P. Morgan Asset Management

            • Terms of Use
            • Privacy Statement
            • Cookies Policy
            • Investment Stewardship
            • Fund Notes
            • Offering Document(s)
            • Forms & Literature
            • Complaint Resolution
            • Guide to Using This Website
            • Sitemap

            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            Important: This area of the website is intended only for distributors of JPMorgan Funds (Asia) Limited. Information is not intended for retail or public distribution. By using this information, you confirm that you accept the Terms of Use as set out in https://am.jpmorgan.com/hk/.

            Investment involves risk. Past performance is not indicative of future performance. In particular, funds which are invested in emerging markets and smaller companies may involve a higher degree of risk and are usually more sensitive to price movements. Investors should carefully read and consider the fund offering document(s), which contain details on investment objectives, risk factors, charges and expenses of the fund, before making any investment decisions. Information in this website does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service, nor a distribution of information for any such purpose. Informational sources are considered reliable but you should conduct your own verification of information contained herein. The above information has not been reviewed by the SFC, issued by JPMorgan Funds (Asia) Limited.

            Apple, the Apple logo, iPad and iPhone are trademarks of Apple Inc., registered in the US and other countries. App Store is a service mark of Apple Inc.

            Copyright 2026 JPMorgan Funds (Asia) Limited. All rights reserved.