logo
  • Funds
      Contact Us

      Fund Listing

      • Fund Explorer
      • Fund Managers
      • Fund Documents
      • How to Invest

      Capabilities

      • All Funds
      • Equities
      • Fixed Income
      • Multi-asset
      • ETF Investing
      • Investment Research

      Featured Funds

      • JPMorgan Singapore & Asia Equity Income Fund
      • JPMorgan Income Fund
      • Equity Funds
      • Equity Premium Income Active ETFs
      • JPMorgan Flexible Credit Fund
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Weekly Market Recap

          Start to simplify the complex with our Weekly Market Recap – a timely summary of recent market movements, economic developments and a look at what's ahead.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Multimedia

          Interviews with Fund Managers and Investment Strategists bring you insights on global market trends and investment news.

        • Solving for Income

          Solving for Income uses slides from the Guide to the Markets – Asia to examine the role of income and why it should remain a key investment objective.

        • Solving for Fixed Income

          Slides from the Guide to the Markets – Asia examine the role of fixed income and why it should remain a key investment objective.

        • U.S. Policy Pulse Hub

          Insights to guide investors through the opportunities and risks arising from policy from the new administration.

        Portfolio Insights

        • Portfolio Insights Overview
        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Global Equity Views

          Massive AI spending is driving exceptional profit growth at reasonable valuations. We see long-term value in “AI losers” and defensive stocks.

        • Alternative Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        ETF Insights

        • ETF Insights overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        Retirement Insights

        • Retirement Resources

          To achieve our desired retirement, it is important to anticipate the possible challenges that retirees could face and be better financially prepared.

        • Guide to Retirement

          Our Guide to Retirement, updated annually, provides an effective framework for retirement planning conversations with clients.

      • Investment Ideas
          Contact Us
          • What's new
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Announcements
            • Forms & Literature
            • About Mutual Funds
            • Investment Glossary
            • Insights App
          • About Us
              Contact Us

              About us

              Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Our Leadership Team
            • Contact Us
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            1. Seeking long-term growth opportunities among the old & new in ASEAN

            Seeking long-term growth opportunities among the old & new in ASEAN

            Aug 2022 (3-minute read)

            Is asean’s market less volatile?
            Where we see opportunities

            47-top-banner

            #ASEAN         #ASEANopportunities         #GrowthInvesting

            Key takeaways:

            • The Association of Southeast Asian Nations (ASEAN) could present compelling long-term growth opportunities1 after undergoing a healthy reset over the past decade.

            • The regional grouping of 10 nations is gaining momentum with continuing infrastructure development, reviving tourism, accelerating digital transformation, strengthening corporate governance, and as an alternative manufacturing base to other parts of Asia.

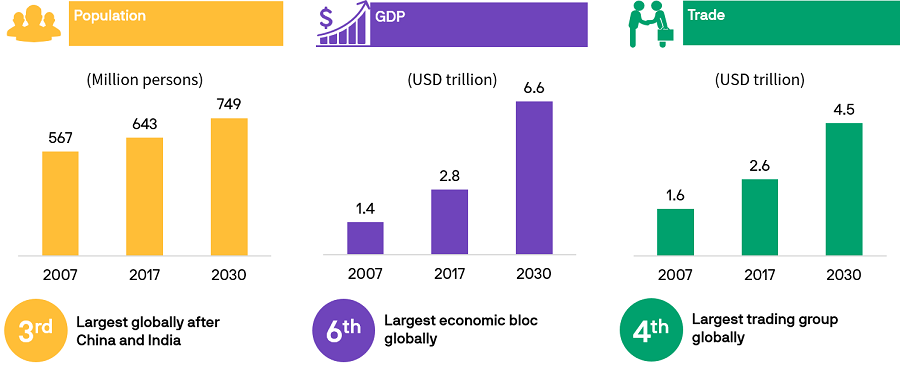
            With its proximity to China, ASEAN straddles between the familiar and alien for most investors. ASEAN is gaining momentum as the regional grouping comprises the world’s third largest population after China and India; is the sixth largest economy and the fourth biggest trading group, as illustrated below2.


            ASEAN is big … and only getting bigger2


            Provided to illustrate macro trends, not to be construed as research or investment advice. Data is not indicative of current or future results.

            We share our perspectives on how the ASEAN market could drive equity growth with its mix of old and new economies, and where we see medium- and long-term opportunities.

            Is the ASEAN market less volatile?

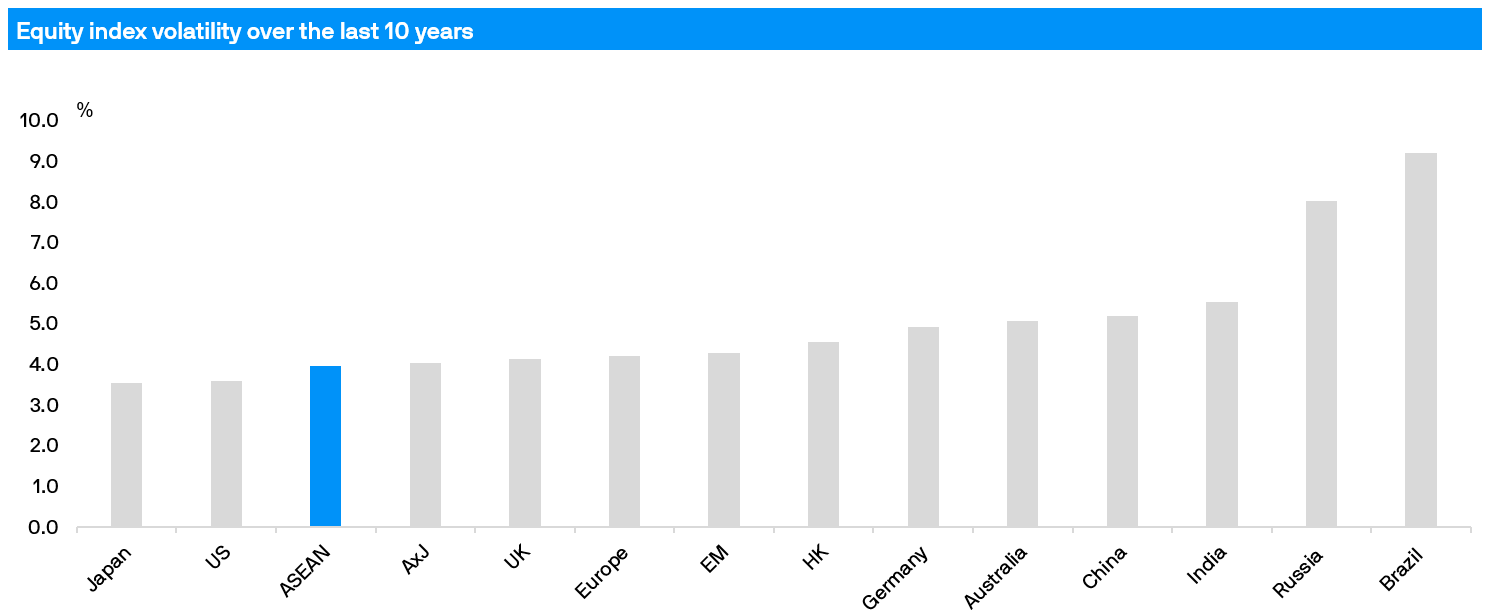
            As illustrated below, the ASEAN market is relatively less volatile than the investors generally believe, even though emerging-market stocks and bonds are generally considered risk assets because of historical political instabilities.


            ASEAN equity index is less volatile than Asia and Europe over the past decade3


            Source: J.P. Morgan Asset Management, MSCI, Data Stream. Data as of May 2022. Equity Indices shown are MSCI Country Indices. Volatility = 6 Month Rolling standard deviation of monthly returns (in USD). They are for illustrative purposes only and serve as an indication of what may occur. Indices do not include fees or operating expenses and are not available for actual investment. AxJ = Asia ex-Japan, EM= emerging markets.

            But ASEAN has undergone a healthy reset over the past 10 years with deleveraging and continuing infrastructure investment. Additionally, the region has presented equity opportunities1 with its expansion into new industries and acceleration of e-commerce, alongside a revival of traditional industries such as commodities, tourism and manufacturing.

            JPMorgan Funds - ASEAN Equity Fund

            Learn more

            Where we see medium- to long-term opportunities

            We believe accelerating vaccinations could bode well for the ASEAN market in 2022 compared with 2021.

            Vaccines continue to be available in Singapore and Malaysia. As of August 2022, 93% of the total population in Singapore4 and 84.1% in Malaysia5, respectively, have received at least two doses of vaccines. Thailand, the Phillipines and Vietnam are also lifting vaccination rates to help accelerate economic recovery and drive domestic consumption growth.

            Tourism is a major contributor to Southeast Asia’s economy. For example, Thailand’s tourism revenue accounted for 18.21%6 of its total economy in 2019. With the onset of the public health crisis, mobility restrictions have hindered economic recovery as inbound tourist numbers dropped to historic lows. Lately, vaccination progress in Southeast Asia has enabled the region to reopen borders and restart tourism, and to gradually resume economic activities.

            Even before the onset of the public health crisis, some businesses have relocated their factories from other parts of Asia to ASEAN to diversify their manufacturing base as well to mitigate rising labour costs. Businesses will likely continue to diversify, driven by rising inflation and transportation costs as well as pressure on profit margins.

            A digital-led healthy reset

            Digitalisation in the spotlight
            • ASEAN’s new internet users increased by 40 million in 2020, after adding 100 million from 2015 to 20197.
            • In recent years, numerous new e-commerce and financial services technology companies have emerged in ASEAN.
            • Penetration rate of e-commerce in ASEAN is just in the single digits, far below the 25% of China8.


            Financial deepening
            • Digital innovation has been leading the way in financial services in ASEAN. Traditionally, investors consider banking as defensive stocks and now banks may be seen as a long-term beneficiaries from digital transformation.
            • Digital techonologies are expected to unleash the growth potential in financial services as banks in ASEAN are actively accelerating their digital transformation including simplifying account opening process, enhancing experience and attracting new clients.


            Natural resources
            • Natural resource is a competitive advantage for ASEAN. For example, Indonesia holds the world’s largest nickel ore reserves, accounting for a quarter of global production9. And global demand for nickel ore in stainless steel and electric vehicle (EV) battery manufacturing is fast-growing.
            • Already, Indonesia has attracted investments from EV supply-chain manufacturers, and has lifted domestic production of nickel ore and restricted export.

            Conclusion
             

            ASEAN economies are straddling between the old and the new. Supported by the old economy, we see strong and sustainable growth in Southeast Asian equites in the next decade as the region’s quality corporates harness new technologies and undergo digital transformation.

            A bottom-up approach and top-down considerations are crucial when investing in emerging markets. Harnessing a dedicated team of five ASEAN investment professionals with an average of 17 years of industry experience10, J.P. Morgan Asset Management seeks optimal growth opportunities on ASEAN’s road to recovery.

            OUR GROWTH SOLUTIONS

            JPMorgan Funds - China A-Share Opportunities Fund

            Learn more

            JPMorgan Funds - Asia Growth Fund

            Learn more

            JPMorgan Funds - ASEAN Equity Fund

            Learn more

            Provided for information only based on market conditions as of date of publication, not to be construed as investment recommendation or advice. Forecasts, projections and other forward looking statements are based upon current beliefs and expectations, may or may not come to pass. They are for illustrative purposes only and serve as an indication of what may occur. Given the inherent uncertainties and risks associated with forecast, projections or other forward statements, actual events, results or performance may differ materially from those reflected or contemplated.

            Diversification does not guarantee investment return and does not eliminate the risk of loss. 

            1. For illustrative purposes only based on current market conditions, subject to change from time to time. Not all investments are suitable for all investors. Exact allocation of portfolio depends on each individual’s circumstance and market conditions.
            2. Source: UOB Economic-Treasury Research, Macrobond, Visual Capitalist. Data as of end-December 2020. Forecasts, projections and other forward looking statements are based upon current beliefs and expectations. They are for illustrative purposes only and serve as an indication of what may occur. Given the inherent uncertainties and risks associated with forecast, projections or other forward statements, actual events, results or performance may differ materially from those reflected or contemplated.
            4. Source: Ministry of Heath Singapore, data as of 01.08.2022.
            5. Source: Ministry of Health Malaysia, data as of 07.08.2022.
            6. Source: Ministry of Tourism and Sports(Thailand), Statista. Data as of May 2021.
            7. Source: “e-Conomy SEA 2020”, Google, Bain & Company, Temasek, 10.11.2020.
            8. Source: “ASEAN E-commerce: beyond the Pandemic”, Hong Kong Trade Development Council Research, 09.06.2021.
            9. Source: “Indonesia On Track To Dominate The Supply Of Nickel To Make Batteries”, Forbes, 02.06.2021.
            10. Source: J.P. Morgan Asset Management, data as of 30.06.2022.


            This advertisement or publication has not been reviewed by the Monetary Authority of Singapore. It does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service. Informational sources are considered reliable but you should conduct your own verification of information contained herein. Investment involves risk. Investments in funds are not deposits and are not considered as being comparable to deposits. Past performance is not indicative of future performance and investors may not get back the full or any part of the amount invested. Dividend distributions if any are not guaranteed and are made at the manager’s discretion. Fund’s net asset value may likely have high volatility due to its investment policies or portfolio management techniques. The value of the units in the scheme and the income accruing to the units, if any, may fall or rise. Funds which are invested in emerging markets, smaller companies and financial derivative instruments may also involve higher risks and are usually more sensitive to price movements. Any applicable currency hedging process may not give a precise hedge and there is no guarantee that any hedging will be successful. Investors in a currency hedged fund or share class may have exposure to currencies other than the currency of their fund or share class. Investors should make their own investigation or evaluation or seek independent advice prior to making any investment. Please refer to the Singapore Offering Documents (including the risk factors set out therein) and the relevant Product Highlights Sheet for details at https://am.jpmorgan.com/sg/en/asset-management/per/. To the extent permitted by applicable law, we may record telephone calls and monitor electronic communications to comply with our legal and regulatory obligations and internal policies. Personal data will be collected, stored and processed by J.P. Morgan Asset Management in accordance with https://am.jpmorgan.com/sg/en/asset-management/per/privacy-statement/. Issued by JPMorgan Asset Management (Singapore) Limited (Co. Reg. No. 197601586K). All rights reserved.


            OUR FOCUS FUNDS

            Equities

            • JPMorgan ASEAN Equity Fund
            • JPMorgan China A-Share Opportunities Fund
            • JPMorgan Emerging Markets Equity Fund
            • JPMorgan Emerging Markets Dividend Fund
            • JPMorgan Asia Growth Fund

            Asset Allocation

            • JPMorgan Global Income Fund
            • JPMorgan Asia Pacific Income Fund
            • JPMorgan Total Emerging Markets Income Fund
            • JPMorgan Global Macro Opportunities Funds

            Fixed Income

            • JPMorgan Income Fund
            • JPMorgan Global Bond Opportunities Fund
            See all funds

            RELATED ARTICLES

            What if … things keep getting more expensive?

            Inflation can diminish purchasing power. We explain why investing and staying invested can help manage the impact of inflation over the long run.

            Read more

            Securitisation: Then and now

            The securitisation market has regained much ground in the past decade.

            Read more

            What’s going on in global equities?

            We share the positive drivers for the global economy and how they could benefit equities in 2025.

            Read more

            Guide to ETFs: Rising flows, growth of active and the Asian connection

            Casting a spotlight on exchange-traded funds (ETFs) in Asia Pacific. The guide serves as a go to source for APAC ETF investors – from global trading best practices to tips on portfolio construction.

            Read more

            How ETFs and model portfolios are striking a pose

            We explore why model portfolios that include ETFs are gaining ground among investors.

            Read more
            lets-solve-it-logo

            For Fund or Institutional enquiries, please call or email us. You can also contact your financial advisor or your J.P.Morgan Representative.

            (65) 6882 1328

            singapore.investor.services@jpmorgan.com

            JPMorgan Asset Management

            • Terms of Use
            • Privacy Statement
            • Cookies Policy
            • Investment stewardship
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            The information contained herein is intended only for use by Singapore residents. By using this information, you are representing and warranting that you are either residing in Singapore or the applicable laws and regulations of your jurisdiction allow you to access the information, and you confirm that you accept the Terms of Use as set out in https://www.jpmorgan.com/sg/am/per/. Investment involves risk. Past performance is not indicative of future performance. In particular, funds which are invested in emerging markets and smaller companies may involve a higher degree of risk and are usually more sensitive to price movements. Investors should carefully read and consider the fund offering document(s), which contain details on investment objectives, risk factors, charges and expenses of the fund, before making any investment decisions. Information in this website does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service, nor a distribution of information for any such purpose. Informational sources are considered reliable but you should conduct your own verification of information contained herein. Issued by JPMorgan Asset Management (Singapore) Limited. This advertisement or publication has not been reviewed by the Monetary Authority of Singapore (“MAS”).


            JPMorgan Asset Management (Singapore) Ltd is regulated by the Monetary Authority of Singapore. (Co. Reg. No. 197601586K)