


Week in review
- U.S. ISM Services PMI fell from 55.4 in Aug to 54.9 in Sep
- India RBI raised the benchmark repo rate by 25 bps from 5.25% to 5.50%
- Japan household spending fell by 3.1% y/y in Aug
Week ahead
- China Sep CPI and PPI
- China Sep imports and exports
- Australia Sep employment data
Thought of the week
U.S. equities continued to advance this week amidst elevated Treasury yields, with the 10-year yield reaching 5.35%, its highest level since 2002. While rising yields can weigh on equities through higher discount rates and opportunity cost of holding stocks, equities can still perform when higher yields reflect stronger growth and earnings expectations. Nonetheless, the recent resilience in U.S. equities has not been broad-based. While the S&P 500 reached another record high, the equal-weighted index remains around 5% below its August peak, suggesting the average stock has been more sensitive to higher rates. For investors, this divergence highlights the need to look beyond headline index performance and assess whether returns are being driven by broad market strength or a narrower set of rate-resilient stocks. As the economic backdrop evolves, shifting stock-bond dynamics reinforce the importance of diversification across both asset classes.
Correlations between stocks and bonds
12-month rolling correlation of U.S. equities and bond prices*
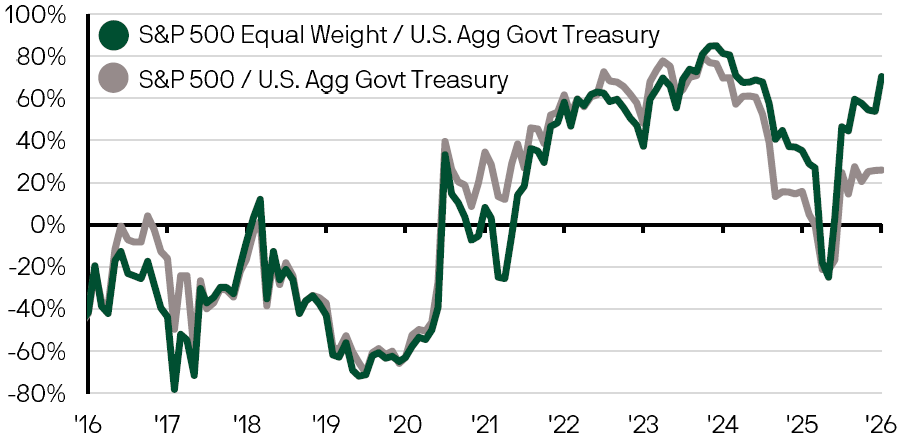
Source: Bloomberg, FactSet, S&P Global, J.P. Morgan Asset Management. *12-month rolling correlations between monthly returns in U.S. equity and treasury markets. Past performance is not a reliable indicator of current and future results. Data reflect most recently available as of 08/10/2026.
Market data
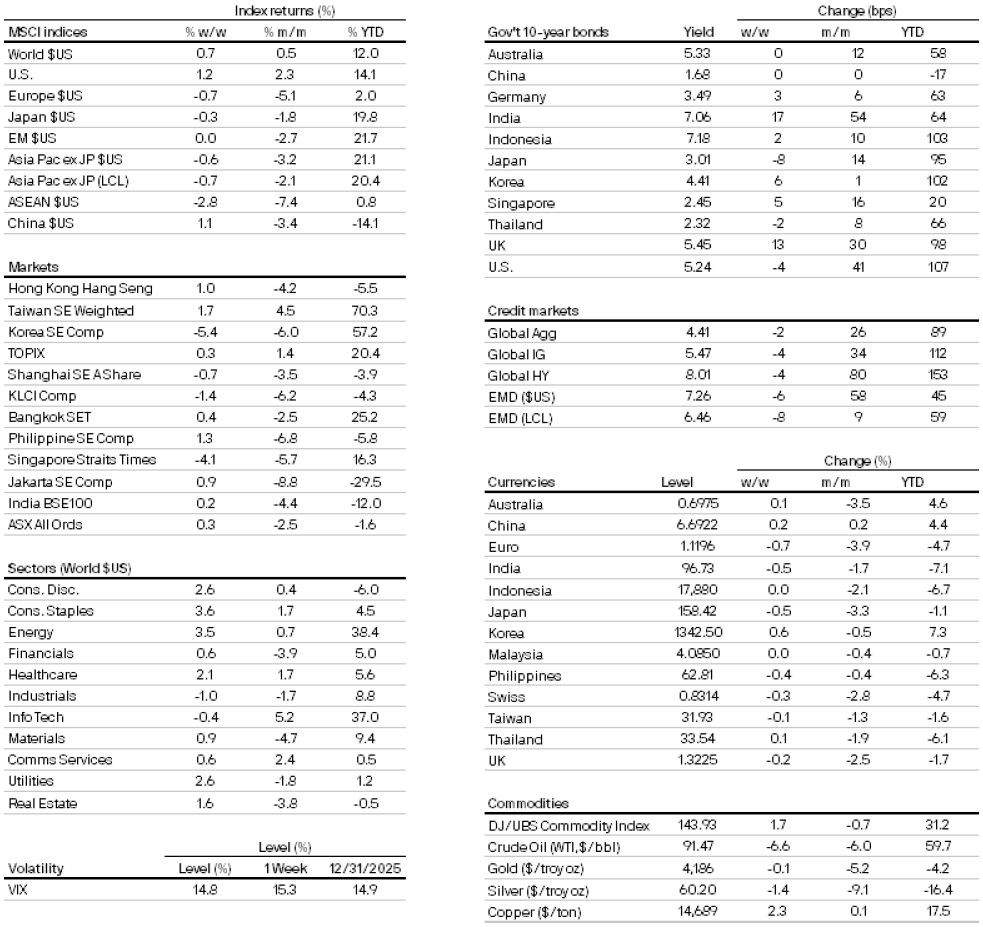
300a4900-f9d9-11e8-839f-fe2ee17e7f12
All returns in local currency unless stated otherwise.
Currencies’ return are based on foreign currencies per U.S. dollar. An appreciation of the foreign currency against the U.S. dollar would be positive and a depreciation of the foreign currency against the U.S. dollar would be negative.