logo
  • Funds
      Contact Us

      Fund Listing

      • Fund Explorer
      • Fund Managers
      • Fund Documents
      • How to Invest

      Capabilities

      • All Funds
      • Equities
      • Fixed Income
      • Multi-asset
      • ETF Investing
      • Investment Research

      Featured Funds

      • JPMorgan Singapore & Asia Equity Income Fund
      • JPMorgan Income Fund
      • Equity Funds
      • Equity Premium Income Active ETFs
      • JPMorgan Flexible Credit Fund
    • Insights
        Contact Us

        Market Insights

        • Market Insights Overview
        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Weekly Market Recap

          Start to simplify the complex with our Weekly Market Recap – a timely summary of recent market movements, economic developments and a look at what's ahead.

        • On the Minds of Investors

          What investment questions are on the minds of investors? Explore the questions investors ask frequently and find answers at J.P. Morgan Asset Management.

        • Podcasts

          Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

        • Mid-Year Outlook 2026

          Global uncertainties abound: the Middle East conflict, central banks' response to returning inflation, U.S. policy shifts and the fast-changing AI landscape.

        • Multimedia

          Interviews with Fund Managers and Investment Strategists bring you insights on global market trends and investment news.

        • Solving for Income

          Solving for Income uses slides from the Guide to the Markets – Asia to examine the role of income and why it should remain a key investment objective.

        • Solving for Fixed Income

          Slides from the Guide to the Markets – Asia examine the role of fixed income and why it should remain a key investment objective.

        • U.S. Policy Pulse Hub

          Insights to guide investors through the opportunities and risks arising from policy from the new administration.

        Portfolio Insights

        • Portfolio Insights Overview
        • Global Asset Allocation Views

          Amid resilient growth and a fading energy shock, we stay positive on risk assets, favoring U.S., Japan and EM equities and U.S. high yield.

        • Global Fixed Income Views

          Central bank credibility, solid profits, capex and resilient consumers lift expansion odds to 85%, outweighing inflation and AI headwinds.

        • Global Equity Views

          Massive AI spending is driving exceptional profit growth at reasonable valuations. We see long-term value in “AI losers” and defensive stocks.

        • Alternative Insights

          We bring you insights based on our nearly 50 years of experience investing in alternatives and more than 800 alternatives professionals around the globe.

        ETF Insights

        • ETF Insights overview
        • Guide to ETFs

          Explore J.P. Morgan Asset Management’s ETF investing guide with insights on ETF market trends and best investing practices for smarter portfolio decisions.

        Retirement Insights

        • Retirement Resources

          To achieve our desired retirement, it is important to anticipate the possible challenges that retirees could face and be better financially prepared.

        • Guide to Retirement

          Our Guide to Retirement, updated annually, provides an effective framework for retirement planning conversations with clients.

      • Investment Ideas
          Contact Us
          • What's new
          • Sustainable investing
          • ETF Knowledge
        • Resources
            Contact Us
            • All Resources
            • Announcements
            • Forms & Literature
            • About Mutual Funds
            • Investment Glossary
            • Insights App
          • About Us
              Contact Us
              • Overview
              • Awards
              • Diversity, Opportunity and Inclusion
              • Our Leadership Team
            • Contact Us
            You are about to leave the site Close
            J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
            CONTINUE Go Back
            Market Response

            Changes in style, but not in substance

            DK
            Dr. David Kelly

            Chief Global Strategist

            Published: 17/06/2026
            We continue to expect no rate adjustments from the Fed this year, as the committee appears comfortable it can remain patient given where policy rates are.

            At his first meeting as Federal Reserve (Fed) Chair, Kevin Warsh led the Federal Open Market Committee (FOMC) to a unanimous decision to hold the Federal Funds target rate range at 3.50-3.75% -- a disciplined debut for a chairman market had pegged as eager to cut, with inflation still running above target. That said, the statement saw a meaningful format shift from previous communications; it was cut in half. The prior April statement was a classic four-paragraph template detailing a reaction function and explicit forward guidance; both were completely stripped out. It also dropped the easing bias entirely, removing the language “the extent and timing of additional adjustment” which aligns with the recent hawkish dissents from the prior meeting.

            As a result, the statement’s assessment of growth, labor and inflation were succinct. Growth was referenced as “solid” and noted that productivity growth and capital investment are strong, a clear nod to Warsh’s optimistic view on AI’s potential for productivity gains. Description of labor improved to reflect a job market better in balance, stating job gains have kept pace with the workforce. On inflation, it attributed the rise in prices to the energy supply shock, though emphasized the central bank’s commitment to deliver on price stability.

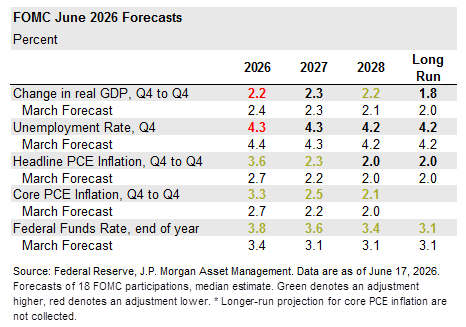
            Turning to the Summary of Economic Projections:

            • Growth was revised lower to 2.2% from 2.4% this year, and broadly unchanged over the next two years.
            • Unemployment was lowered by 0.1% to 4.3% in 2026 and untouched over the forecast period.
            • Headline and core inflation saw sizeable increases rising to 3.6% from 2.7%, and 3.3% from 2.7%, respectively, this year. Further out, inflation doesn’t reach target until 2028.
            • Notably, the median interest rate forecast indicates one rate hike this year, followed by one cut in 2027 and 2028. While Chair Warsh declined to submit forecasts, the committee remains split as nine of eighteen participants foresee at least one rate hike this year.

            The Chair used the press conference as an opportunity to announce five task forces whose remits entail:

            • Frequency and type of Fed communication which may include revisions to how the central bank communicates views to the market.
            • Fed balance sheet – assess the benefits and risks of an ample-reserves regime
            • Use and reliance on source data – explore methodological changes to improve data gathering and real-time accuracy
            • Productivity and jobs – during a period of transformation, survey the pace, reach and impact of new general-purpose (AI) technologies on the labor market and output
            • Fed’s inflation frameworks likely leaning more on trimmed-mean measures of inflation rather than traditional CPI and PCE methodologies.

            The Chair expects these task forces to begin work starting in the fall and conclude their findings by year end. Notably, Warsh was explicit that he does not foresee any change to the Fed’s long held 2% target. We continue to expect no rate adjustments from the Fed this year, as the committee appears comfortable it can remain patient given where policy rates are. Yields rose and stocks fell as the initial read may be considered hawkish. Altogether, while there will likely be changes to the Federal Reserve under this new Warsh regime, the central bank’s dual mandate of price stability, maximum employment, and its use of the Federal Funds rate as its primary policy tool appear cemented.


            0634a504-698b-11f1-91d9-55d496cdd5d5
            • Economy
            • Markets
            JPMorgan Asset Management

            • Terms of Use
            • Privacy Statement
            • Cookies Policy
            • Investment stewardship
            • Sitemap
            J.P. Morgan

            • J.P. Morgan
            • JPMorgan Chase
            • Chase

            The information contained herein is intended only for use by Singapore residents. By using this information, you are representing and warranting that you are either residing in Singapore or the applicable laws and regulations of your jurisdiction allow you to access the information, and you confirm that you accept the Terms of Use as set out in https://www.jpmorgan.com/sg/am/per/. Investment involves risk. Past performance is not indicative of future performance. In particular, funds which are invested in emerging markets and smaller companies may involve a higher degree of risk and are usually more sensitive to price movements. Investors should carefully read and consider the fund offering document(s), which contain details on investment objectives, risk factors, charges and expenses of the fund, before making any investment decisions. Information in this website does not constitute investment advice, or an offer to sell, or a solicitation of an offer to buy any security, investment product or service, nor a distribution of information for any such purpose. Informational sources are considered reliable but you should conduct your own verification of information contained herein. Issued by JPMorgan Asset Management (Singapore) Limited. This advertisement or publication has not been reviewed by the Monetary Authority of Singapore (“MAS”).


            JPMorgan Asset Management (Singapore) Ltd is regulated by the Monetary Authority of Singapore. (Co. Reg. No. 197601586K)