logo
  • My collections
    View saved content and presentation slides
  • Log out
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration
      • European domiciled products

      Solutions

      • Cash Strategies
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy

      Fund Information

      • Regulatory Updates
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook
        • Tokenization
        • Cash Cookbook
        • Case Studies
        • Partnership with fintechs
        • ESG Resources for Liquidity Investors
        • Leveraging the Power of Cash Segmentation
        • Cash Investment Policy Statement

        Market Insights

        • Market Insights Overview
        • Eye on the Market
        • Guide to the Markets
        • Market Updates
        • Podcast: Markets Explained

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency
        • Fixed Income
        • Long-Term Capital Market Assumptions
        • Sustainable investing
        • Strategic Investment Advisory Group
      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
        • About us
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Our Leadership Team
            • Our Commitment to Research
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My collections
              View saved content and presentation slides
            • Log out
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back

          <p>2026 Long-Term Capital Market Assumptions</p>

          The 30th annual edition explores how rising economic nationalism and fiscal activism create both challenges and silver linings for investors. Technology adoption will provide a near-term boost to profits and a longer-term boost to productivity.

          1. Home
          2. Insights
          3. Portfolio Insights Overview

          Projections for stronger portfolios

          Our assumptions see attractive real return potential, while differentiation across assets provides a richer hunting ground for active investors .

          Shifting landscapes and silver linings

          Rising economic nationalism and fiscal activism create both challenges and silver linings for investors. The return for a USD global 60/40 stock-bond portfolio holds steady at 6.4% while a 60/40+ with alternative assets increases overall returns and lowers volatility. We see a fertile backdrop for good active managers.

          Portfolio construction in flux

          A traditional “60/40” portfolio may be challenged to meet investor objectives. Diversifying the diversifiers is essential (global currencies, alpha strategies, and uncorrelated alternatives). A “60/40+” portfolio with diversified alternatives can boost returns and lower volatility – but the size and mix will be unique to each investor.

          Resilient growth and warmer inflation

          Despite dramatic policy shifts, particularly in the U.S., global growth remains resilient and inflation only slightly warmer and more variable. Economic nationalism and policy uncertainty create lasting drags and a more fragmented environment, giving technology an increasingly central role in sustaining growth. 

          Topics

          Matrices

          Our expectations for returns, volatilities and correlations. Use our interactive version to download the excel in your chosen currency.


          The assumptions are not designed to inform short term tactical allocation decisions. Our assumptions process is carefully calibrated and constructed to aid investors with strategic asset allocation or policy-level decisions over a 10- to 15-year investment horizon.

          Download Excel and PDF matrices by currency

          • Excel
          • PDF

          Assumptions

          Examine our return projections by major asset class and the thinking behind the numbers.

          Long-Term Capital Market Assumptions: Methodology Handbook

          A companion volume to dive deeper into our LTCMAs’ building blocks

          • Executive Summary
          • Macroeconomic
          • Public markets
          • Private markets
          • Volatility, Correlation and Portfolio Implications

          EXECUTIVE SUMMARY

          Shifting landscapes and silver linings

          Key points

          Economic nationalism and barriers to trade and migration weigh on global growth. But they are also galvanizing offsetting positive forces – creating silver linings. Trade uncertainty spurs fiscal activism. Labor market constraints accelerate technology adoption, providing a near-term boost to profits and a long-term boost to productivity.


          Even after a year of strong equity gains, asset returns hold up. Profitability offsets valuation for global stocks. Bond returns rise amid higher term risk premia. Alternatives offer growing opportunities to strengthen portfolio resilience.


          The economic landscape is shifting. But, in our view, much of what worries investors today will ultimately pale beside the silver linings we see breaking through over the long run.

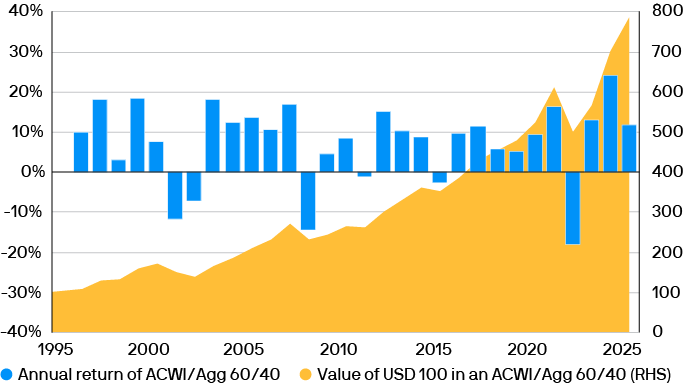
          A steady exposure to stocks and bonds has stood the test of time over the last three decades

          Growth of 60/40 over 30 years, and average returns through the period
          ltcma-executive-summary-exihibit1

          Source: Bloomberg, J.P. Morgan Asset Management; data as of September 30, 2025.

          MACROECONOMIC ASSUMPTIONS

          Resilient growth and warmer inflation

          Key points

          Elevated tariffs and restrictive immigration policies lower our U.S. GDP growth assumption. But limited labor supply spurs investments in advanced technologies, boosting productivity gains. 


          Developed market (DM) growth declines marginally, mainly on the U.S. downgrade, yet nationalism and populism, boosting defense and infrastructure spending, sustain growth elsewhere. 


          Emerging market (EM) growth is stable: India’s favorable demographics and China’s productivity offset lower capital investment. 


          DM inflation rises amid Europe’s fiscal spending, U.S. trade frictions and Japan’s rising inflation expectations. China weighs down EM inflation.

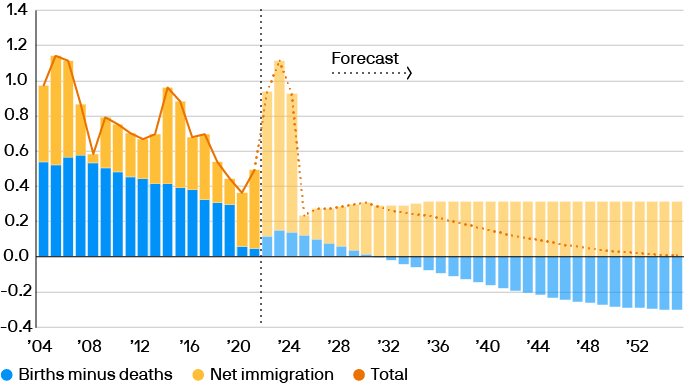
          Tighter immigration policies appear set to pull U.S. labor force growth toward zero

          Contributions to U.S. population growth (% change y/y)
          ltcma-macro-exihibit2

          Source: Congressional Budget Office, J.P. Morgan Asset Management; data as of September 30, 2025.

          PUBLIC MARKET ASSUMPTIONS

          Resilient profits, higher yields

          Key points

          We continue to see solid long-term return opportunities across public markets, despite a strong rally in risk assets and a reshuffling of global growth forecasts. Our 10- to 15-year forecast sees global equities returning 7.0% annualized in USD, supported by resilient corporate profitability and rapid technological innovation.
           

          With yields higher, we forecast the highest U.S. government bond returns since the financial crisis, at 4.6%. However, bonds’ traditional hedging role may be less reliable in this new environment.


          Credit markets’ improved fundamentals and higher issuer quality leave our U.S. high yield forecast unchanged at 6.1%.


          A weakening USD makes portfolio FX hedging decisions paramount, and adds a tailwind for non-USD returns.

          Uncertainty about policymaking stability and safe-haven appeal has raised Treasuries’ term premium

          Expected yield curve slope

          ltcma-public-market-exihibit3

          Source: J.P. Morgan Asset Management; data as of September 30, 2025.

          PRIVATE MARKETS AND ALTERNATIVE ASSET ASSUMPTIONS

          Powerful market forces set capital in motion

          Key points

          Economic nationalism, fiscal activism and technological innovation will drive structural change in private markets and set capital in motion. Asset valuations may recalibrate and opportunities emerge.
           

          Higher trade barriers will dampen global economic growth and raise inflation – with a mixed impact on real assets. Private equity and hedge funds benefit from looser U.S. financial regulation.


          Fiscal activism allows for productivity gains; interest rates ease globally. Deal volume and valuations in the real estate market should improve, and declining rates should similarly affect private equity.


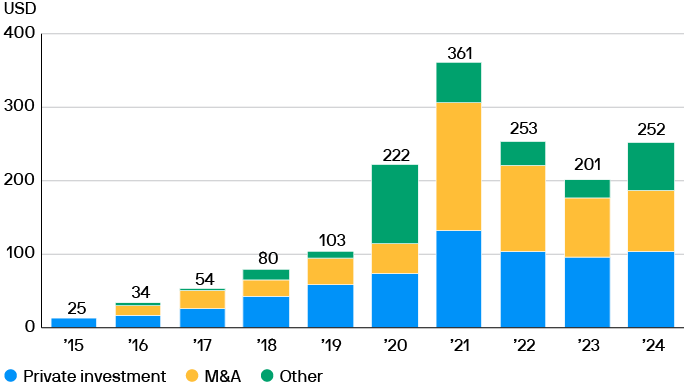
          Surging investment in technology and AI adoption will drive innovation and efficiency across all private markets, particularly private equity, but also real estate and infrastructure.

          Globally, AI investment continues to drive significant deal flow

          Global corporate investment in AI (by type), USD bn
          ltcma-private-exihibit4

          Source: Stanford University Artificial Intelligence Index Report, J.P. Morgan Asset Management; data as of September 30, 2025.

          Volatility, Correlation and Portfolio Implications

          Changing portfolio construction in a shifting landscape

          Key Points

          Over the next decade investors will need to grapple with inflation and rate shocks as well as economic (growth) shocks. It’s a new landscape, reflecting the interplay among the forces of economic nationalism and fiscal activism. Together they are reshaping volatility and asset class correlation expectations. 
           

          In the face of higher and more unstable stock-bond correlations, investors need to think differently about portfolio resilience. To diversify the diversifiers, currency diversification, alpha strategies and certain alternative assets are essential.


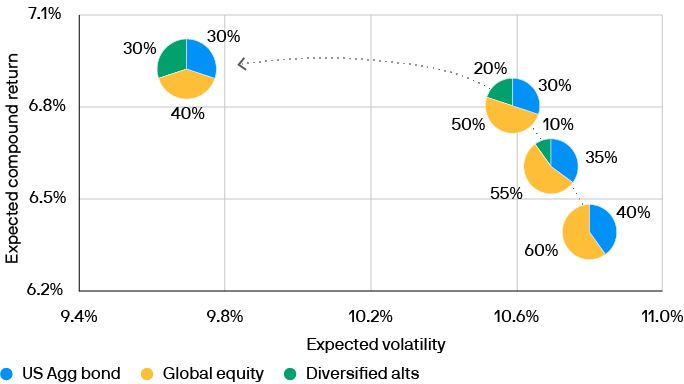
          A “60/40+” portfolio, which includes a diversified alternatives allocation, has the potential to boost overall returns and lower volatility relative to a traditional “60/40” public market portfolio.

          Portfolios that include alternatives can improve risk-adjusted returns, but the 60/40+ can vary

          Projections for portfolio returns and volatility, based on 2026 LTCMA figures
          ltcma-portfolio-exihibit5

          Source: J.P. Morgan Asset Management; data as of September 30, 2025. Diversified alternatives allocation includes global real estate, global real assets, private credit, hedge funds and private equity.

          Download this year's Long Term Capital Market Assumptions report
          ltcma-cover-banner-340x440