


Week in review
- U.S. Sep inflation rose to 3.7% y/y
- China Sep inflation rose to 0.9% y/y
- Monetary Authority of Singapore kept all policy settings unchanged
Week ahead
- China Q3 GDP and Sep economic activity
- Japan Sep inflation
- Bank of Korea interest rate decision
Thought of the week
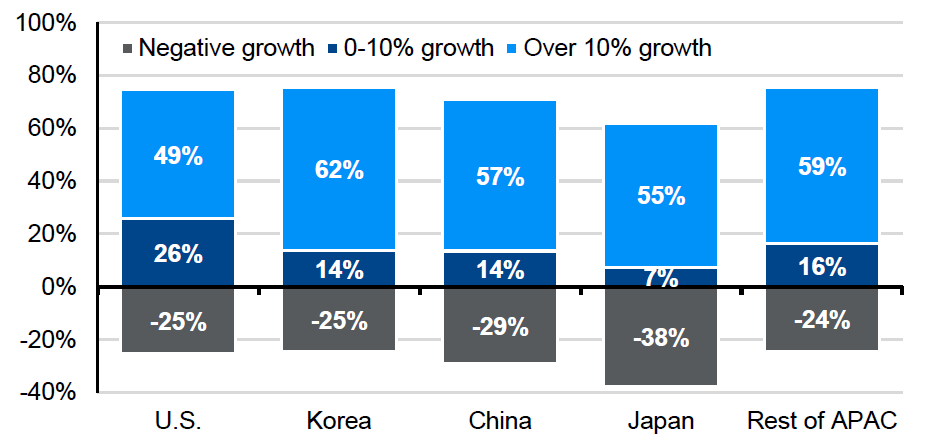
The 26Q3 earnings season kicked off last week with U.S. financials and Asian technology leading the reporting schedule. Global earnings growth is expected to remain extremely robust, with consensus projecting increases of 27.6% in the U.S. and 64.4% in Asia. While headline growth is still expected to be heavily concentrated in technology on the AI upcycle, earnings strength is far broader than the headline suggests. Consensus estimates point to double-digit earnings growth for more than half of companies in most markets, with Korea at 62%, China at 57%, Japan at 55% and the U.S. at 49%. This breadth reflects the fundamental support from structural drivers beyond AI, including the global industrial upgrade, Japan’s domestic reflation and China’s anti-involution policies. With equity performance increasingly reliant on earnings growth rather than valuation re-ratings, this marks the current earnings season as especially important for monitoring both earnings delivery and management guidance.
Distribution of companies by expected 26Q3 earnings growth
By company count, year-over-year growth, consensus estimates
Source: FactSet, MSCI, S&P Global, J.P. Morgan Asset Management. U.S., China, Japan, Korea, and APAC equity indices used are S&P 500, MSCI China, MSCI Japan, MSCI Korea, and MSCI AC Asia Pacific, respectively. Analysis includes quarterly reporting companies only and earnings refer to GAAP net income. Past performance is not a reliable indicator of current and future results. Data reflect most recently available as of 16/10/2026.
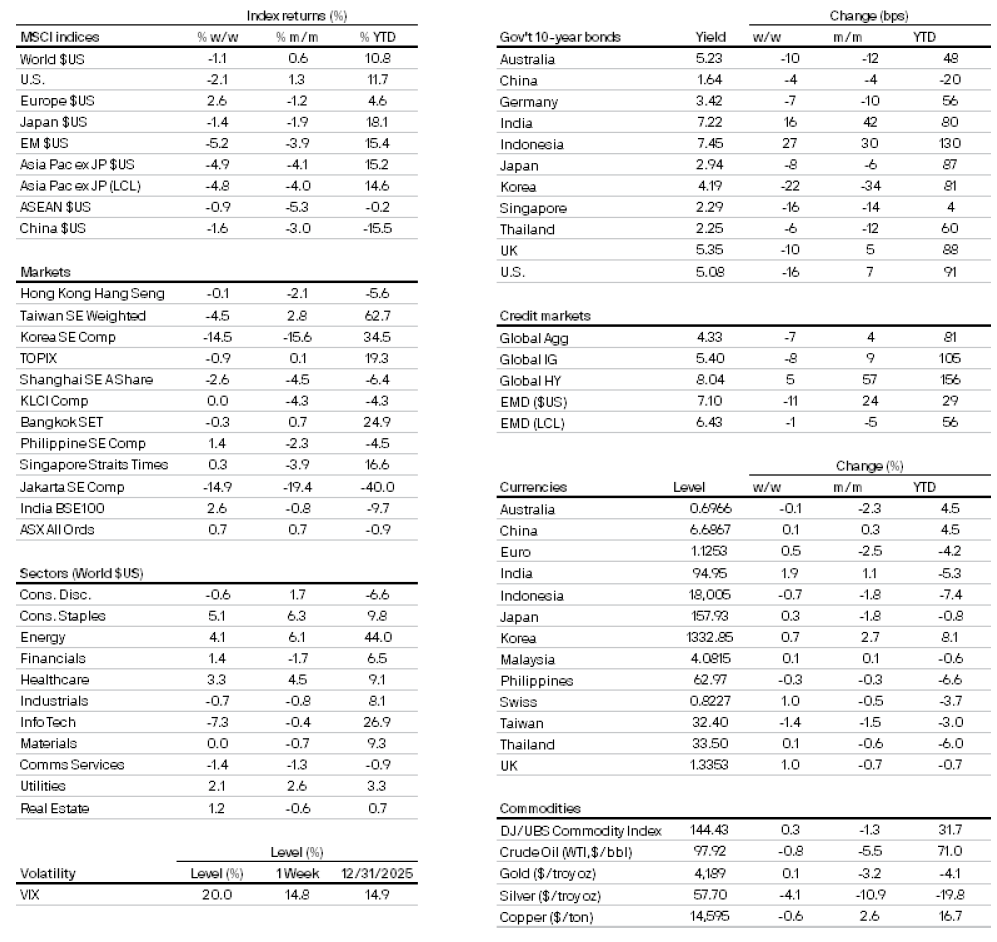
Market data
300a4900-f9d9-11e8-839f-fe2ee17e7f12
All returns in local currency unless stated otherwise.
Currencies’ return are based on foreign currencies per U.S. dollar. An appreciation of the foreign currency against the U.S. dollar would be positive and a depreciation of the foreign currency against the U.S. dollar would be negative.