logo
  • My collections
    View saved content and presentation slides
  • Logout
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration
      • European domiciled products

      Solutions

      • Cash Strategies
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy

      Fund Information

      • Regulatory Updates
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook

          Global Liquidity Investment Outlook

        • Tokenization

          Explore the full whitepaper to learn how tokenized MMFs can transform your approach to cash management and position your organization at the forefront of digital finance.

        • Cash Cookbook

          The Cash Cookbook, your guide to cash and liquidity management success, helps you choose the right liquidity solution for your needs and risk tolerance.

        • Case Studies

          Read about companies with specific cash management challenges and the solutions when they worked with J.P. Morgan Asset Management.

        • Partnership with fintechs

          A focus on digital innovation and institutional liquidity solutions drive our dynamic partnership with fintech.

        • ESG Resources for Liquidity Investors

          We’ve created a clear, rigorous ESG process meets the many needs of liquidity investors.

        • Leveraging the Power of Cash Segmentation

          The most effective strategy incorporates a clear investment policy, well-defined goals and parameters for liquidity, quality and return.

        • Cash Investment Policy Statement

          How to write an investment policy statement for your organization

        Market Insights

        • Market Insights Overview
        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Market Updates

          Read our weekly commentaries to get market insights that may help inform your investment strategy.

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency

          Our currency team provides solutions for clients, controlling risk using passive management strategies and generating returns by actively managing global currencies.

        • Fixed Income

          A complex mix of monetary, credit and fiscal forces is changing the bond landscape. Discover how flexible fixed income approaches can seek returns, income and resilience.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Sustainable investing

          We believe that ESG considerations can play a critical role in a long-term investment strategy.

        • Strategic Investment Advisory Group

          The Strategic Investment Advisory Group approaches today’s investment challenges with a global view across asset classes.

      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
        • About us

            About us

            Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

            • Overview
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Our Leadership Team
            • Our Commitment to Research
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My collections
              View saved content and presentation slides
            • Logout
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back
          1. The forest and the trees

          • LinkedIn Twitter Facebook WhatsApp

          The forest and the trees

          19-11-2019

          Kelsey Berro

          When constantly watching financial markets and following the 24-7 news flow, it can be easy to get caught up in the trees and miss the forest. Take for instance the observation that 10-year Treasury yields have moved 50bps higher since reaching the local lows in early September. But beyond the fact that long-term yields have retraced higher, what else has changed?

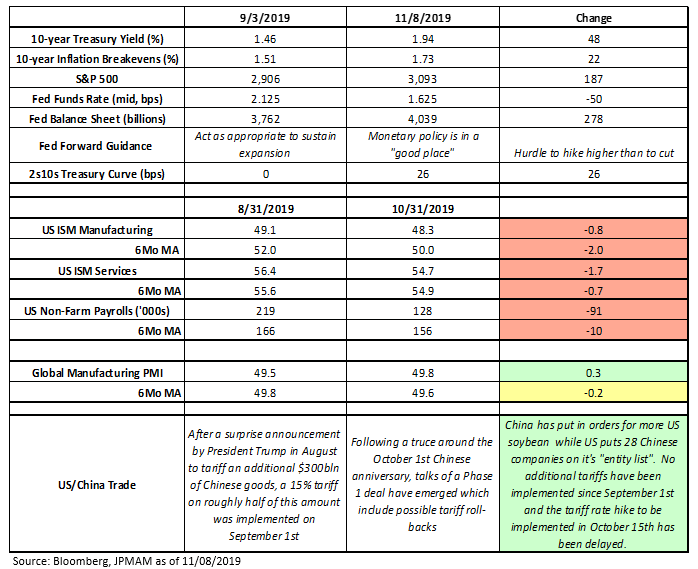
          In an effort to objectively investigate this question, the following table shown below depicts the changes in financial markets, monetary policy, US and global economic data and the developments in the US/China trade situation since reaching the local yield lows.
          5 Key Observations:

          1. The Fed has cut rates by 50bps and the balance sheet has started re-expanding. However, the Fed’s forward guidance has shifted to a pause indicating that monetary policy is sufficiently accommodative, for now.

          2. The US yield curve shape has normalized and the 2s10s spread had steepened accompanied by a rise in inflation breakevens. Simultaneously, US equity markets have reached new highs.

          3. The trend in US economic data continues to slow.

          4. Global manufacturing activity is stabilizing at low levels.

          5. US/China trade developments suggest possible progress in talks using a phased approach but even a “Phase 1” agreement is not yet set in stone.
             

          Interpretation:

          The changes in financial markets since September suggest investors are reducing their near-term recession probabilities following a prompt policy response from the Fed resulting in higher nominal yields, wider inflation breakevens, buoyant risk assets and a steeper US Treasury curve. This seems appropriate given that the Fed has eased policy and started re-expanding the balance sheet, global manufacturing activity has stabilized and headlines regarding US/China trade policy have improved.

          Despite the re-pricing of recession risk, a more significant re-evaluation of the macro outlook could still be considered premature given that the positive trade headlines have not resulted in a concrete agreement between the US and China and the trend for US economic data remains soft. Furthermore, finding a catalyst that would result in a big resurgence in confidence and capex spending, even if there was a truce with China, is currently hard to identify as companies may still be hesitant to invest ahead of the US Presidential election. One possibility would be a surge in fiscal stimulus. Another possibility would be a doubling down on global central bank easing to more credibly combat low inflation resulting into a re-acceleration in global growth.

          Turning to the Fed, the balance of risks for US monetary policy remains that the FOMC is more likely to ease again than to tighten. As we interpret the Fed’s reaction function, the hurdle to hike is much higher (and would take much more time to develop as it would require a re-acceleration in the data and more importantly higher inflation) than that to ease again if the service sector in the US were to weaken.

          Outlook:

          Undoubtedly, we have experienced some large swings in US Treasury yields – some of the largest since the election in 2016. However, it appears too early to clearly confirm a regime shift (like the one in late 2016) is occurring. The stabilization in global manufacturing activity and US/China trade are positive developments that should reduce near-term recession risk. What has not changed is the fact that the medium term trajectory for the US economy is still muted and the Fed is more likely to cut rates further than to raise them. These factors should ultimately keep a lid on how far Treasury yields can rise.

          • Federal Reserve
          • Monetary Policy
          • Rates
          • Economic Outlook

          RELATED ARTICLES

          FOMC statement & potential impact on fixed income

          Following the Fed's announcement, find our latest market views from the Global Fixed Income, Currency & Commodities Team (GFICC).

          Read more

          FOMC statement & potential impact on fixed income

          Following the Fed's announcement, find our latest market views from the Global Fixed Income, Currency & Commodities Team (GFICC).

          Read more

          FOMC statement & potential impact on fixed income

          Following the Fed's announcement, find our latest market views from the Global Fixed Income, Currency & Commodities Team (GFICC).

          Read more