logo
  • My collections
    View saved content and presentation slides
  • Logout
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration
      • European domiciled products

      Solutions

      • Cash Strategies
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy

      Fund Information

      • Regulatory Updates
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook

          Global Liquidity Investment Outlook

        • Tokenization

          Explore the full whitepaper to learn how tokenized MMFs can transform your approach to cash management and position your organization at the forefront of digital finance.

        • Cash Cookbook

          The Cash Cookbook, your guide to cash and liquidity management success, helps you choose the right liquidity solution for your needs and risk tolerance.

        • Case Studies

          Read about companies with specific cash management challenges and the solutions when they worked with J.P. Morgan Asset Management.

        • Partnership with fintechs

          A focus on digital innovation and institutional liquidity solutions drive our dynamic partnership with fintech.

        • ESG Resources for Liquidity Investors

          We’ve created a clear, rigorous ESG process meets the many needs of liquidity investors.

        • Leveraging the Power of Cash Segmentation

          The most effective strategy incorporates a clear investment policy, well-defined goals and parameters for liquidity, quality and return.

        • Cash Investment Policy Statement

          How to write an investment policy statement for your organization

        Market Insights

        • Market Insights Overview
        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Market Updates

          Read our weekly commentaries to get market insights that may help inform your investment strategy.

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency

          Our currency team provides solutions for clients, controlling risk using passive management strategies and generating returns by actively managing global currencies.

        • Fixed Income

          A complex mix of monetary, credit and fiscal forces is changing the bond landscape. Discover how flexible fixed income approaches can seek returns, income and resilience.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Sustainable investing

          We believe that ESG considerations can play a critical role in a long-term investment strategy.

        • Strategic Investment Advisory Group

          The Strategic Investment Advisory Group approaches today’s investment challenges with a global view across asset classes.

      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
        • About us

            About us

            Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

            • Overview
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Our Leadership Team
            • Our Commitment to Research
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My collections
              View saved content and presentation slides
            • Logout
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back
          1. Taxable munis in 2020: Opportunity knocks

          • LinkedIn Twitter Facebook Line WhatsApp

          Taxable munis in 2020: Opportunity knocks

          Margaret Byrne

          Michelle Hallam

          Municipal issuers are realizing savings by issuing taxable municipals to refund higher cost tax exempt debt.  So what does that mean for the market?  A spike in supply and more diversified issuance will be an opportunity to add high quality long duration at attractive spreads.  We’ve already seen institutional investors taking advantage of the opportunity.

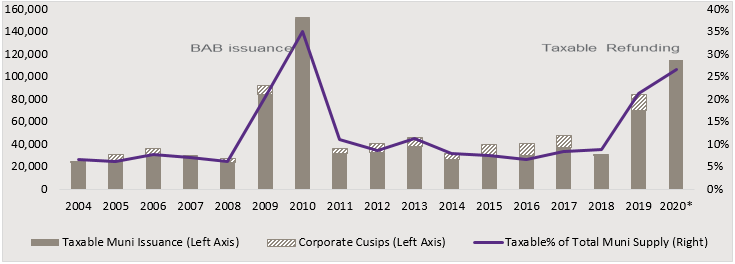
          Of the $436bn of munis priced in 2019, $85bn was taxable. For 2020, we estimate that if rates remain stable, overall supply will again approach $435bn with over $100bn in taxable munis, almost a quarter of total supply.  To put these numbers in perspective, prior to the uptick in supply last year, taxable muni supply from 2014 to 2018 averaged only $39bn.

          Exhibit 1: Taxable issuance is expected to spike
          Sources: Bond Buyer, Citi, JPMAM as of 01/15/2020

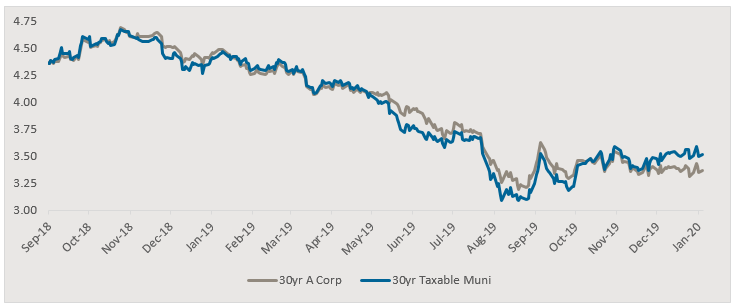
          During the 2009 and 2010 Build America Bond (BAB) bubble, $85bn and $153bn respectively priced as part of the American Recovery and Reinvestment Act of 2009, which was created to reduce the cost of borrowing for new capital projects to spur economic growth.  During that period, high quality taxable munis were priced cheaper than A-rated corporates due to a number of factors: 1) municipalities were under budgetary stress, 2) bond insurers were being downgraded by the rating agencies, and 3) many taxable investors were unfamiliar with muni credits.    Since then, non-traditional municipal investors have gained familiarity with the market, which has kept spreads on A-rated munis vs. A- rated corporates from reaching the levels seen in 2009-2010, when that spread was almost 100bps.

          Exhibit 2: Yields on Long Taxable A-rated Munis vs. Long A-rated Corporates
          Source: BaML ICE and TM3 MMD as of 01/15/2020

          Why The Surge

          Municipalities lost an important tool used to lower interest cost on outstanding debt, the tax exempt advance refunding.  Prior to the Tax Cuts and Jobs Act (TCJA), municipal issuers could advance refund higher cost debt by issuing a tax exempt refunding bond and use the proceeds to fund an escrow of government securities in an amount sufficient to pay the principal and interest on the outstanding debt. 

          Congress no longer permits muni advance refunding as it is considered double dipping because for a limited time, while both the refunding as well as the refunded bonds are outstanding, there are two sets of tax exempt bonds for any given project.

          With interest rates at multi-decade lows, the refunding math again works for issuers – this time using taxable debt.  The taxable advance refunding meets the requirement that only one tax exempt issuer per project is outstanding at any time. 

          So far, issuance has been fairly well received, but the uptick in supply has made valuations more attractive.  In 2020, issuance should look less skewed toward healthcare and education because every municipality across the country, large and small, revenue and general obligation, lower rated and higher rated, may tap the market.  This will create significant opportunities for managers who have expertise in the fragmented muni market – as both larger index-eligible and especially non-index eligible issues come to the market looking for buyers. 

          Continued low rates and significantly more taxable muni supply should create opportunities, especially for clients who want to take advantage of the high quality asset class to diversify portfolios heavily weighted in corporate credit.

          More on the market

          2019 saw a record breaking wave of demand for munis of nearly $100bn into funds that has surpassed the previous record flows during the recession when investors flocked to the safety and security of municipal bonds.  Munis have become one of the last tax shelters.  TCJA limited the deduction of income, property and in some states sales taxes to $10k.  For many high net worth tax payers, that means the loss of significant deductions that run into the six figures

          Taxable municipal deals are priced with both municipal as well as with corporate cusips.  Issuing in the corporate market typically requires less rigorous disclosure and has a shorter time to market.  The corporate market attracts a broader investor base given the typically larger issuance size, more recognizable credits, bulleted structure and make-whole calls.  Issuance of taxable in the muni market can come with either make-whole calls or with optional ten year par calls, typical of most muni market issues.

          • Market Views
          • Latest

          RELATED ARTICLES

          'Blue ripple' and the USD outlook

          The ‘Blue wave’ the market had prepared for now appears to be more of a ‘Blue ripple’ and currency markets are adjusting to a different political outlook.

          Read more

          Multiple reasons for multi-family

          The agency CMBS market offers an attractive way for fixed income investors to access one of the more resilient sectors of the commercial real estate market.

          Read more

          Is there green in the graying baby boomers? Why we like non-profit tax-exempt senior living bonds

          At our recent IQ meeting, we concluded municipal high yield was one of our best ideas. In this piece we take a deep dive into one of the more opportunistic sectors in the tax-exempt market.

          Read more