logo
  • My collections
    View saved content and presentation slides
  • Log out
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration
      • European domiciled products

      Solutions

      • Cash Strategies
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy

      Fund Information

      • Regulatory Updates
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook

          Global Liquidity Investment Outlook

        • Tokenization

          Explore the full whitepaper to learn how tokenized MMFs can transform your approach to cash management and position your organization at the forefront of digital finance.

        • Cash Cookbook

          The Cash Cookbook, your guide to cash and liquidity management success, helps you choose the right liquidity solution for your needs and risk tolerance.

        • Case Studies

          Read about companies with specific cash management challenges and the solutions when they worked with J.P. Morgan Asset Management.

        • Partnership with fintechs

          A focus on digital innovation and institutional liquidity solutions drive our dynamic partnership with fintech.

        • ESG Resources for Liquidity Investors

          We’ve created a clear, rigorous ESG process meets the many needs of liquidity investors.

        • Leveraging the Power of Cash Segmentation

          The most effective strategy incorporates a clear investment policy, well-defined goals and parameters for liquidity, quality and return.

        • Cash Investment Policy Statement

          How to write an investment policy statement for your organization

        Market Insights

        • Market Insights Overview
        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Market Updates

          Read our weekly commentaries to get market insights that may help inform your investment strategy.

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency

          Our currency team provides solutions for clients, controlling risk using passive management strategies and generating returns by actively managing global currencies.

        • Fixed Income

          A complex mix of monetary, credit and fiscal forces is changing the bond landscape. Discover how flexible fixed income approaches can seek returns, income and resilience.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Sustainable investing

          We believe that ESG considerations can play a critical role in a long-term investment strategy.

        • Strategic Investment Advisory Group

          The Strategic Investment Advisory Group approaches today’s investment challenges with a global view across asset classes.

      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
        • About us

            About us

            Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

            • Overview
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Our Leadership Team
            • Our Commitment to Research
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My collections
              View saved content and presentation slides
            • Log out
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back
          1. Confirmation, Conflict, Hope

          • LinkedIn Twitter Facebook Line WhatsApp

          Confirmation, Conflict, Hope

          02-06-2020

          Bob Michele

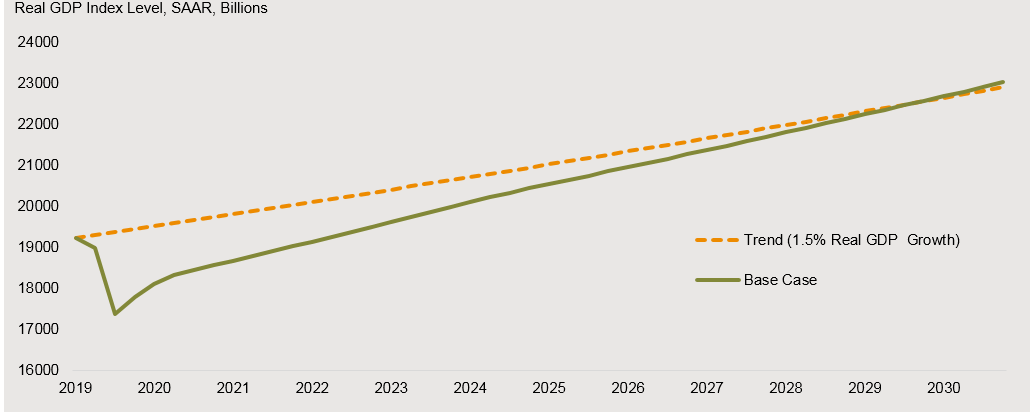
          Over the last couple of months, we have received a lot of criticism for our economic forecast. In attempting to model what a recovery could look like following the pandemic, we were estimating that it would take about 10 years to close the output gap and return to something approximating full employment.

          Real GDP GFICC Base Case Forecast verus Trend Growth starting Q4 2019
          Source: J.P. Morgan Asset Management, BEA and Bloomberg as of 6/1/2020

          Of course, the push back centered on the overwhelming fiscal and monetary policy response which has been a multiple of what was experienced during the Great Financial Crisis (GFC)…and deployed in weeks as opposed to years. It is true that if GDP is modeled on an annualized quarterly basis, the recovery will look like a ‘V’ with the bottom being put in 2020 Q2. This is what we saw during the GFC. But if GDP is modeled versus its long term potential, it will take about 10 years to return to that trend line. Hence, our view of a check mark shape recovery…..again, similar to what we saw after 2008 when it took about 8 ½ years to return to the economy’s long term potential.

          This week, the Congressional Budget Office released a letter to Democratic Leader Charles Schumer effectively confirming our original analysis. https://www.cbo.gov/system/files/2020-06/56376-GDP.pdf

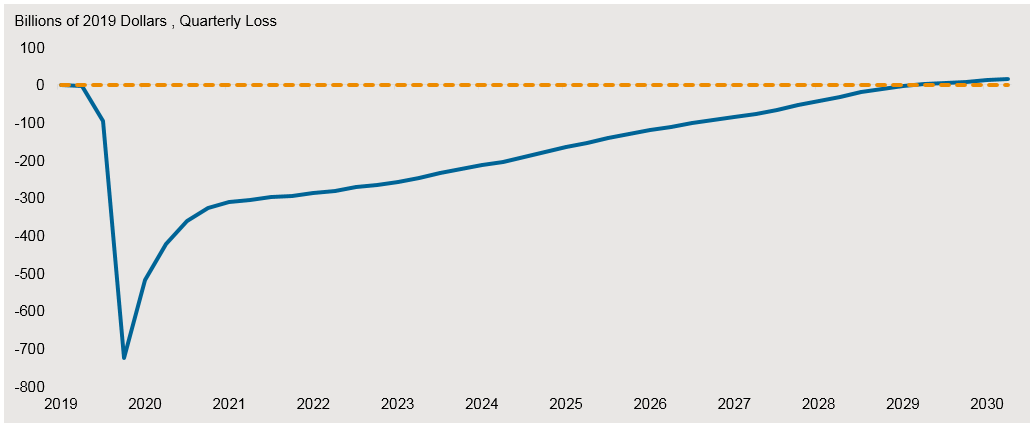
          In a normal year, the CBO forecasts economic variables going out 10 years bi-annually. Following the coronavirus, their January 2020 forecast looked woefully out of date. In May, they took their first stab at projecting the new economic reality out to 2021 warning that unemployment could still be double digits for much of that time. Now, with some more time to gather information, the CBO is looking out to 2030 and has formally revised its growth estimates lower for every year until 2029. We should note that their original forecasts were already more rosy than ours (and they also use a higher trend growth rate) but this at least implies the output gap won’t be closed till at the earliest 2027 according to their new estimates.

          Difference in Real Gross Domestic Product Between CBO’s May 2020 and January 2020 Projections
          Source: CBO as of 6/1/2020 

          The importance of both our analyses is to highlight that the road to recovery will be long and challenging. Inflation will remain low and unemployment will be unacceptably high. This is an unfolding reality that policy makers (public and private) must accept and begin to deal with.

          Like everyone, I am very disturbed by the events of the last week. I have worried for months that on June 5th, we might see an unemployment rate in the US print at over 20% just as the equity markets are rising back toward their highs. The pandemic is disproportionately taking a toll on our underserved and minority communities while the aggregate policy response seems to be inflating asset prices once again. Growing frustration was bound to erupt and the horrible death of George Floyd became the unfortunate catalyst. Like some others, I am worried - but hopeful - that there can be a path to recovery which is promising for all.

          I do not blame the Federal Reserve or the other central banks for their policy response. They have done what was needed to help underwrite the amount of debt needed to fund a recovery. Trillions upon trillions upon trillions. What all policy makers should take away from the GFC is that austerity – a concentrated focus on deleveraging and paying down debt – is the wrong policy response for the foreseeable future. And by all policy makers, I mean central bankers, politicians and corporate CEOs. At a time when unemployment is high, policy makers should be looking for longer term solutions and investments.

          Perhaps an infrastructure spend of $1T in the US spread out over 3-5 years instead of the 10 years mooted a few years ago would be a good use of public funds? It would create jobs, provide genuine stimulus in contrast to what we believe is currently aid and assistance, and encourage more durable consumption. And surely, the pandemic has highlighted deficiencies in our healthcare system which could be addressed at both the Federal and local levels of government. And this time, corporate CEOs need to be incented to invest in capex rather than to deleverage and then buy back stock or raise dividends. Certainly corporate investment and spending could be undertaken to catch up to the work-from-home/stay-at-home movement. I am sure that everyone has very good ideas of their own which could be added to this list.

          I realize that all of this will exacerbate the debt burden. But the central banks are helping to make the cost affordable and the potential benefits are appealing.  History has taught us that every crisis will present opportunities. Let’s hope this time the opportunity is broadly diverse and inclusive.

          • Economic Outlook
          • Market Views

          Related Content

          'Blue ripple' and the USD outlook

          The ‘Blue wave’ the market had prepared for now appears to be more of a ‘Blue ripple’ and currency markets are adjusting to a different political outlook.

          Read more

          Multiple reasons for multi-family

          The agency CMBS market offers an attractive way for fixed income investors to access one of the more resilient sectors of the commercial real estate market.

          Read more

          FOMC statement & potential impact on fixed income

          Following the Fed's announcement, find our latest market views from the Global Fixed Income, Currency & Commodities Team (GFICC).

          Read more