logo
  • My collections
    View saved content and presentation slides
  • Log out
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration
      • European domiciled products

      Solutions

      • Cash Strategies
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy

      Fund Information

      • Regulatory Updates
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook

          Global Liquidity Investment Outlook

        • Tokenization

          Explore the full whitepaper to learn how tokenized MMFs can transform your approach to cash management and position your organization at the forefront of digital finance.

        • Cash Cookbook

          The Cash Cookbook, your guide to cash and liquidity management success, helps you choose the right liquidity solution for your needs and risk tolerance.

        • Case Studies

          Read about companies with specific cash management challenges and the solutions when they worked with J.P. Morgan Asset Management.

        • Partnership with fintechs

          A focus on digital innovation and institutional liquidity solutions drive our dynamic partnership with fintech.

        • ESG Resources for Liquidity Investors

          We’ve created a clear, rigorous ESG process meets the many needs of liquidity investors.

        • Leveraging the Power of Cash Segmentation

          The most effective strategy incorporates a clear investment policy, well-defined goals and parameters for liquidity, quality and return.

        • Cash Investment Policy Statement

          How to write an investment policy statement for your organization

        Market Insights

        • Market Insights Overview
        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Market Updates

          Read our weekly commentaries to get market insights that may help inform your investment strategy.

        • Podcast: Markets Explained

          Signal or noise? In this weekly podcast, Karen and Hugh digest the newsflow in an increasingly tumultuous world and work out what it means for global investors.

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency

          Our currency team provides solutions for clients, controlling risk using passive management strategies and generating returns by actively managing global currencies.

        • Fixed Income

          A complex mix of monetary, credit and fiscal forces is changing the bond landscape. Discover how flexible fixed income approaches can seek returns, income and resilience.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Sustainable investing

          We believe that ESG considerations can play a critical role in a long-term investment strategy.

        • Strategic Investment Advisory Group

          The Strategic Investment Advisory Group approaches today’s investment challenges with a global view across asset classes.

      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
        • About us

            About us

            Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

            • Overview
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Our Leadership Team
            • Our Commitment to Research
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My collections
              View saved content and presentation slides
            • Log out
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back
          Liquidity Insights

          China PBoC – Navigating the Imbalances

          AS
          Aidan Shevlin

          Head of International Liquidity Fund Management
          Published: 29-10-2025

          In brief

          • China’s GDP growth remains on track to meet the government’s “around 5%” target for 2025, suggesting limited need for major fiscal stimulus in Q4 unless external risks escalate.
          • Growth remains uneven, supported by robust industrial production but weighed down by weak consumption and investment as the property market downturn continues to drag on domestic demand.
          • The People’s Bank of China (PBoC) is likely to maintain an accommodative stance, although further rate cuts are unlikely as stability and liquidity take precedence.

          Robust growth – amid imbalances

          China’s economy outperformed expectations in 2025, with Q3 GDP up 4.8%y/y despite ongoing geopolitical and trade challenges.  However, the underlying picture is more complex as strong exports and industrial production contrast with persistent weakness in consumption, investment, and real estate.  

          Production has led the way, rising 6.5%y/y in September, fueled by export-driven sectors like autos and semiconductors. However, this momentum may soften as frontloading and seasonal effects fade.  On the demand side, fixed asset investment slipped into negative territory for the first time since Covid-induced shutdowns in 2020, driven by declines in manufacturing, infrastructure, and especially property. The real estate sector remains a major concern, with double-digit drops in new home sales and investment, and ongoing price declines. Retail sales growth also slowed to 3%y/y, reflecting subdued consumer confidence and fading fiscal support.

          While growth is expected to moderate in Q4-25, the current trajectory should enable China to meet its “around 5%” target, reducing the need for additional fiscal or monetary stimulus. Instead, policy is now focused on executing existing fiscal measures.  The recent Fourth Plenum and ongoing US-China trade talks are possible economic pivots, though significant near-term policy changes are unlikely.


          Monetary policy – stability over stimulus

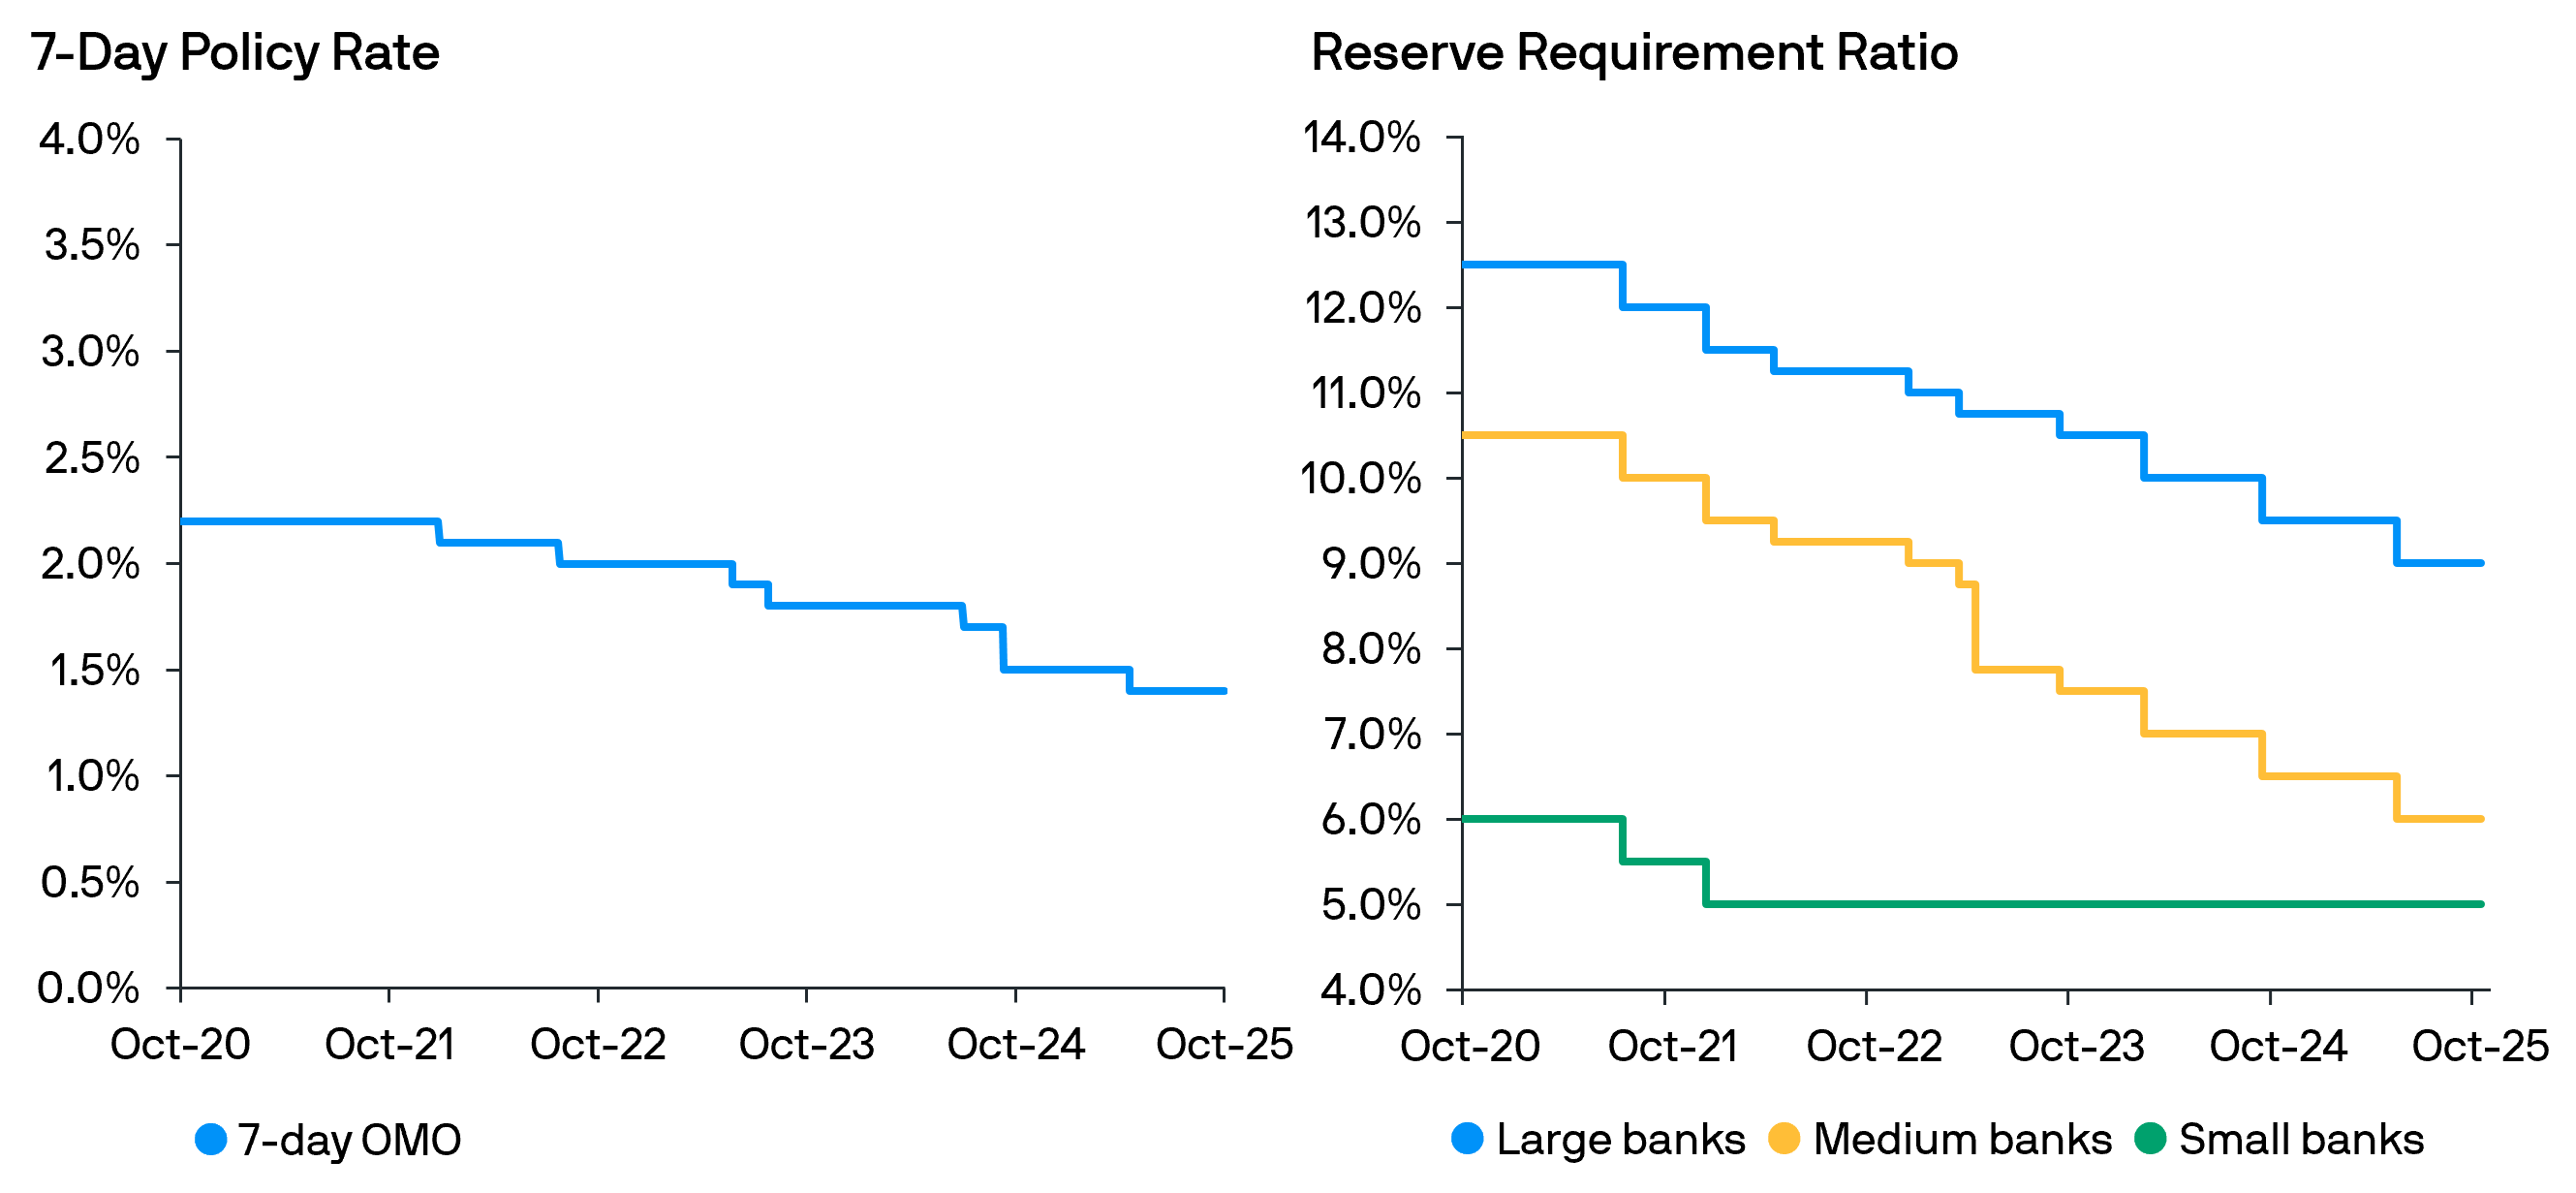
          Against this backdrop, the PBoC has maintained an accommodative stance. After cutting the Reserve Requirement Ratio (RRR), 7-day Open Market Operations (OMO), and Loan Prime Rate (LPR) in May, the central bank has kept rates unchanged, signaling a preference for stability and ample liquidity.


          Fig 1: Monetary policy has been on hold since May 2025.
           

          Source: PBoC, Bloomberg and J.P. Morgan Asset Management; data as at 21 October 2025.


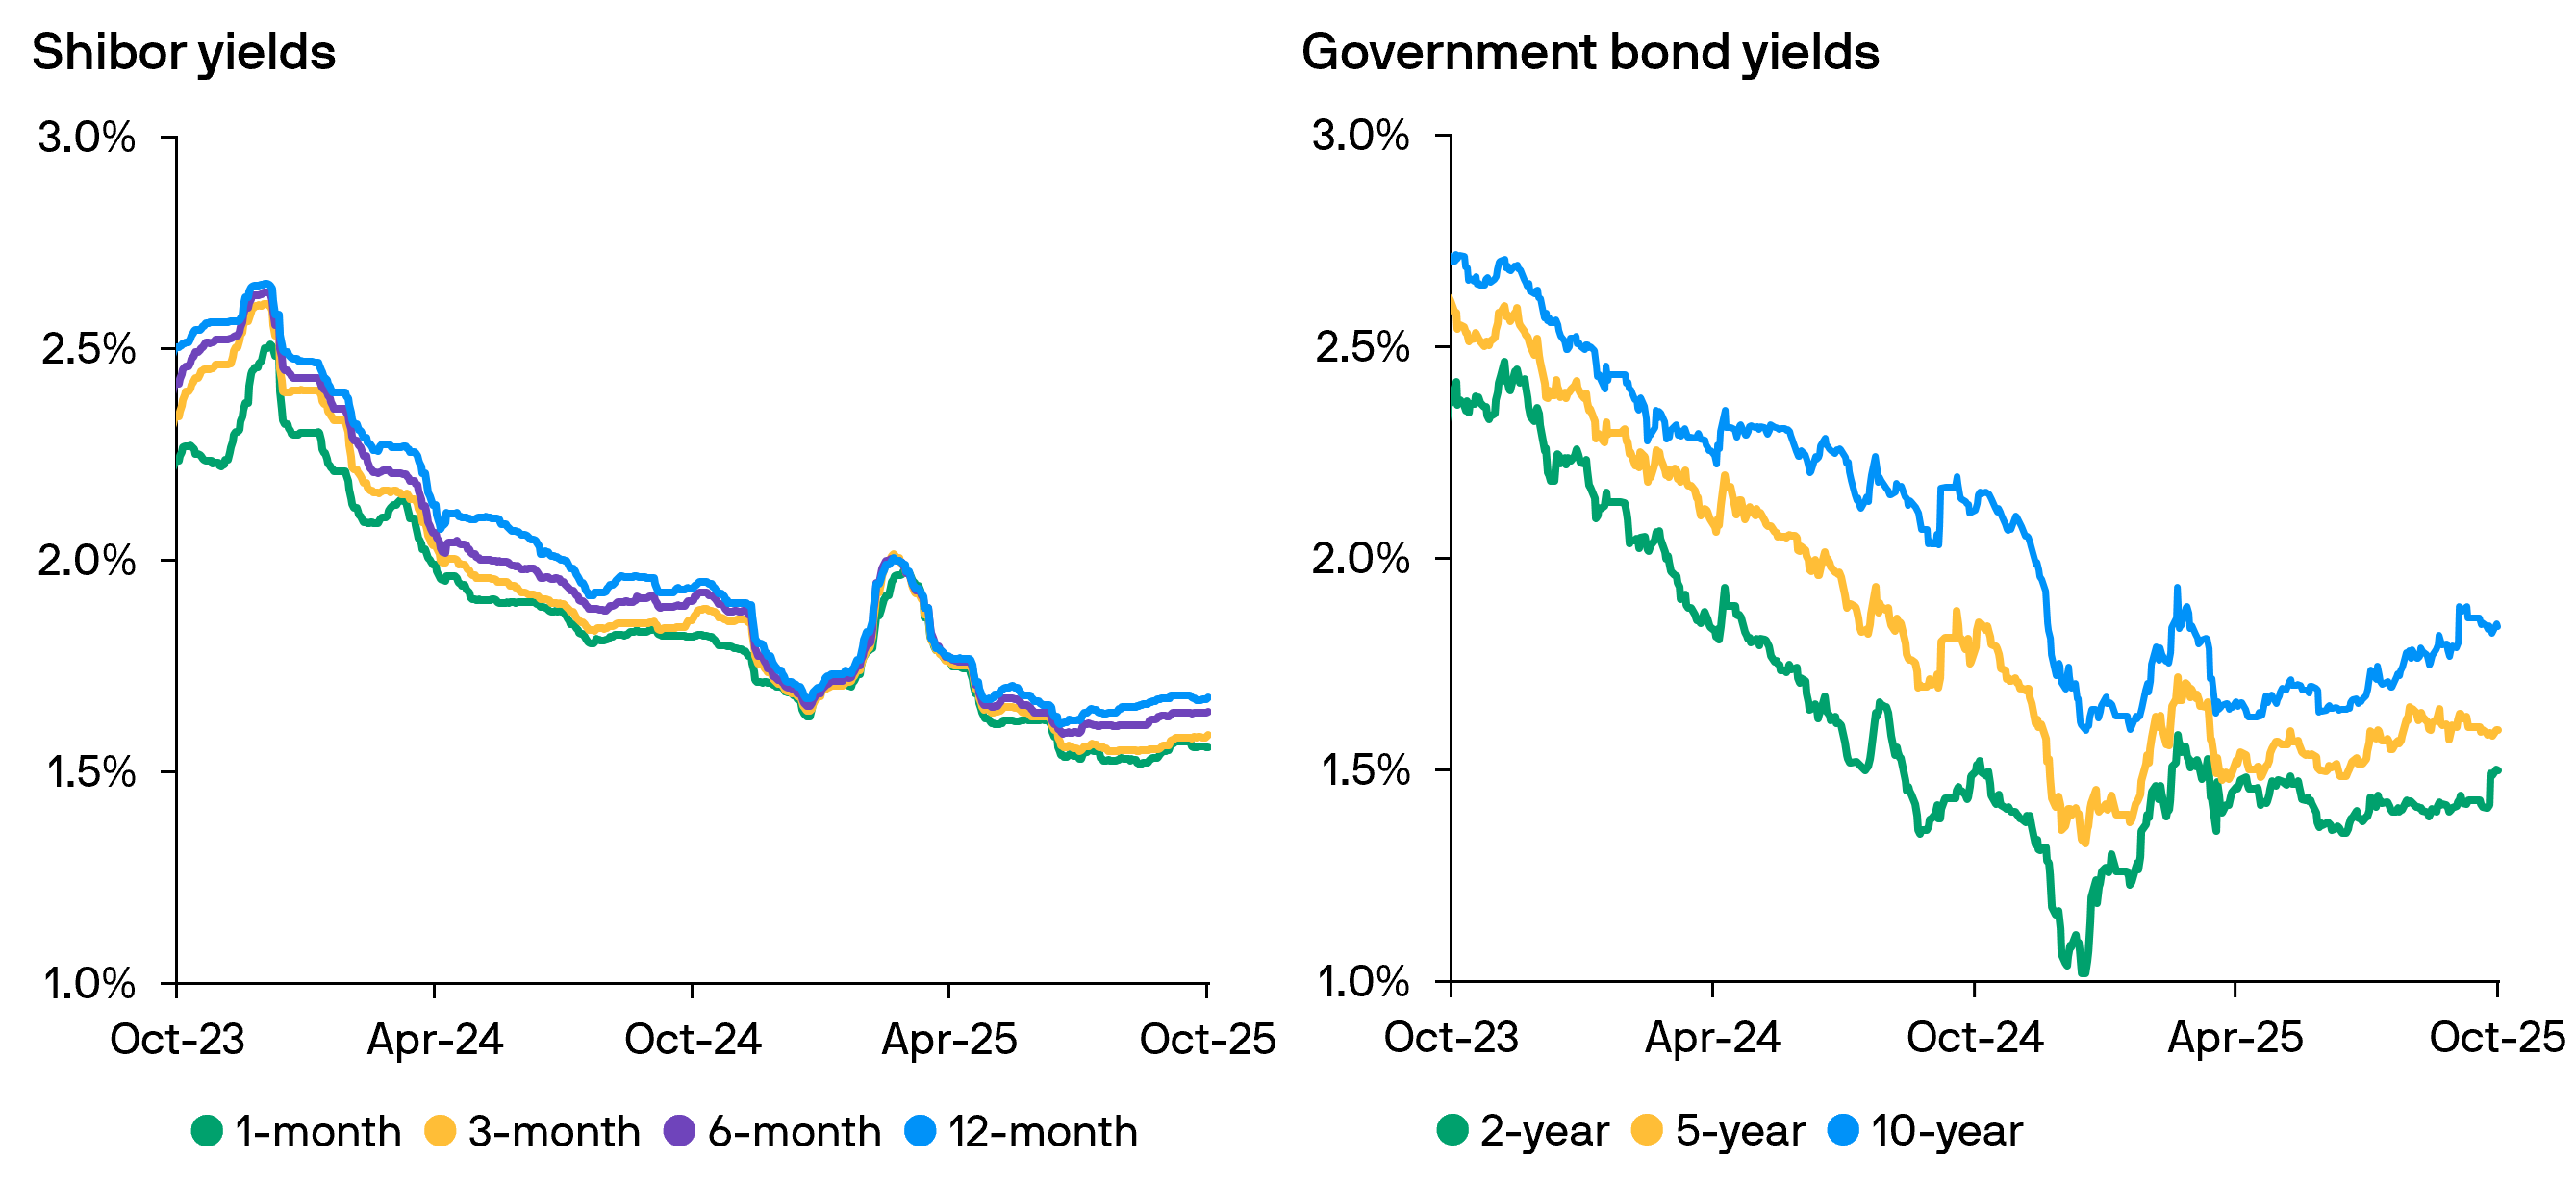
          Interest rates, which rose in the first quarter and declined in the second, have since stabilized, albeit at cycle lows.  With investors anticipating only incremental and targeted easing rather than broad-based stimulus, short-term rates have edged up and the yield curve has begun to steepen.


          Fig 2: Interest rates have declined but recently shown signs of stability.
           

          Source: Bloomberg and J.P. Morgan Asset Management; data as at 21 October 2025.


          Interest rate outlook – accommodative but cautious

          China’s economy is caught between strong industrial output and persistent weakness in consumption and investment. The PBoC’s cautious monetary policy reflects confidence in achieving growth targets, caution regarding upcoming political and trade developments, and an awareness of the limits of monetary stimulus.

          For RMB cash investors, money market fund yields remain near record lows but have stabilized.  They continue to present relatively attractive returns compared to declining commercial bank deposit rates. Tactical duration extensions, should the yield curve steepen further, may present opportunities to enhance returns. However, diversification and disciplined investment remain crucial amid ongoing market volatility.

          Diversification does not guarantee investment returns and does not eliminate the risk of loss.
          This information is generic in nature provided to illustrate macro trends based on current market conditions that are subject to change from time to time. This generic information does not take into account any investor’s specific circumstances or objectives and should not be construed as offer, research or investment advice.