logo
  • My collections
    View saved content and presentation slides
  • Log out
  • Insights

      Liquidity Insights

      • Liquidity Insights Overview
      • Global Liquidity Investment Outlook

        Global Liquidity Investment Outlook

      • Tokenization

        Explore the full whitepaper to learn how tokenized MMFs can transform your approach to cash management and position your organization at the forefront of digital finance.

      • Case Studies

        Read about companies with specific cash management challenges and the solutions when they worked with J.P. Morgan Asset Management.

      • Partnership with fintechs

        A focus on digital innovation and institutional liquidity solutions drive our dynamic partnership with fintech.

      • ESG Resources for Liquidity Investors

        We’ve created a clear, rigorous ESG process meets the many needs of liquidity investors.

      • Leveraging the Power of Cash Segmentation

        The most effective strategy incorporates a clear investment policy, well-defined goals and parameters for liquidity, quality and return.

      • Cash Investment Policy Statement

        How to write an investment policy statement for your organization

      Market Insights

      • Market Insights Overview
      • Eye on the Market

        Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

      • Guide to the Markets

        The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

      • Market Updates

        Read our weekly commentaries to get market insights that may help inform your investment strategy.

      • Podcasts

        Insights from Tai Hui, Chief Market Strategist, Asia, on what is happening in financial markets, from our Asia Pacific headquarters in Hong Kong.

      • Guide to Investing in Asia

        The Guide to Investing in Asia explores the diverse economies, markets and investment trends across Asia, including Japan, India, China and Southeast Asia.

      Portfolio Insights

      • Portfolio Insights Overview
      • Currency

        Our currency team provides solutions for clients, controlling risk using passive management strategies and generating returns by actively managing global currencies.

      • Fixed Income

        We highlight themes and implications from various fixed income teams to help guide your portfolio decisions.

      • Long-Term Capital Market Assumptions

        Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

      • Sustainable investing

        Sustainable Insights

      • Strategic Investment Advisory Group

        The Strategic Investment Advisory Group approaches today’s investment challenges with a global view across asset classes.

    • Resources
        • All Resources
        • MORGAN MONEY
        • Account Management & Trading
        • Global Liquidity Investment Academy
        • Announcements
      • About us

          About us

          Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

          • Overview
          • Spectrum: Our Investment Platform
          • Our Leadership Team
          • Diversity, Opportunity & Inclusion
        • Contact us
        • English
        • MORGAN MONEY LOGIN
          • My collections
            View saved content and presentation slides
          • Log out
        • Log in
        • MORGAN MONEY LOGIN
        Log in
        You are about to leave the site Close
        J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
        CONTINUE Go Back
        1. RBA: uncharted territory for unattainable goals

        • LinkedIn Twitter Facebook WhatsApp

        RBA: uncharted territory for unattainable goals

        10/10/2019

        Aidan Shevlin

        At the beginning of October, the Reserve Bank of Australia (RBA) cut its overnight cash rate by 25bps to a new record low (Fig 1a). The third rate cut in five months has effectively halved the central bank’s key policy rate – leaving the RBA in uncharted territory and one step closer to unconventional monetary policy to achieve potentially unattainable employment and inflation goals. The current trajectory of cash rates will have significant and far-reaching implications for local currency cash investors.

        Optimistic rate cuts:

        In recent speeches, RBA governor Philip Lowe struck an upbeat tone, noting the economy had reached a “gentle turning point”[1] helped by a combination of low interest rates, tax cuts, lower currency, infrastructure spending and housing market stabilization.

        Despite this professed optimism, the RBA still cut rates in October and remained dovish, committed to “ease monetary further if needed to support sustainable growth in the economy, full employment and the achievement of the inflation target”[2]. However, given current lack of macroeconomic drivers to achieve the central banks full inflation target of 4.5% and core inflation target of ≥2% (fig 1b), the probability of attaining either goal remains remote.

        Fig 1: The Australian central bank has cut base rates to a new record low; however, inflation and unemployment remain well below its target levels.
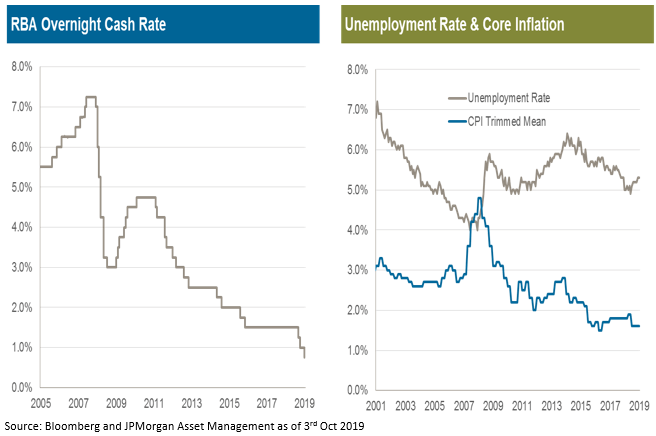
        The reality is more nuanced: While Australia is currently in its 28th year of economic expansion, gross domestic product (GDP) growth has slowed to a decade low; moreover the rising labour participation rate is offsetting almost 2-years of positive jobs creation and despite the recent recovery, house prices have fallen below their long term trend. Meanwhile, the long term slowdown and rebalancing of the Chinese economy will eventually weigh on exports – although short term Chinese infrastructure stimulus will benefit Australia’s commodity driven economy.

        Sluggish consumption and structural trends:

        Apart from weak global growth, the RBA’s other key domestic concern remains the lack of growth in domestic consumption – especially during a period of rising employment. However, this can partly be explained by job insecurity, muted wage growth and the high level of consumer indebtedness (Fig 2a). All these factors should still benefit from lower interest rates – suggesting that monetary policy remains an effective policy tool – provided commercial banks pass the rate reductions on to consumers.

        Fig 2: Debt to GDP continues to increase while wage growth remains sluggish. Globally, government bond yields have declined to new record lows.
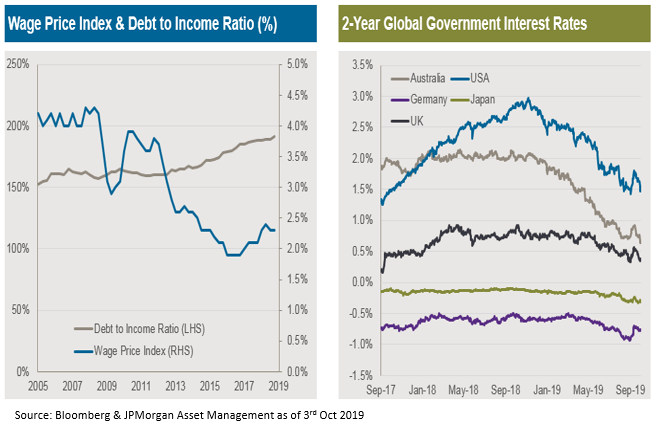
        Interestingly, for the first time, the RBA alluded to a new rationale for the latest rate cut. The structural shifts in global interest rates (Fig 2b) – which have fallen to record lows have also placed downward pressure on Australian interest rates. The central bank fears if it ignored the actions of major central banks, the “exchange rate would appreciate, which in the current environment would be unhelpful on terms of achieving both the inflation target and full employment”[3].

        The implications of sustain lower interest rates:

        The recent rate cuts, fiscal stimulus and continued Chinese commodities demand, suggest the modest Australian economic recovery is likely to endure. However, growing expectations of additional monetary policy easing by major central banks may force additional, unnecessary RBA rate cuts and even trigger unconventional monetary policy to restrain unwanted capital inflows and AUD appreciation.

        For Australian cash investors who are more familiar with high interest rates, steep yield curves and competitive deposit rates, the prospect of extremely low or even zero yields represents a significant challenge. These difficulties have been compounded by the Royal Commissions impact on commercial banks demand for deposits and APRA’s clarification on the definition of cash.

        Nevertheless there are several techniques developed and refined during the past decade of zero US interest rates which should help Australian corporate treasurers mitigate some of these complications. These include diversifying beyond deposits into money market funds and ultra-short duration funds, segmenting cash by liquidity requirements and identifying sectors and tenors that offer additional return for minimal reductions in liquidity and security.

        Although combining these three techniques will not fully offset the negative impact of RBA rate cuts on cash returns, they will allow treasurers to achieve a competitive return consistent with the objectives of capital preservation and maintaining a high degree of liquidity.

        [1] An Economic Update by Philip Lowe, 24th September 2019.

        [2] Statement by Philip Lowe, Governor: Monetary Policy Decision, 1st October 2019

        [3] An Economic Update by Philip Lowe, 24th September 2019

        • Monetary Policy
        • APAC
        • Central Banks

        RELATED ARTICLES

        China’s Interest Rate Pivot

        While China’s post-Covid-19 economic data is showing signs of normalization, the government’s focus on stability will have significant implications for monetary policy and interest rates

        Read more

        The PBoC – Rate Cuts and Policy Clarification

        The Peoples Bank of China recent policy actions help address the concerns that its policy response was lagging the aggressive actions taken by other central banks.

        Read more

        Singapore Dollar – no longer defying gravity

        The Singapore Dollar is no longer defying gravity – we discuss why and the implications for cash investors.

        Read more
        J.P. Morgan Asset Management

        • Investment stewardship
        • About us
        • Contact us
        • Privacy policy
        • Cookie policy
        • Cross-border business arrangements
        • Accredited Investor – Schedule 2 – Funds
        • Sitemap
        J.P. Morgan

        • J.P. Morgan
        • JPMorgan Chase
        • Chase

        READ IMPORTANT LEGAL INFORMATION. CLICK HERE >

        The value of investments may go down as well as up and investors may not get back the full amount invested.

        Copyright 2026 JPMorgan Chase & Co. All rights reserved.