

Global Market Strategist
Global Market Strategist
In Brief
- AI momentum remains strong, supported by robust earnings, rising compute demand, and massive infrastructure investment.
- Concentration risk is increasing, especially in the U.S. and Asian markets, making diversification across the broader AI value chain more important.
- Second-order opportunities may emerge in data centers, power, cooling, equipment, and APAC markets with distinct roles across semiconductors, infrastructure, and AI adopters.
Investors have favored artificial intelligence (AI)-related names throughout the year, and performance data justifies some of that enthusiasm. Hardware and semiconductors have been standout performers year-to-date. The momentum is real, earnings have been broadly supportive, and the competitive logic pushing capital into the sector remains intact. However, momentum has a way of compressing the margin for error. Benchmark concentration is now elevated across both the U.S. and some Asian markets. That concentration amplifies upside when earnings hold, but it can also accelerate losses when they do not. At this stage of the cycle, a more diversified allocation beyond mega-cap leaders, across the broader AI ecosystem and different regions, may help mitigate the risks of market concentration.
Demand is real, and monetization is the test
The AI buildout is happening on a massive scale. Hyperscalers are on track to spend approximately USD 700billion on AI infrastructure this year, directing capital across the physical building blocks of AI: advanced chips, high-bandwidth memory, servers, power systems, and new data centers. For these companies, falling behind in the AI race is viewed as a threat to their very survival. As a result, even the most established technology giants are aggressively ramping up capital expenditure.
However, the math is becoming less forgiving. In 2025 and 2026, capex is rising much faster than actual revenues, putting pressure on these companies’ available cash flows. At the same time, the stock market is pricing in years of future growth. The durability of the AI boom will therefore depend not only on monetization but also on efficiency. Can these companies grow revenues fast enough through cloud usage, enterprise software, and AI subscriptions to justify the massive investment? If revenues accelerate while costs decline and cash flow improves, the investments will be easier to justify. But if monetization disappoints or efficiency gains fail to materialize, companies may be forced to cut back on capex, creating a painful ripple effect across semiconductor and hardware stocks.
Beyond the obvious names: where the second-order opportunity sits
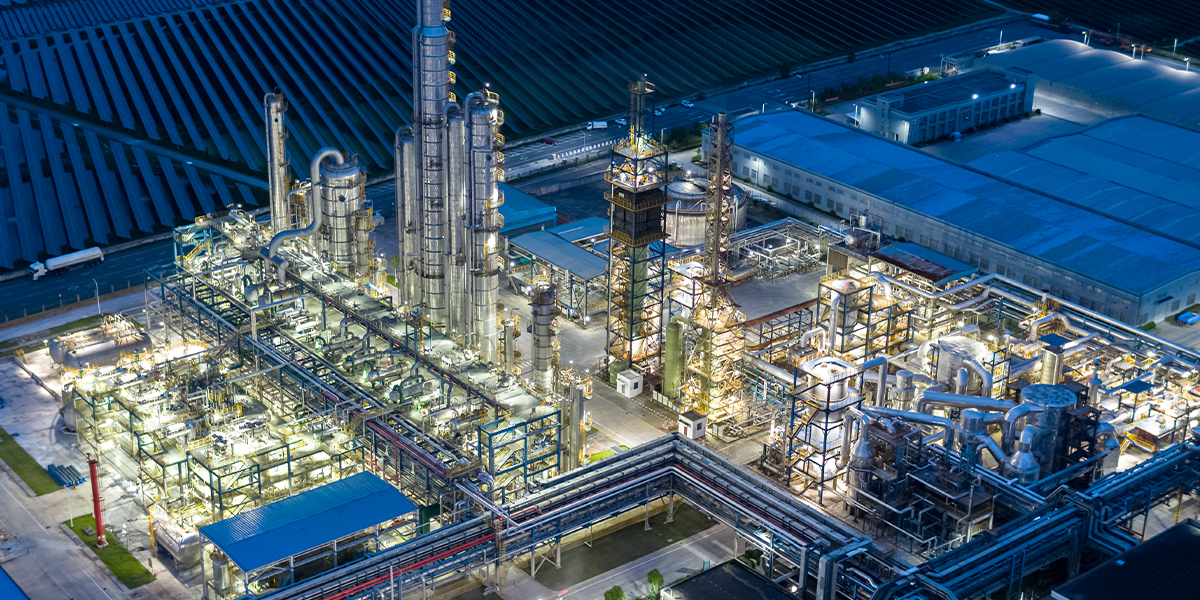
The most popular way to invest in AI is by owning the largest hyperscalers and leading semiconductor companies. While valid, this trade is already very crowded. The AI value chain extends well beyond the headline winners in hyperscalers and semiconductors. The next layer of potential beneficiaries may sit in the physical infrastructure required to support AI adoption. This includes data center real estate, engineering and construction firms, nuclear and renewable power providers, transmission networks, gas-powered electricity, cooling systems, and electrical components.
These areas may benefit from sustained investment as AI drives higher demand for compute, energy, and grid capacity. However, the landscape remains highly competitive, and rapid technology shifts could change which companies capture the most value, making selectivity essential.
A tour of AI in APAC region
South Korea and Taiwan are the heavyweights in manufacturing advanced chips and memory. They have seen significant stock market gains recently, but their markets are highly concentrated and have a high correlation with the U.S. technology cycle.
Japan offers leverage to semiconductor equipment, advanced materials, and robotics, which are critical picks-and-shovels for fabrication and industrial automation. This is supported by a broader reindustrialization dynamic.
China’s AI trajectory is increasingly independent, driven by self-sufficiency imperatives spanning models through applications in e-commerce, finance, healthcare, robotics, and industrial automation. China’s comparative advantage in more mature semiconductor nodes and its large domestic user base can reduce dependence on the most cutting-edge Western technology. Meanwhile, some Chinese technology companies are benefiting from the tech upcycle as clients redirect orders back to China while global AI demand strains capacity elsewhere.
Singapore is positioned as a regional hub for data center infrastructure and supply chain orchestration, offering a different angle: the physical and logistical backbone of the Asia-Pacific buildout.
India’s AI exposure is split between information technology (IT) services companies adopting AI to drive delivery automation and margin improvement, and a growing domestic adoption curve supported by a deep software talent base.
Investment implications
The structural case for AI remains supported by rising compute demand, expanding infrastructure needs, and broader enterprise adoption. However, portfolio outcomes may increasingly depend on how investors evaluate exposure across the AI value chain, including platform companies, semiconductors, data centers, power, cooling, equipment suppliers, and sector adopters. This framing can help investors assess where AI-related revenues, productivity gains, and cash-flow improvements may emerge over time, while recognizing that forecasts and market conditions are subject to change.
Geographically, Asia’s AI exposure may be better understood through distinct market and value-chain roles rather than as a single technology allocation. South Korea and Taiwan are closely tied to advanced semiconductors and memory; Japan is exposed to equipment, materials, and robotics; China’s AI cycle may reflect a more domestically driven ecosystem with distinct opportunities and risks; Singapore is linked to data center and supply chain infrastructure; and India combines IT services with domestic adoption.