Investment themes for emerging market debt – Q3 2026
- Resilient growth and developed market (DM) diversification keep EMD backdrop firmly supportive
- A manageable inflation shock – this is not 2022
- Central banks are calibrating, not cycling – real-rate buffers do the heavy lifting
- Fundamentals stay solid – upgrades roll on, defaults stay away
- Positioning and scenarios: Credit for core carry and local to outperform
-
Resilient growth and DM diversification
-
A manageable inflation shock
-
Central banks are calibrating, not cycling
-
Fundamentals stay solid
-
Positioning and scenarios
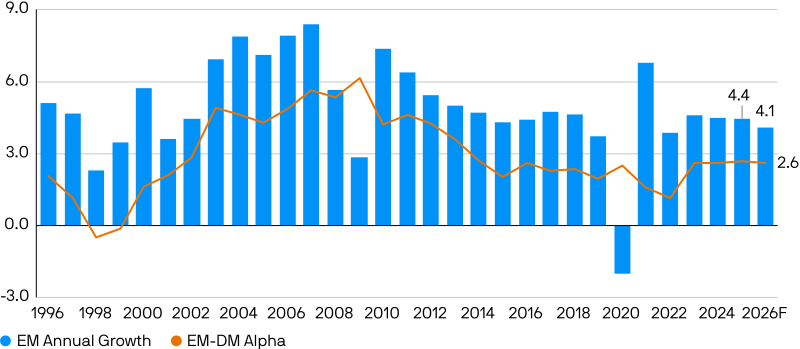
Resilient growth, a manageable inflation shock and diversification away from developed markets build a supportive backdrop for EMD. Emerging market (EM) 2026 growth holds at 4.1% (as at June 2026), unchanged from last quarter, but an improvement in the EM– DM growth alpha to 2.6% – driven largely by weaker European growth – means the alpha remains around the 2015-2019 average. We watch for an EM–US growth contraction in the first half of 2026 before a recovery in the second half.
EM growth is broad-based, with Latin America and emerging Europe set to recover while Asia stabilises into the second half, underscoring the diversification benefit offered by emerging markets compared to a slowing DM bloc.
China remains a steady anchor, with 2026 GDP growth upgraded slightly to 4.6% on the back of fixed asset investment and exports, as well as structural resilience evident through the energy shock.
Key risks to watch over the next six months include US exceptionalism and potential rate hikes from the Federal Reserve, a more extended and impactful energy crisis, and politics in both emerging and developed markets.
Resilient growth and DM diversification keep EMD backdrop firmly supportive
EM annual growth and EM–DM alpha (%)
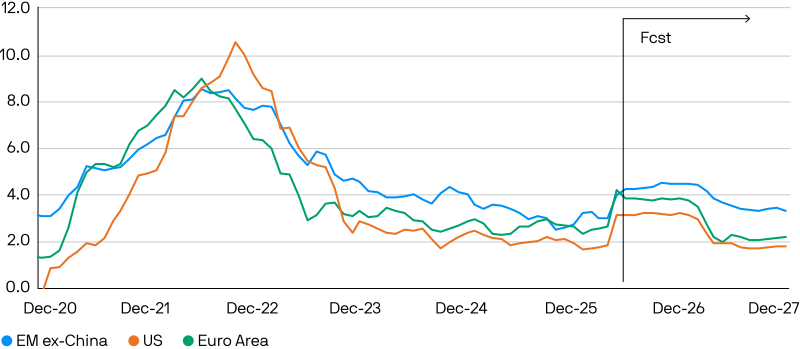
EM inflation has risen to roughly 3.8% from 2.8% pre-crisis — about 30% of the size of the 2022 shock, and mostly concentrated in Asia.
Upside risks include second-round effects and El Niño, with nuanced, country-specific impacts, but demand-side pressures are limited and inflation expectations remain anchored. Energy prices have already retraced meaningfully from their peaks – Brent is down 34%, European natural gas down 32% and US natural gas down 57% from 2026 highs – limiting the pass-through to EM inflation. While a resolution to the Strait of Hormuz closure is still pending, the permanent and temporary offsets have already produced a more moderate shock than feared.
The impact is also highly regional: Asia is by far the worst affected, while emerging Europe and Latin America are far more contained. Crucially, there is no demand-side angle, as there was in 2022, with labour markets gradually cooling and inflation expectations not moving out of control.
A manageable inflation shock – this is not 2022
We are through the worst of the inflation increase (%)
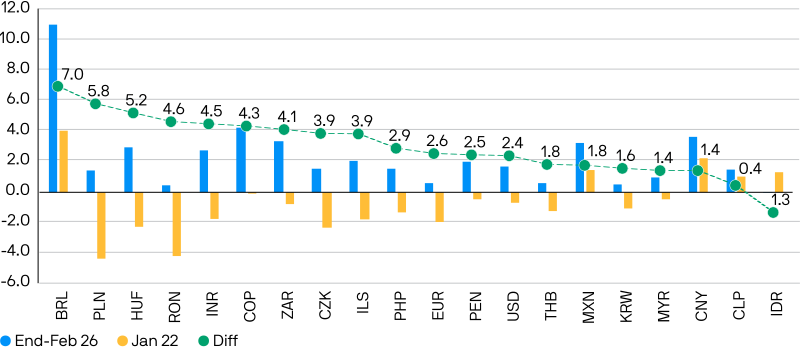
Emerging market real rates provide a buffer of more than 100 basis points (bps) vs. 2022, so we do not expect a full hiking cycle. Most rate cuts are on pause, but some hawkish central banks are being proactive with “maintenance” hikes. The bulk of the EM central banks we track are either expected to be on hold or deliver modest 25bps–50bps moves in the second half of 2026, rather than launching a full cycle. Although a handful of hawks (such as the Czech Republic and South Africa) are hiking, while others (such as Hungary) still have room to cut. This dispersion is the opportunity, as it lets us be long duration where central banks have the willingness and ability to ease, and more tactical where fiscal or political risks loom.
Solid fundamentals, supported by high real policy rates relative to developed markets, have historically led EMD to perform well in Federal Reserve hiking cycles, driven by growth and productivity, rather than inflation and fiscal, fears. Brazil stands out as an outlier on a forward-looking basis, with the highest real rates, followed by Colombia, South Africa and Hungary.
Central banks are calibrating, not cycling: Alpha opportunity in EM rates
Real policy rate comparison vs. 2022 (%)
EM sovereign fundamentals remain solid, with limited default risk even under an extended oil-shock scenario. There were no defaults in 2025 and risks for 2026 are limited.
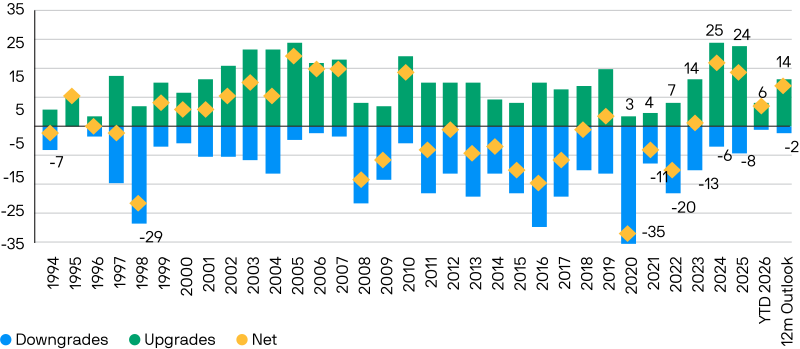
Upgrades continue to exceed downgrades: recent single-agency upgrades include Aruba, Lithuania, the Bahamas, Argentina, Ghana, Bermuda, Nigeria, the Maldives and South Africa, with further upgrades expected across Benin, Bulgaria, Costa Rica, India, Morocco, Turkey and Zambia, among others.
The median EM picture is reassuringly stable: public debt is rising only slightly (to around 61% of GDP), current accounts are contained and fiscal balances remain healthier than pre-pandemic.
Default risk stays low and idiosyncratic rather than systemic across the index. Stresstesting external financing needs shows that most countries keep their financing gaps below 100% of reserves even under a severe oil-shock scenario, with some oil exporters actually benefiting.
Fundamentals stay solid — upgrades roll on, defaults stay away: Support for EM credit to grind tighter
Upgrades continue to exceed downgrades in 2026
EM sovereigns rating changes (middle M/S/F)
Source: J.P. Morgan Asset Management, International Monetary Fund, Bloomberg. Rating outlook does not include changes between CC/C/D as often temporary/technical. All listed face outstanding as of 8 June 2026. 12moF = % face of names with high default probability. The risk designation high refers to a probability of default >40%, medium refers to 10-40% probability of default, and low refers to a probability of default between 5-10%. Ukraine GDP warrants defaulted in 2025 but sovereign bonds in the index did not default.
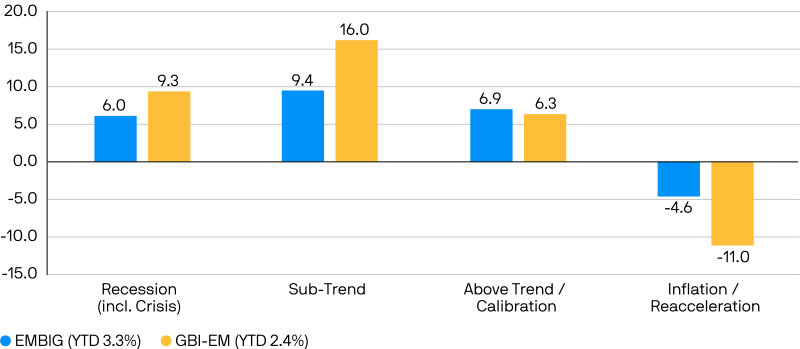
We see probability-weighted returns of roughly 2%–5% for the rest of 2026. Our base “Above Trend” scenario features spread and high-yield compression alongside rangebound core rates, while the worst outcomes occur in a re-acceleration / inflation regime with higher US Treasury yields and a stronger US dollar. Notably, our constructive base case is underpinned by the fact that EMD has historically delivered strong returns in Federal Reserve hiking cycles characterised by growth and productivity, rather than inflation and fiscal, fears.
On positioning, in local markets we are overweight duration on the reversal of centralbank pricing following the Iran shock, and we like EM currency (EM FX) and frontier exposure funded from a diversified basket of DM FX.
In sovereigns we remain overweight select high yield and underweight investment grade. In corporates, fundamentals and technicals remain strong, and we continue to add on opportunities in primary markets amid volatility.
Positioning and scenarios: Credit for core carry and local to outperform
2026 return scenarios (%)