logo
  • My collections
    View saved content and presentation slides
  • Log out
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration
      • European domiciled products

      Solutions

      • Cash Strategies
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy

      Fund Information

      • Regulatory Updates
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook

          Global Liquidity Investment Outlook

        • Tokenization

          Explore the full whitepaper to learn how tokenized MMFs can transform your approach to cash management and position your organization at the forefront of digital finance.

        • Cash Cookbook

          The Cash Cookbook, your guide to cash and liquidity management success, helps you choose the right liquidity solution for your needs and risk tolerance.

        • Case Studies

          Read about companies with specific cash management challenges and the solutions when they worked with J.P. Morgan Asset Management.

        • Partnership with fintechs

          A focus on digital innovation and institutional liquidity solutions drive our dynamic partnership with fintech.

        • ESG Resources for Liquidity Investors

          We’ve created a clear, rigorous ESG process meets the many needs of liquidity investors.

        • Leveraging the Power of Cash Segmentation

          The most effective strategy incorporates a clear investment policy, well-defined goals and parameters for liquidity, quality and return.

        • Cash Investment Policy Statement

          How to write an investment policy statement for your organization

        Market Insights

        • Market Insights Overview
        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Market Updates

          Read our weekly commentaries to get market insights that may help inform your investment strategy.

        • Podcast: Markets Explained

          Signal or noise? In this weekly podcast, Karen and Hugh digest the newsflow in an increasingly tumultuous world and work out what it means for global investors.

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency

          Our currency team provides solutions for clients, controlling risk using passive management strategies and generating returns by actively managing global currencies.

        • Fixed Income

          A complex mix of monetary, credit and fiscal forces is changing the bond landscape. Discover how flexible fixed income approaches can seek returns, income and resilience.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Sustainable investing

          We believe that ESG considerations can play a critical role in a long-term investment strategy.

        • Strategic Investment Advisory Group

          The Strategic Investment Advisory Group approaches today’s investment challenges with a global view across asset classes.

      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
        • About us

            About us

            Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

            • Overview
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Our Leadership Team
            • Our Commitment to Research
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My collections
              View saved content and presentation slides
            • Log out
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back

          <p>Investment themes for emerging market debt Q1 2026</p>

          Investment themes for emerging market debt in 5 key charts.

            1. Home
            2. Insights
          1. Portfolio Insights Overview
          2. Fixed Income Insights | Portfolio Insights

          Investment themes for emerging market debt - Q1 2026

          • Positive backdrop for EMD assets extended by economic resilience and Fed cuts
          • Long EM rates with more differentiation along fiscal and political risks
          • EMFX supported by carry and lower volatility
          • Credit valuations driven tighter by supportive fundamentals and technicals
          • Risks: US inflation and fiscal policy, recession, AI, geopolitics
          • Positive backdrop for EMD assets extended by economic resilience and Fed cuts

          • Long EM rates with more differentiation along fiscal and political risks

          • EMFX supported by carry and lower volatility

          • Credit valuations driven tighter by supportive fundamentals and technicals

          • Risks

          Emerging market debt (EMD) had a phenomenal run in 2025. Corporate markets returned 8.7%, sovereigns added 14.3% and local currency bonds were up 19.3%. Investors are now asking whether this performance can continue.

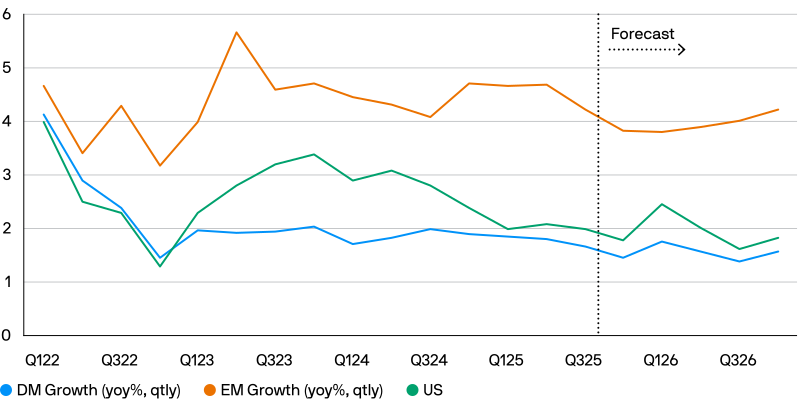
          Fundamentals suggest yes. Economic growth is supportive, with just a slight slowdown expected from 4.3% in 2025 to 4.0% in 2026. Although slightly lower, the emerging market (EM)-developed market (DM) growth alpha should remain healthy at 2.4% in 2026, similar to pre-pandemic trends. Emerging markets have navigated and adapted to tariffs in 2025 and are in a strong position going into 2026.

          All things equal, emerging markets should be on track to deliver strong returns in 2026.

          Emerging market growth is far above developed markets
          jpm-investment-themes-for-emerging-exhibit-1
          Source: Bloomberg, J.P. Morgan Asset Management; data as of December 2025. Opinions, estimates, forecasts, projections and statements of financial market trends are based on market conditions at the date of the publication, constitute our judgment and are subject to change without notice. There can be no guarantee they will be met.

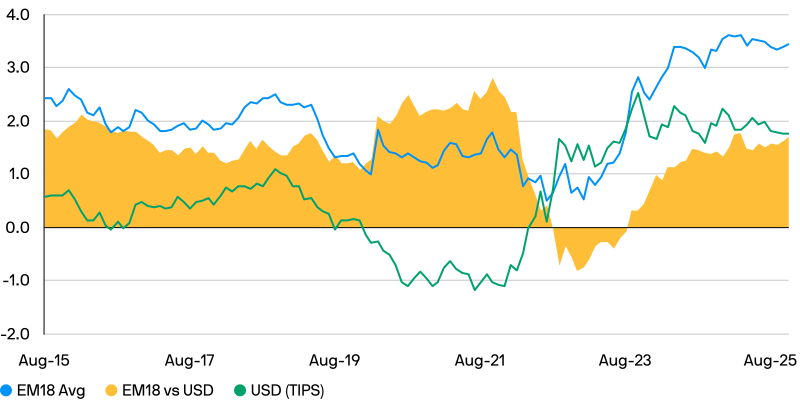
          Inflation has reduced significantly over 2025 for EM countries and is now back to target levels. Rates, however, remain high, as we estimate that EM central banks are only halfway through their cutting cycle. Combining these elements leads to high real rates. We are long duration in the countries where we believe central banks will show the most willingness and ability to cut policy rates, while being more tactical in those countries with upcoming fiscal and political risks.

          EM local currency debt markets have been undergoing a structural change over many years. EM policy frameworks have substantially improved with the number of EM countries with inflation targeting regimes and fiscal rules doubling over the past 15 years. In addition, the domestic investor base continues to grow and now represents over 100% of GDP in many EM countries. In turn, the risk associated with EM local currency debt is reduced by the accumulation of domestic assets by domestic investors.

          Real yields remain compelling in local currency

          %
          jpm-investment-themes-for-emerging-exhibit-2
          Source: Bloomberg, J.P. Morgan Asset Management; data as of December 2025.

          A concern for many investors when considering EMD is the risk associated with EM foreign exchange (EMFX). In 2025, EMFX has added considerably to portfolios as the dollar weakened following Liberation Day. Putting this move in context, however, highlights that there may be further potential for appreciation in EMFX over the coming years given that currencies are still cheap.

          With this appreciation, we have seen EMFX volatility converge with the volatility of DMFX. While this convergence may seem unintuitive, on a longer-term historical basis, it’s not atypical.

          The flow of capital could reasonably be expected to slow due to increased tariffs. However, world trade volumes have reached new historical highs led by strong EM exports despite declining US imports. Investor capital flows have been strong into EM local currency debt markets over 2025 and we expect more investors to add to the asset class in 2026 following the strong returns this year. Even when accounting for the inflows this year, international investor allocations are still near historical lows with the door open for future investments.

          EMFX valuations still cheap despite recent appreciation

          jpm-investment-themes-for-emerging-exhibit-3
          Source: Bloomberg, J.P. Morgan Asset Management as of 30 November 2025 for the period 2012 to 2025.

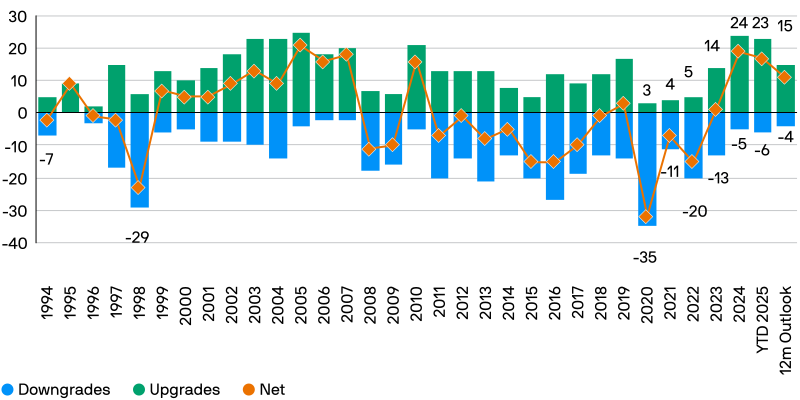
          We predict that EM Sovereign fundamentals will continue improving in 2026 following a strong 2025. EM countries reported lower deficits and zero defaults in 2025, continuing the trend of zero defaults in 2024. In 2026 we predict limited defaults with 0.4% of the index at risk. Strong fundamentals are being reflected in upgrades from credit rating agencies.

          EM corporate fundamentals are more stable but present sector divergence, which provides the possibility for alpha generation. We expect mid-single digit EBITDA growth, stable leverage and a small increase in defaults due to idiosyncratic issues.

          While valuations may seem tight based on historical data, we find they are justified by these strong fundamental factors and technicals. We predict corporate markets will have the fifth consecutive year of negative net supply. Meanwhile, sovereign issuance is expected to be driven by investment grade issuers, and high yield issuance is expected to also be negative on a net basis. As such, current spread levels are supported by demandsupply technical and further inflows could lead to spread tightening.

          Sovereigns upgrades continue to exceed downgrades in 2026

          EM Sovereigns Rating Changes (Middle M/S/F)
          jpm-investment-themes-for-emerging-exhibit-4
          Source: Bloomberg, IMF, J.P. Morgan Asset Management; Rating outlook does not include changes between CC/C/D as often temporary/technical.

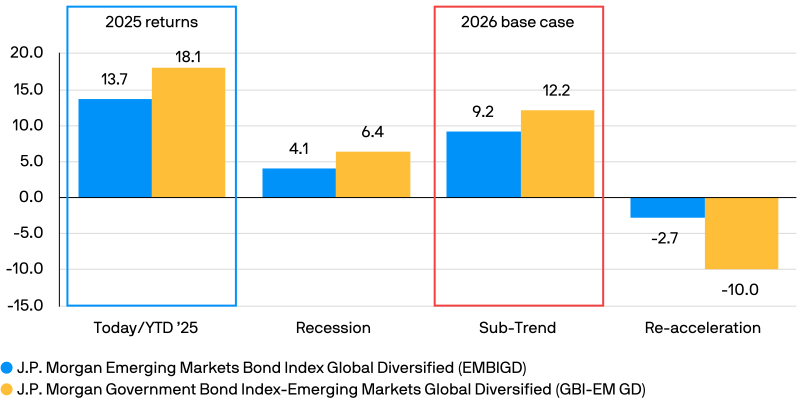
          We break down our market environment scenarios into three categories: recession, sub-trend growth, and re-acceleration. Our central scenario of sub-trend growth has the highest upside, with returns between 9% and 12% for sovereign and local markets. However, our expectations of tail risk scenarios are increasing.

          Re-acceleration is the most negative scenario for EMD, with increasing inflation leading to a stronger US dollar and central banks not being able to cut rates as expected, which would impact local currency debt. Improving quality combined with a spread buffer leads to less negative returns in sovereign markets.

          A recessionary market environment would deliver positive returns in EMD. Sovereigns would benefit from US policy rate cuts while spreads in the investment grade portion of the market would be expected to remain contained and act as a ballast for the market. In local debt markets, high policy rates give EM central banks capacity to significantly cut rates, offsetting US dollar strength.

          Probability-weighted, we see positive returns for both sovereign and local markets in 2026, of around 6%.

          2026 return scenarios
          jpm-investment-themes-for-emerging-exhibit-5
          Source: Bloomberg, J.P. Morgan Asset Management as of 4 December 2025.