

Q4 2026
The global stock market has remained resilient despite several headwinds this year. Many of those downside risks remain pressing, including ongoing geopolitical conflict and the associated rise in energy prices, a hawkish policy shift by the major central banks, government bond yields flirting with fresh cycle highs, and renewed technology sector volatility. Yet, the global economic backdrop has so far held firm amid ongoing public- and private-sector spending, and corporate earnings are booming. The stock market’s ascent has therefore remained intact, but taking a selective approach will be important in navigating the various moving parts.
-
Corporate earnings growth and expectations remain robust
-
Equity valuations have de-rated this year
-
Tracking end-user demand is critical for the AI trade
-
Index-level concentration continues to build
-
Looser fiscal policy may still provide opportunities for cyclical stocks
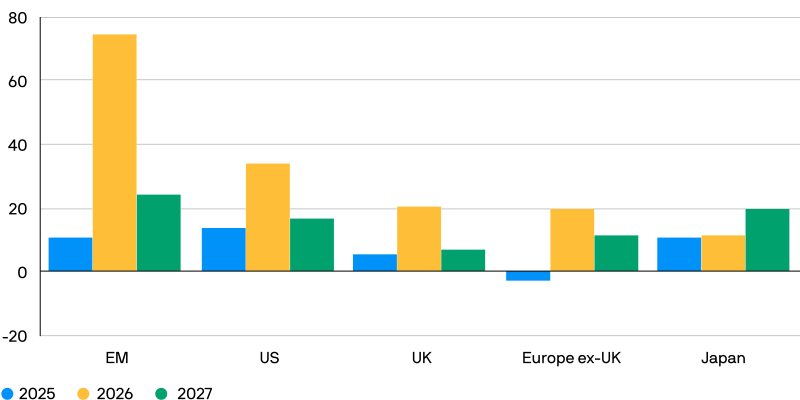
Global earnings per share (EPS) growth still looks exceptional this year, on track for its fastest pace of expansion since 2021. Technology-related earnings in particular have soared amid the artificial intelligence (AI) data centre build-out, while energy sector earnings have also surged. Emerging markets are leading the charge, with EPS expected to grow by more than 70% in 2026, largely reflecting Korea and Taiwan’s critical role in the AI supply chain, while US EPS growth remains strong. Promisingly, EPS growth has also been running in double-digit territory in the other major stock market regions. This robust earnings trend is forecast to continue in 2027, though the consensus expects the EPS growth gap between the technology and non-technology segments of the market to narrow.
Consensus estimates for earnings per share growth
% change year on year
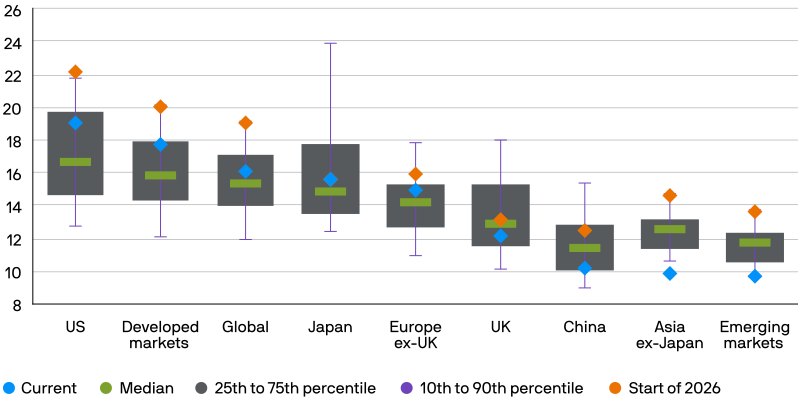
There has been a broad-based valuation de-rating across stock markets this year. Forward-looking valuation metrics, such as 12-month forward price-to-earnings (P/E) ratios, have declined in almost all the major equity regions, as the rise in near-term earnings growth expectations has largely exceeded stock price gains. This has been most evident in regions with high technology exposure, such as the US and Asia ex-Japan, where earnings growth has been strongest. While valuations are still not outright ‘cheap’ in some regions, at least relative to historical averages, investors should nonetheless assess whether the widespread de-rating offers an attractive entry point into certain segments.
12-month forward P/E ratios
x, multiple, percentiles and median since 2000
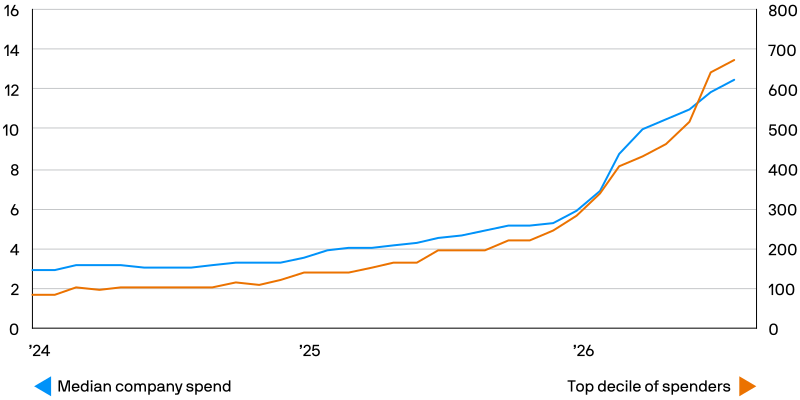
There is a wide range of metrics to monitor when allocating funds to various parts of the AI value chain. For example, if capital expenditure (capex) estimates continue to rise, semiconductor earnings might receive a boost in the near term, but the so-called ‘hyperscalers’ may face a higher hurdle to achieving a satisfactory return on investment. Meanwhile, US-China competition at the large language model (LLM) level may not help the case for those US AI providers looking to list on public markets, but it could offer more choice and possibly greater utility for non-technology businesses. Each stage in the technology supply chain clearly faces different hurdles, but end-user demand remains the most crucial factor in the overall AI trade. Investors should thus watch final demand metrics, such as US business spending on AI models, which has continued to trend higher over the past quarter.
AI spending by US businesses
USD, monthly spend per employee
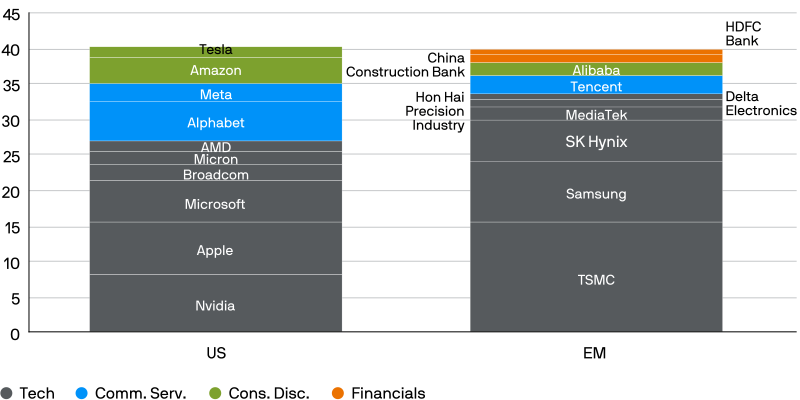
Despite recent technology stock volatility, concentration risk remains elevated at the index level. In the S&P 500, 10 technology-focused companies account for roughly 40% of the entire index’s market capitalisation. While their business lines are somewhat diversified, they all have substantial exposure to the AI data centre build-out. Strikingly, in the MSCI Emerging Markets benchmark, just three semiconductor-related companies account for around 30% of the entire index. These companies’ fundamentals could of course remain robust in the near term, but this concentration nevertheless highlights the case for both greater diversification and an active approach within equities.
Top 10 companies in US and EM equity benchmarks
%, index weight
Source: LSEG Datastream, MSCI, S&P Global, J.P. Morgan Asset Management. US: S&P 500; EM: MSCI Emerging Markets. Index weights are as of the end of the previous calendar month. Guide to the Markets - UK. Data as of 30 September 2026.
Government spending has ramped up in the post-pandemic world. That trend is likely to persist in Europe in particular, given the large infrastructure package in Germany and the defence spending push across the wider euro bloc. While cyclical stocks outside the technology sector face near-term challenges, such as higher energy prices and interest rates, stronger levels of government spending should boost economic growth prospects over the medium term. If investors expect that some of those cyclical headwinds will dominate in the near term, then value- or defensive-oriented market segments, such as UK large caps, may provide better opportunities.
Government investment
%, annualised change over period
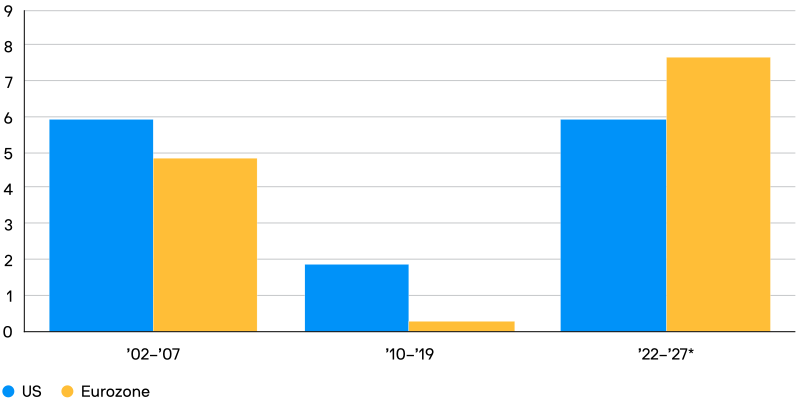
Source: OECD, J.P. Morgan Asset Management. *Includes OECD forecasts. Eurozone is a GDP-weighted average of France, Germany, Italy and Spain. Guide to the Markets - UK. Data as of 30 September 2026.
Conclusion
The corporate earnings backdrop has remained healthy over the past quarter, while there has been a broad-based valuation de-rating across equity regions this year. This may provide an attractive entry opportunity, though selectivity remains important amid technology sector volatility and concentration risk at the index level. While the AI trade will remain in focus, allocations to less AI-centric regions and sectors may also offer value. Cyclical stocks in regions with large fiscal spending plans may benefit disproportionately, while a worsening of some of the headwinds noted above may strengthen the case for allocating to higher-quality, defensive segments of the stock market.