logo
  • My Collections
    View saved content and presentation slides
  • Log out
  • Products

      Funds

      • Performance & Yields
      • Liquidity
      • Ultra-Short
      • Short Duration
      • European domiciled products

      Solutions

      • Cash Strategies
      • Cash Segmentation
      • Separately Managed Accounts
      • Managed Reserves Strategy

      Fund Information

      • Regulatory Updates
    • Insights

        Liquidity Insights

        • Liquidity Insights Overview
        • Global Liquidity Investment Outlook

          Global Liquidity Investment Outlook

        • Cash Cookbook

          The Cash Cookbook, your guide to cash and liquidity management success, helps you choose the right liquidity solution for your needs and risk tolerance.

        • Case Studies

          Read about companies with specific cash management challenges and the solutions when they worked with J.P. Morgan Asset Management.

        • Partnership with fintechs

          A focus on digital innovation and institutional liquidity solutions drive our dynamic partnership with fintech.

        • ESG Resources for Liquidity Investors

          We’ve created a clear, rigorous ESG process meets the many needs of liquidity investors.

        • Leveraging the Power of Cash Segmentation

          The most effective strategy incorporates a clear investment policy, well-defined goals and parameters for liquidity, quality and return.

        • Cash Investment Policy Statement

          How to write an investment policy statement for your organization

        Market Insights

        • Market Insights Overview
        • Eye on the Market

          Explore Eye on the Market, timely commentary that offers views on the economy, markets, and investment portfolios by Michael Cembalest.

        • Guide to the Markets

          The J.P. Morgan Guide to the Markets illustrates a comprehensive array of market and economic histories, trends and statistics through clear charts and graphs.

        • Market Updates

          Read our weekly commentaries to get market insights that may help inform your investment strategy.

        • Podcast: Markets Explained

          Signal or noise? In this weekly podcast, Karen and Hugh digest the newsflow in an increasingly tumultuous world and work out what it means for global investors.

        Portfolio Insights

        • Portfolio Insights Overview
        • Currency

          Our currency team provides solutions for clients, controlling risk using passive management strategies and generating returns by actively managing global currencies.

        • Fixed Income

          A complex mix of monetary, credit and fiscal forces is changing the bond landscape. Discover how flexible fixed income approaches can seek returns, income and resilience.

        • Long-Term Capital Market Assumptions

          Our Long-Term Capital Market Assumptions (LTCMAs) deliver forward-looking return, volatility and correlation estimates for 200+ asset and strategy classes in 20+ base currencies.

        • Sustainable investing

          We believe that ESG considerations can play a critical role in a long-term investment strategy.

        • Strategic Investment Advisory Group

          The Strategic Investment Advisory Group approaches today’s investment challenges with a global view across asset classes.

      • Resources
          • Overview
          • MORGAN MONEY
          • Account Management & Trading
          • Global Liquidity Investment Academy
          • Announcements
        • About us

            About us

            Backed by $4.6T in assets, we harness our active edge to deliver timely ideas and actionable insights that empower investors to achieve what matters most.

            • Overview
            • Diversity, Opportunity & Inclusion
            • Spectrum: Our Investment Platform
            • Our Leadership Team
            • Our Commitment to Research
          • Contact us
          • English
          • MORGAN MONEY LOGIN
            • My Collections
              View saved content and presentation slides
            • Log out
          • Log in
          • MORGAN MONEY LOGIN
          Log in
          You are about to leave the site Close
          J.P. Morgan Asset Management’s website and/or mobile terms, privacy and security policies don't apply to the site or app you're about to visit. Please review its terms, privacy and security policies to see how they apply to you. J.P. Morgan Asset Management isn’t responsible for (and doesn't provide) any products, services or content at this third-party site or app, except for products and services that explicitly carry the J.P. Morgan Asset Management name.
          CONTINUE Go Back
          1. Chinese property - a paradigm shift

          • LinkedIn Twitter Facebook WhatsApp

          Chinese property - a paradigm shift

          19-11-2019

          Sunny Tam, CFA

          Over the past decade, Chinese property and related industries contributed ~15-20% of China’s GDP. Over the same period, the market value of the housing stock ballooned from 92% of GDP in 2009 to 178% of GDP in 2019. The Chinese government appears to be very determined to prevent further rapid growth in property prices and has further tightened credit availability to the sector this year. The operating environment could likely get more challenging in 2020, and we expect more divergence in developers’ performance going forward. Chinese property is one of the largest sectors in the Asia high yield bond universe, and is often considered as one of the “safer” sectors by investors, given limited default cases so far (only two defaults in the USD bond space in the past 10 years) and generally good asset coverage for most companies; however, the perception could change if defaults start to pick up. Some issuers may grow stronger as they consolidate the market, while the weaker ones get eliminated.

          Policies now targeting demand side and financing side

          Historically we have gone through many policy cycles for the Chinese property sector, but we think the key difference this time is that the government clearly stated that they will no longer use the property sector as a short term economic tool; and credit tightening is across the board, from construction loans, to bond issuance, and even mortgage loans. It is less likely that we would see policy easing anytime soon, and new regulations are virtually capping the total debt available to the sector. The operating environment has changed materially. Overall property sales appears to have reached its peak and is plateauing, if not gradually declining (volume growth is flat, price growth is being curbed).

          Operational performance would likely diverge going forward

          When markets perform well, developers can use higher growth to offset impacts of higher leverage or higher funding costs. As long as property sales do well, a lot of the weaker/smaller companies can still survive. However with the tighter mortgage loan availability, cash collection rate from property sales will likely be lower than before. As a result, the construction loans required to support the same scale will be higher yet at the same time construction loans are now harder to get. Also, with more stringent rules on bond issuances (basically only refinancing is allowed), developers would have less cash available to buy land too. Some developers may start to focus more on margins, and gradually deleverage during this period, yet others may struggle to survive. Current land bank quality and execution capability of management are also important factors determining how they would perform in the coming years, and this is not always fully captured in credit ratings.

          Bond market gradually pricing in the diverging operating performances – more adjustments to come

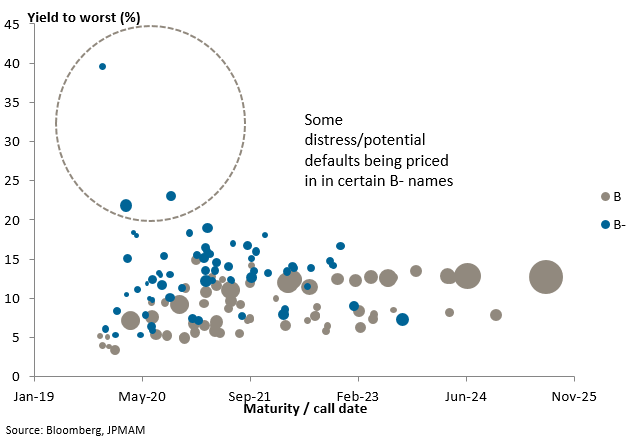
          The bond market is already starting to price-in more differentiation between issuers, but this is possibly just the beginning. Some names are already trading at relatively distressed levels, yet if some of them actually default, it could still affect the overall sentiment towards the sector.

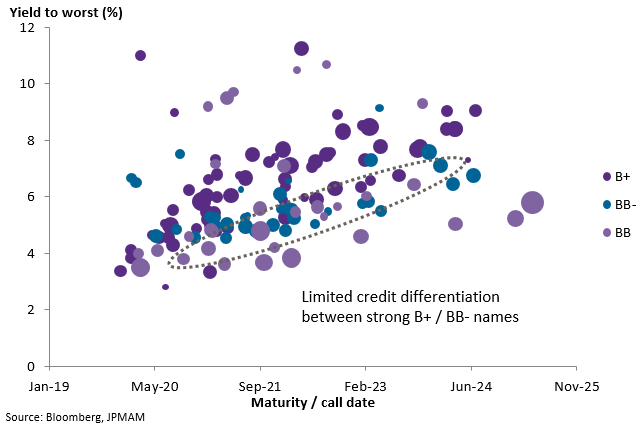
          On the other hand there seems to be relatively less differentiation between some stronger B+ names vs BB- names, possibly due to the expectation that they would eventually improve their credit metrics and later get upgraded to BB-, yet it could also be due to complacency of investors on certain names, and valuations could adjust materially if their performances do not meet expectations.

          All in all, there are still good investment opportunities within the sector; but we need to be vigilant in monitoring the company’s operational performances and make suitable credit rotations along the way, given that the competitive landscape is constantly evolving. The ability of issuers in adapting to the industry changes should play a much bigger role in credit selection going forward.

          Yield charts for various issuers with different ratings
          • APAC

          RELATED ARTICLES

          China’s Interest Rate Pivot

          While China’s post-Covid-19 economic data is showing signs of normalization, the government’s focus on stability will have significant implications for monetary policy and interest rates

          Read more

          The PBoC – Rate Cuts and Policy Clarification

          The Peoples Bank of China recent policy actions help address the concerns that its policy response was lagging the aggressive actions taken by other central banks.

          Read more

          Singapore Dollar – no longer defying gravity

          The Singapore Dollar is no longer defying gravity – we discuss why and the implications for cash investors.

          Read more